
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
LANXESS (XTRA:LXS) Stock Looks Cheap Based On Its Sales
LANXESS has seen its share price fall sharply in recent years, which naturally puts the spotlight on whether the current valuation can still be explained by its sales. With the stock now trading at €12.21, the key issue is how that price lines up with the revenue the chemical group is generating.
- The share price has declined 77.3% over the past 5 years, which raises a direct question about how much of the underlying sales power is still being recognized in the market value.
- The business model relies heavily on converting specialty chemical volumes into steady revenue streams, so any shift in pricing power, product mix or capacity utilization can meaningfully change how investors think about what its sales are worth.
- Your read on LANXESS is one view; the desks covering it have another. See what analysts think LANXESS's shares could be worth.
The issue now is whether LANXESS's current share price is reasonably explained by the scale and quality of its sales base.
If you are weighing LANXESS against other opportunities that also trade on their sales profile, it can be helpful to compare it with companies in our 181 high quality undervalued stocks
Is LANXESS Still Cheap on Sales?
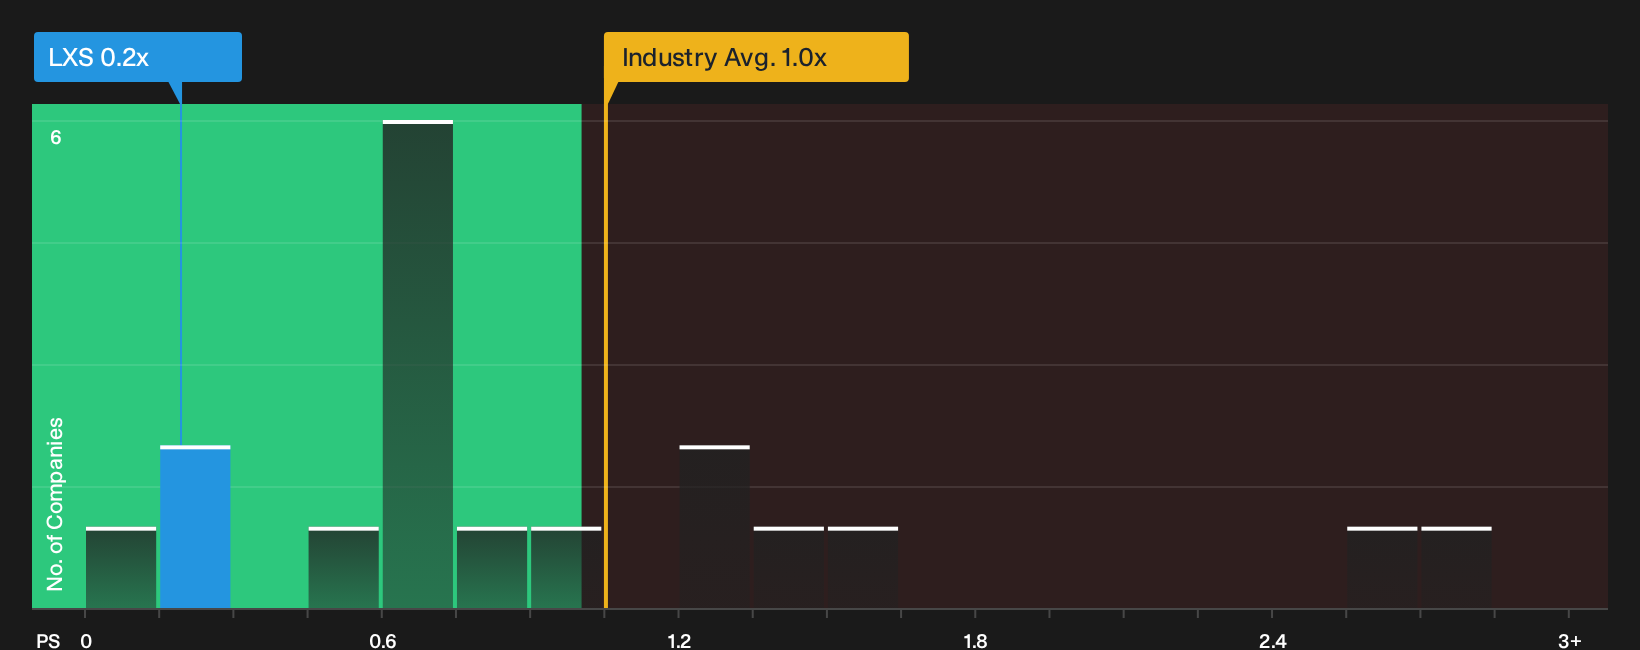
P/S fits LANXESS because investors are essentially paying for access to its revenue stream, even when earnings and book value move around. On this metric, the stock trades at about 0.2x trailing sales, which is far below both the Chemicals industry average of roughly 1.3x and the peer group around 1.1x. That gap indicates that the market assigns a much lower price tag to each euro of LANXESS revenue than to comparable businesses.
The tailored fair P/S multiple for LANXESS, which adjusts for its size, margins and risk profile, sits above the current 0.2x reading. As a result, the shares are screening as undervalued on this framework, with the market attaching a discounted value to the existing sales base relative to what this model suggests might be reasonable. That kind of spread invites closer examination of the quality and stability of those revenues, and whether the current P/S leaves room for a different view. Explore the numbers behind LANXESS's P/S valuation.
The LANXESS Narrative: What Would Justify Today's Price?
Narratives for LANXESS pick up where this valuation puzzle leaves off by spelling out the specific combinations of future growth, profitability and earnings power that would need to hold for the stock to be worth materially more or less than today's market price. Instead of a single ratio or model output, these scenarios show the future path that figure rests on so you can watch how reality lines up with it over time on Simply Wall St's Community page.
Community views on LANXESS split around how much of the restructuring and sustainability push will actually translate into stronger earnings power.
Bull case: 21% undervalued
"Strategic portfolio optimization including the divestiture of the urethane business, accelerated closure of high-cost, high-CO2 assets, and network consolidation positions LANXESS to allocate capital toward higher-margin, resilient segments..."
Discover why this Narrative puts LANXESS at 21% undervalued.
Bear case: 11% overvalued
"Intensifying competition from low-cost Asian producers, particularly from China, continues to result in price erosion and dumping in core European markets..."
Explore why this Narrative puts LANXESS at 11% overvalued.
One more piece of the LANXESS puzzle before you move on
Before you lean too heavily on where LANXESS trades on sales today, it can be useful to see how professional analysts currently map out its earnings and revenue path over the next few years. Explore where analysts expect LANXESS to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com