
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dear Accenture Stock Fans, Mark Your Calendars for Oct. 14
Accenture (ACN) is a global IT services and consulting giant that helps businesses modernize their technology, transform operations, and put artificial intelligence (AI) to work. But in 2026, the very technology it is helping companies adopt has also become a source of anxiety for its investors. As AI automates routine coding and threatens traditional billable consulting hours, concerns about weaker demand and slower enterprise IT spending have weighed on ACN stock. Yet AI is not all bad news for Accenture. Businesses still need expert help with complex data migrations, cloud modernization, and scaling AI across their operations.
Recently, sentiment has started to improve. Accenture’s latest earnings report helped restore investor confidence. At the same time, shares jumped last week after the company announced an expanded collaboration with Dell Technologies (DELL) to help businesses scale AI and modernize their infrastructure.
Now, investors have another date to circle on their calendars — Oct. 14. Accenture’s upcoming Investor Day is expected to shed more light on its long-term business strategy, AI monetization opportunities, growth guidance, and margin expansion plans. It could offer some important clues about where the company is headed.
About Accenture Stock
Accenture is a large technology and consulting company based in Dublin, Ireland. It helps businesses update the way they work and use new technology. Its work covers areas such as cloud services, cybersecurity, AI, and digital transformation.
The company works with about 9,000 clients worldwide and has roughly 814,000 employees. Its services include finance, supply chain management, engineering, business strategy, hiring and talent support, and customer experience through its Song division. As more companies explore AI, Accenture is also helping them find practical ways to use data and new digital tools.
Accenture reported about $74 billion in revenue for fiscal 2026, making it one of the biggest companies in the consulting and IT services industry. Its market capitalization stands at around $139.6 billion.
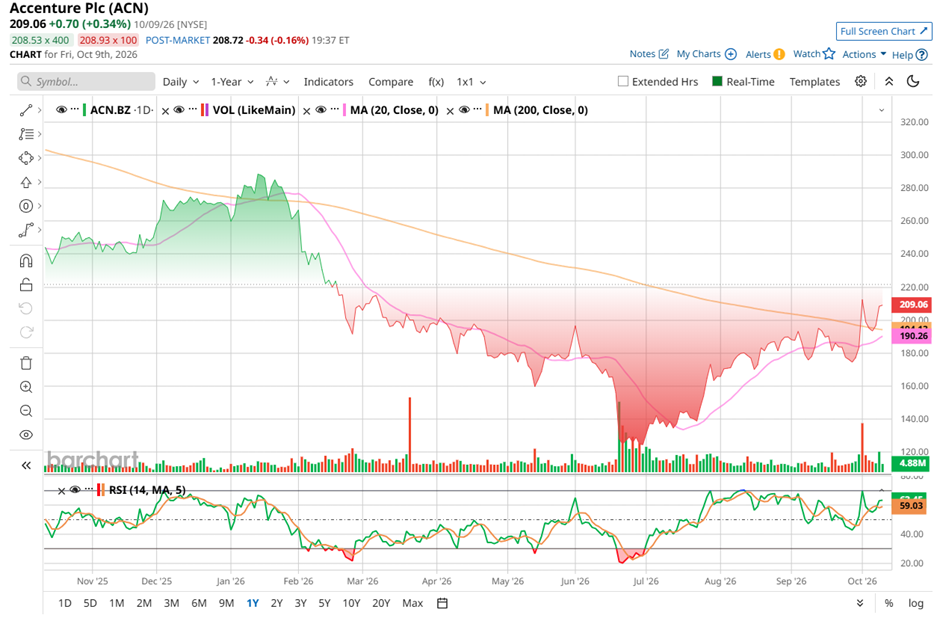
Even with a business as large as Accenture’s, a shift in investor sentiment can make quite a difference to its stock. Investors have been trying to figure out whether AI will bring Accenture more business or reduce demand for some of its traditional consulting work. Consequently, 2026 has been quite a ride for ACN shareholders. Shares climbed to a high of $291.09 in January before tumbling to a low of $118.15 in June as fears of AI disrupting traditional consulting services rattled investors. Since then, the stock has bounced back nearly 77%, although it remains 28.2% below its January peak.
The mood began to change after Accenture reported better-than-expected fiscal 2026 fourth-quarter results on Oct. 1. Its stronger-than-anticipated revenue growth outlook helped ease concerns about AI-related disruption, while highlighting continued demand from businesses seeking outside expertise to automate complex processes and accelerate AI adoption. ACN shares surged nearly 15.7% that day, followed by another roughly 6% jump on Oct. 8 after the company expanded its collaboration with Dell Technologies.
Despite this recovery, the bigger picture remains mixed. The stock is down 22.1% in 2026 and 17.1% over the past 52 weeks. However, zoom in, and the momentum looks considerably better: shares have gained 50.3% over the past three months and nearly 19% over the past month.
Meanwhile, trading volumes have shown signs of renewed buying interest, while ACN has climbed above both its 20-day and 200-day moving averages after spending much of the year below the longer-term trendline. Its 14-day RSI sits at 63, suggesting bullish momentum without yet entering the commonly used overbought zone above 70. For now, the charts suggest buyers are returning, although Accenture still has ground to recover before reclaiming its January highs.
After a bumpy year, Accenture’s stock may be catching investors’ attention for its valuation. ACN trades at 14.26 times forward adjusted earnings and 1.61 times sales, below both sector averages and its historical medians. Investors might be paying less for the company’s earnings and revenue than they typically would, potentially making the stock worth a closer look.
Income-focused investors also have something to appreciate. Accenture has paid dividends for 20 consecutive years and increased its payouts for more than a decade. This month, the company raised its quarterly dividend by 5% to $1.71 per share, payable on Nov. 13, 2026. That brings its annualized payout to $6.84 per share, translating into a forward yield of 3.7%. With a payout ratio of around 47.3%, Accenture appears to have room to continue rewarding shareholders, provided earnings and cash flow hold up.
A Closer Look at Accenture’s Q4 Earnings Report
Accenture gave its investors something to smile about when it reported its fiscal 2026 fourth-quarter results on Oct. 1. The consulting giant beat Wall Street’s expectations for both revenue and earnings, sending ACN shares soaring. After a challenging year for the stock, the results offered a welcome reminder that the business still has room to grow. Q4 revenue amounted to $18.7 billion, up 6% year over year (YOY) in U.S. dollars and 7% in local currency. EPS jumped 46% annually to $3.29.
The encouraging part was that growth was not confined to one corner of the business. Consulting revenue climbed 6% to $9.3 billion, while managed services brought in $9.4 billion, up 7%. Both segments contributed to the overall performance. Across industries, Communications, Media & Technology led with 10% revenue growth in U.S. dollars, followed by Health & Public Service at 8%. These gains suggest that businesses continue to need help upgrading their technology and modernizing their operations.
Accenture’s new bookings reached $22.2 billion in Q4, producing a book-to-bill ratio of 1.2. In simple terms, the company booked more business than it recognized as revenue during the quarter. Managed services bookings hit a record $12.8 billion, while 141 clients each signed deals worth more than $100 million.
Profitability and cash generation also remained strong. GAAP operating income rose to $2.86 billion, and the reported operating margin expanded by 370 basis points to 15.3%. Free cash flow reached $2.85 billion for the quarter and $11.62 billion for the full fiscal year. That gave Accenture room to reward shareholders, returning a record $11.5 billion through dividends and share repurchases in fiscal 2026, up 38% from the previous year.
Looking ahead, management expects fiscal 2027 revenue to grow 3% to 6% in local currency. While EPS is projected to be between $14.39 and $14.81, representing growth of 6% to 9%, adjusted EPS is expected to increase 3% to 6%. Accenture also plans to return at least $9.5 billion to shareholders.
Analysts tracking the company project Accenture’s revenue for fiscal 2027 to be $77.5 billion, while EPS is expected to grow 5.1% YOY to $14.68. In fiscal 2028, EPS is anticipated to rise another 8.2% annually to $15.88.
What Do Analysts Think About ACN Stock?
Mizuho is feeling upbeat about ACN stock, raising its price target to $241 from $226 last week while maintaining an “Outperform” rating. The brokerage firm pointed to the company’s strong Q4 fiscal 2026 results and initial fiscal 2027 outlook, arguing that its long-term prospects may be better than investors feared. As AI adoption expands and token costs decline, Mizuho expects more businesses to turn to Accenture to transform operations and scale AI solutions. Its estimates have also been updated ahead of the Oct. 14 Investor Day.
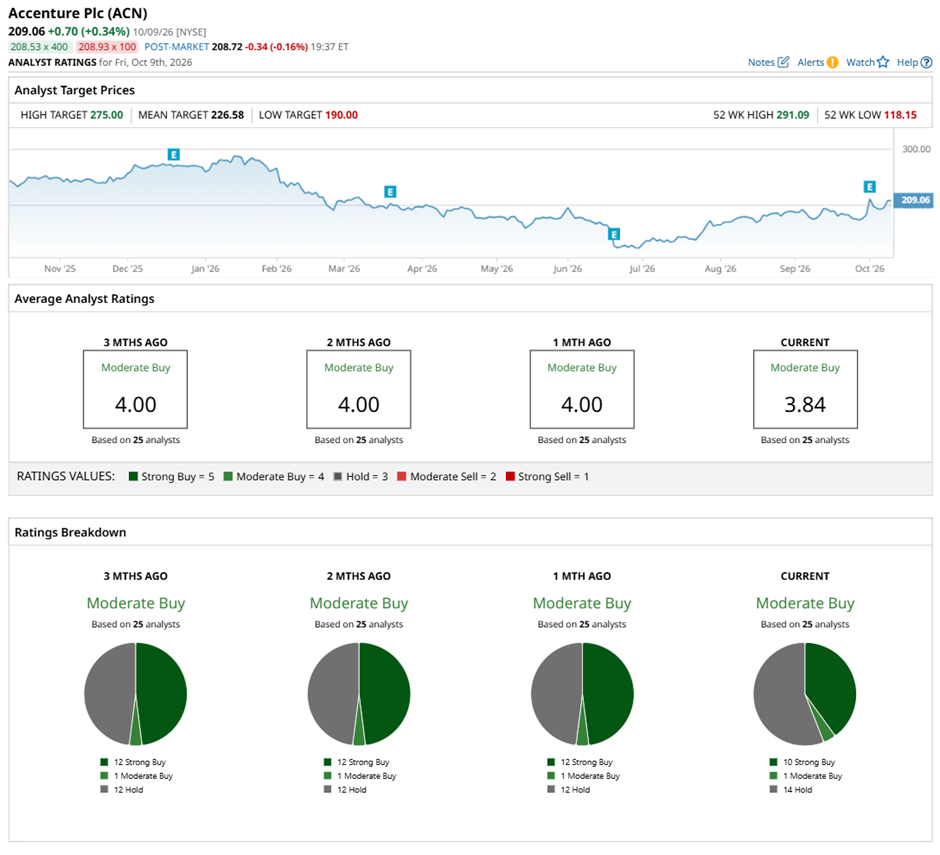
Wall Street’s outlook on ACN is cautiously optimistic, with analysts collectively assigning the stock a “Moderate Buy” rating. Among the 25 analysts covering the stock, 10 recommend a “Strong Buy,” one has a “Moderate Buy” rating, and 14 advise a “Hold.”
The mean price target of $226.58 suggests an upside potential of 8.3% from the current price levels. The Street-high target price of $275 for ACN implies the stock could rally as much as 31.5%.
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.