
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Solar JV Expansion Require Action From KKR (KKR) Investors?
- TotalEnergies and KKR agreed in October 2026 to add 700 MW of U.S. utility scale solar to their 50/50 joint venture, increasing the portfolio from 1.4 GW to closer to 2.1 GW, in a deal valuing the added assets at about US$1.2b.
- The expanded solar partnership gives KKR more exposure to contracted, or to be marketed, power generation, tying its fee streams more closely to real economy energy demand rather than short term capital markets activity.
- We will now examine how KKR's investment narrative could be affected by this larger U.S. solar platform and the associated long term cash flows.
Scan how KKR’s push into large scale renewables compares with other potential breakouts in the energy transition by reviewing the hand picked 43 power grid technology and infrastructure stocks shaping tomorrow’s grid.
KKR Investment Narrative Recap
To own KKR you need to be comfortable with a manager that leans heavily on alternatives, uses higher risk funding rather than deposits, and can see swings in fee and performance income. The near term story still hinges on fundraising momentum in private credit and asset based finance and how that offsets expected declines in reported revenue.
The biggest operational risk remains asset quality and liquidity across the fast growing credit and ABF platforms, especially if riskier deals underperform and write downs hit earnings. The latest U.S. solar expansion does not radically change that picture, although it slightly deepens KKR's exposure to long term contracted infrastructure style cash flows.
The renewables joint venture expansion with TotalEnergies looks most relevant here because it adds scale to KKR's energy transition footprint while keeping capital intensity shared in a 50/50 structure. For investors watching catalysts, the key question is whether this sort of contracted power platform can make fee related earnings a bit smoother and less tied to exit markets.
Set against that, the bid interest in Uniper with RWE and the complex Telecom Italia network deal through FiberCop show how busy the firm already is in capital intensive, regulated sectors. Execution risk stacks up. Integration progress and any updates on asset performance in these areas, alongside the solar JV build out, are likely to matter more than sentiment swings in the KKR share price.
KKR's narrative projects US$9.4b revenue and US$6.0b earnings by 2029. That path assumes annual revenue declines of 28.6% and an earnings increase of US$3.0b from US$3.0b today.
Uncover why KKR's fair value indicates a 37% potential upside to its current price, which could narrow quickly.
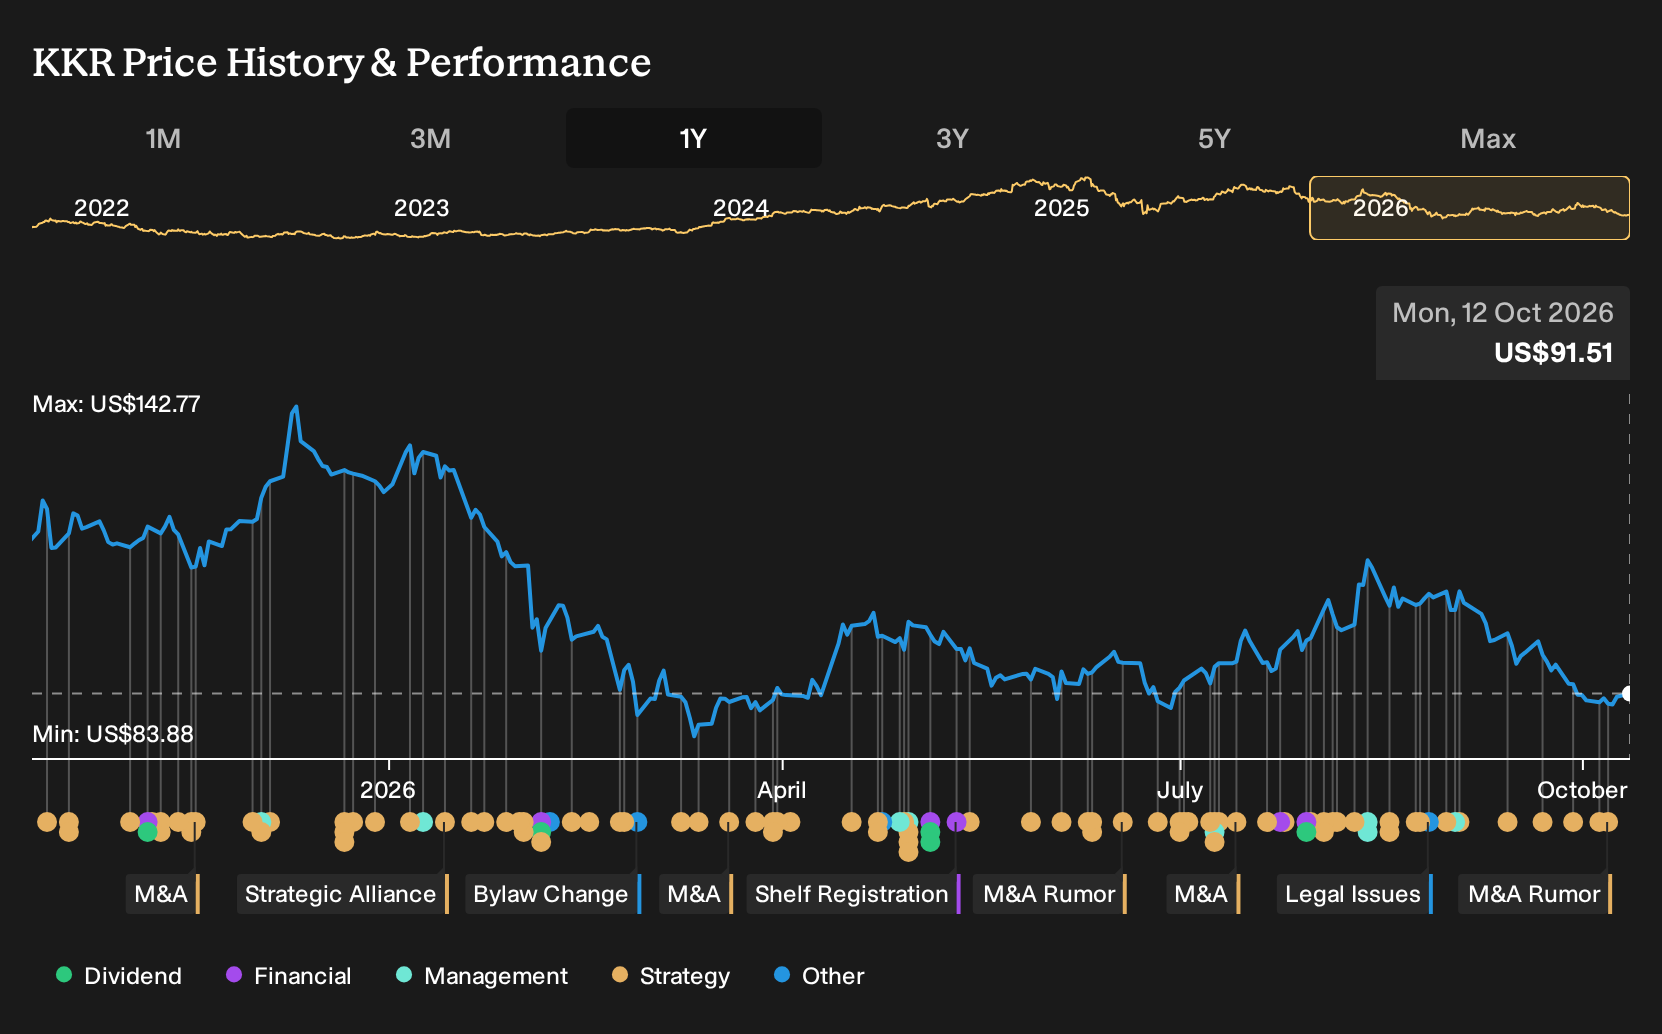
Exploring Other Perspectives
Some of the most optimistic analysts frame KKR’s real catalyst as faster monetization of its broader platform, not just energy transition deals. Before this solar JV news, the bullish cohort was already pencilling in US$11.3b of revenue and US$6.2b of earnings by 2029. You can treat this expansion as a fresh test of that upbeat storyline.
Explore 5 other KKR fair value estimates, including one that suggests up to 69% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your KKR research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KKR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KKR's overall financial health at a glance.
Looking For More Investment Ideas Beyond KKR?
Once you have formed a view on KKR, it can help to widen the lens and compare that thesis with other opportunities that match your risk and income preferences. The Simply Wall St Screener lets you filter for the traits that matter most to you, then quickly see which businesses line up with your criteria.
- If you want potential mispricing combined with quality fundamentals, start by scanning a curated set of 29 high quality undervalued stocks that already clear basic balance sheet and earnings checks.
- For readers who prefer income over headlines, focus on cash return potential with our collection of 8 dividend fortresses that offer higher yields supported by underlying financial data.
- If capital protection is a priority, concentrate on stability using a 31 resilient stocks with low risk scores that screens for lower risk scores and more resilient business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com