
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SoftBank Group (TSE:9984) Dropped, So Why Is It Back In Focus?
Why SoftBank Group Stock Is Back in Focus
SoftBank Group (TSE:9984) has drawn fresh attention after an 8.5% slide, alongside a wider selloff in AI linked chipmakers, just as the conglomerate reshapes its debt through redemptions and new yen bond issuance.
The recent 1 month share price return of SoftBank Group is down 18.4%, with the 7 day move down 15.2% and the latest drop tied to a broader pullback in AI exposed chip stocks, even as the group redeems a €405.1m euro bond and issues new unsecured yen bonds.
Despite this sharp setback, the stock still shows a 15.7% year to date share price gain and a 5 year total shareholder return of 241.3%, which indicates that long term investors have so far been rewarded, even as short term momentum fades.
Scan how other AI exposed plays are reacting to this pullback by reviewing the hand picked 13 AI small caps that share some of SoftBank Group's key themes.The recent slide leaves SoftBank Group trading well below the average analyst target and far away from some intrinsic value estimates. After this kind of gap opens up, where does fair value really sit?
Most Popular Narrative: 31.4% Undervalued
On the most followed view, SoftBank Group’s fair value of ¥7,782.47 sits well above the last close at ¥5,338. This puts the current slide against a backdrop of AI heavy assets that drive much of that estimate.
SB Energy’s planned Nasdaq listing, backed by roughly 8.8 GW of contracted AI data center capacity and an estimated US$430b lease revenue backlog that is still to be realized, offers a path for SoftBank Group to crystallize part of this embedded value and potentially improve reported NAV and investment gains.
See why 23 investors see SoftBank Group as 31% undervalued.
Result: Fair Value of ¥7,782.47 (UNDERVALUED)
Still, this hinges on SoftBank Group keeping funding costs in check and avoiding delays to major AI related liquidity events, such as the OpenAI and SB Energy listings.
Find out about the key risks to this SoftBank Group narrative.
Another View: What Our DCF Says About SoftBank Group
The analyst narrative describes SoftBank Group as 31.4% undervalued at a fair value of ¥7,782.47, but the Simply Wall St DCF model points the other way. On that cash flow view, the shares at ¥5,338 trade above an estimated value of ¥2,493.27, which implies overvaluation.
One approach relies on earnings and multiples, while the other focuses on modeled cash generation. When two frameworks disagree this sharply, which yardstick do you trust more for sizing any position?
Look into how the SWS DCF model arrives at its fair value.
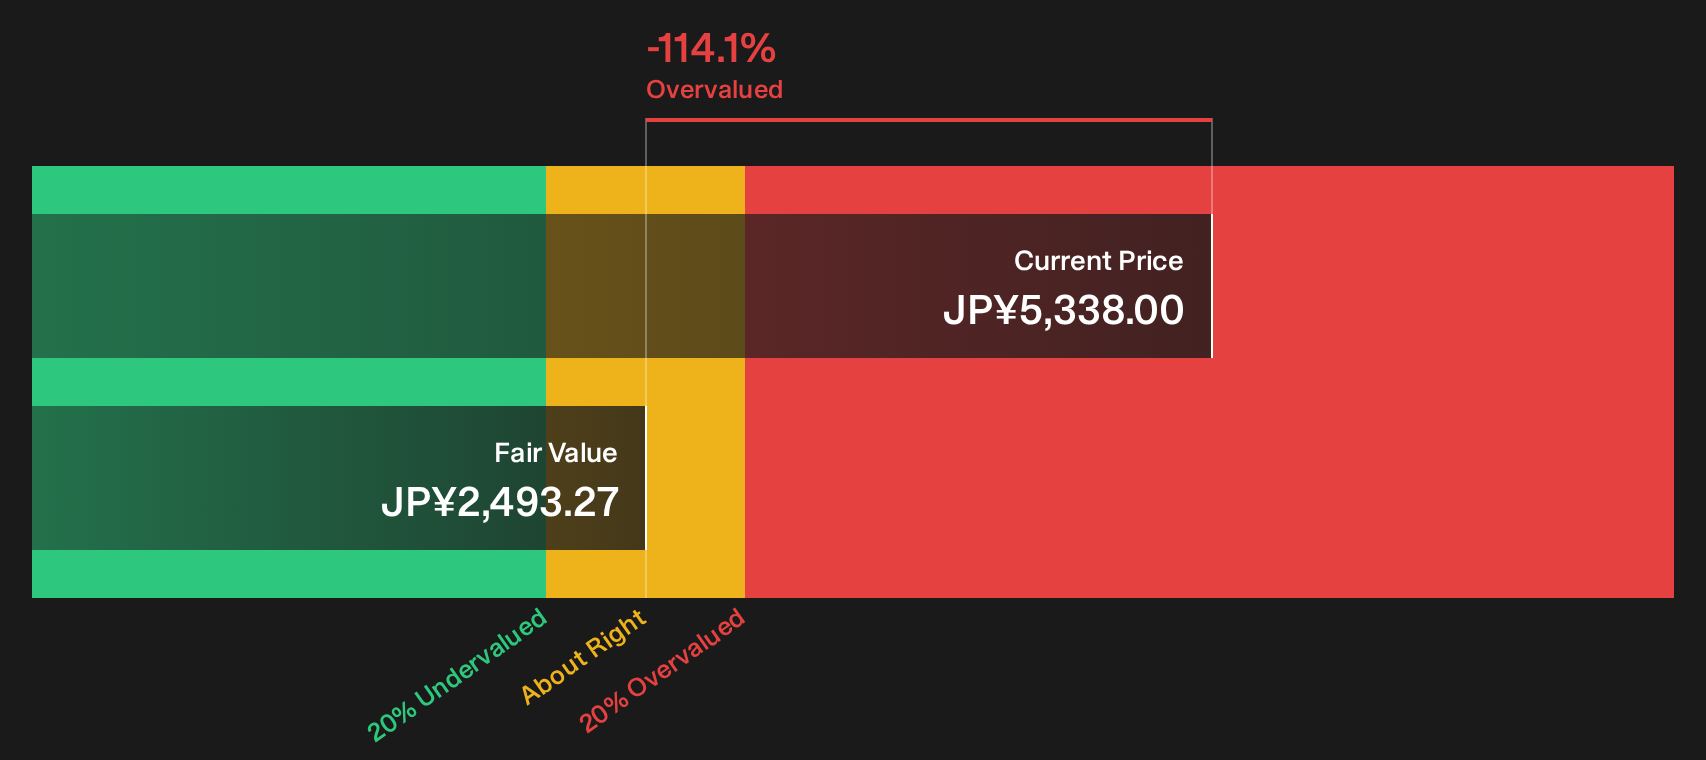
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SoftBank Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on SoftBank Group is split, with some investors focused on potential upside and others worried about clear pressure points. Move quickly and review the underlying data to form your own takeaway using the 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond SoftBank Group?
If SoftBank Group has sharpened your appetite for opportunity, do not stop here. Use the screener to hunt for fresh ideas that fit your style.
- Target long term resilience by reviewing a 23 resilient stocks with low risk scores that may help you stay invested through rough patches without constantly second guessing every move.
- Spot potential mispricing early and scan a 74 high quality undiscovered gems before the crowd starts paying attention and pricing in the quality already on the table.
- Build a portfolio that can potentially pay you to wait by filtering for a 27 dividend fortresses that lines up with your income goals and risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com