
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SEGRO (LSE:SGRO) Draws Takeover Attention, Is The Upside Already Priced In?
SEGRO (LSE:SGRO) is back in focus after several institutions, including Millennium International Management, Natixis and Nuveen, disclosed positions under Rule 8.3 of the Takeover Code in connection with an offer involving Prologis.
Recent trading indicates that investors are paying attention to SEGRO again. The share price has climbed 30.84% year to date, with an 8.34% 90 day share price return and a 47.08% 1 year total shareholder return, pointing to strong momentum rather than a short lived reaction to the takeover related disclosures.
Spot similar warehouse and logistics plays attracting institutional attention by scanning our curated list of list of solid balance sheet and fundamentals (9 results).SEGRO has already run hard this year, and the takeover angle has only sharpened the move. The next issue is simple: Does that recent jump leave enough value on the table today, or does patience make more sense?
Most Popular Narrative: 1% Undervalued
On the numbers, SEGRO's latest narrative fair value of £9.39 sits just above the recent close at £9.32, which points to a market price that is only slightly behind the implied worth of the property portfolio and data infrastructure potential.
The physical world is increasingly struggling to bear the exponential weight of the digital world. In our previous analyses, we argued that UK-based Segro (SGRO.LN), with its 190 MVA (Mega Volt Ampere) grid reserve and 1.2 GW of data center development capacity, would transform from a traditional warehouse lessor ("Powered Shell" model) into a fully fitted energy and data infrastructure player.
See why 12 investors see SEGRO as 1% undervalued.
Result: Fair Value of £9.39 (ABOUT RIGHT)
Still, SEGRO's data centre thesis could be upset if power grid access proves slower or costlier than expected, or if regulators push back on large scale developments.
Find out about the key risks to this SEGRO narrative.
Another View: SEGRO looks expensive on earnings
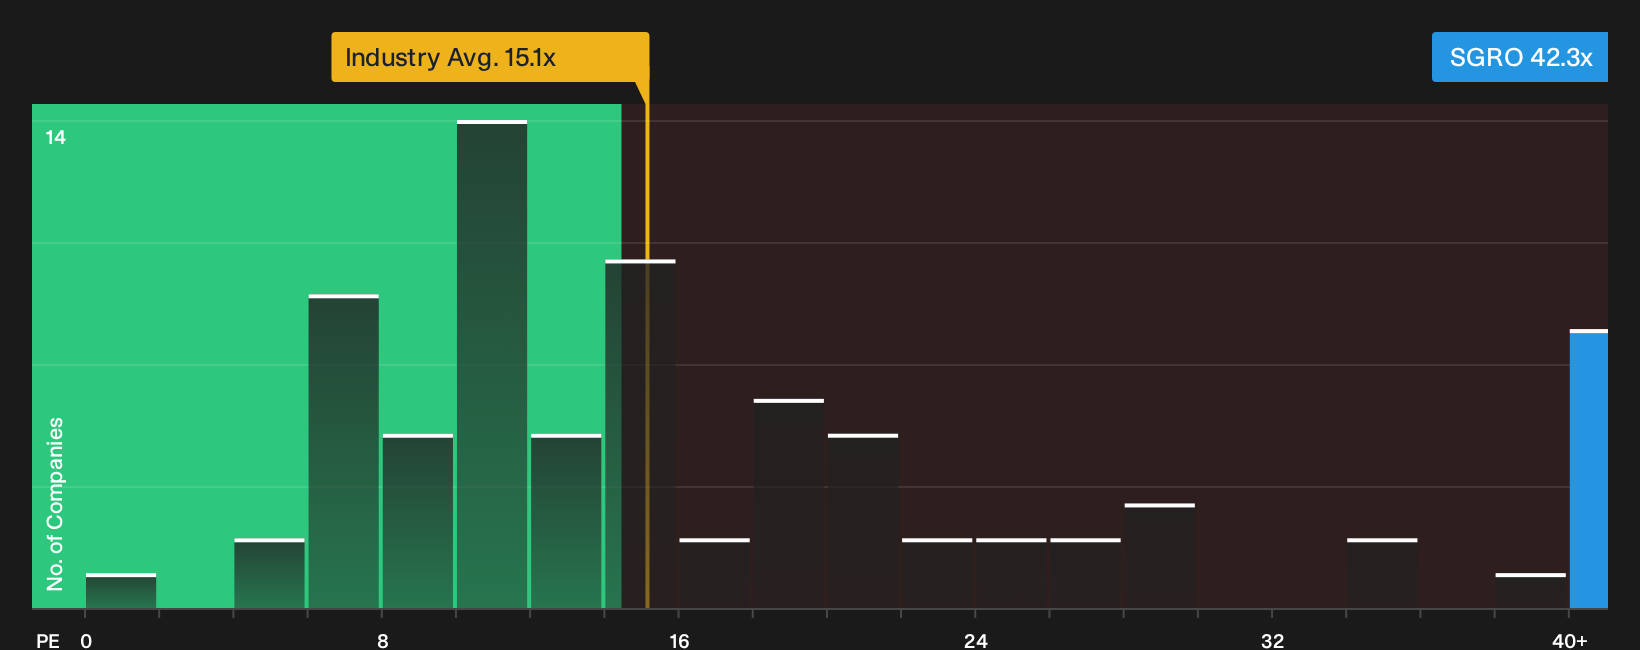
On a simple earnings yardstick, SEGRO tells a very different story. The shares trade on a P/E of 42.3x, compared with 15x for global Industrial REITs and a fair ratio of 18x. That gap points to meaningful valuation risk if enthusiasm for the AI and data centre angle cools.
Given that kind of premium, investors have to decide whether SEGRO's quality and growth profile justify paying more than double both peers and the fair ratio, or whether this is the point to demand a wider margin of safety.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SEGRO's value and risk profile. Use this as a jumping off point, move fast, and weigh both the upside and the downside yourself with 2 key rewards and 3 important warning signs
Looking for more SEGRO sized investment ideas?
If SEGRO has sharpened your focus on where capital is flowing, do not stop here. The next move you make across the market could matter more.
- Target resilient balance sheets and steadier sleep at night by scanning our 4 resilient stocks with low risk scores that screens for companies with lower risk profiles.
- Hunt for quality at a discount and stress test your value instincts with a curated 5 high quality undiscovered gems that filters for stronger fundamentals.
- Lock in income potential and keep your cash working through a focused 1 dividend fortresses built around higher yield opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com