
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Torex Gold Resources Stock As New Mine Ramps Up
- Torex Gold Resources recently confirmed the successful completion and ramp up of its Media Luna project at the Morelos Complex in Mexico, supporting higher output in gold, copper, and silver with an extended operating life for the asset.
- The Media Luna transition shifts Torex Gold Resources further toward an underground, infrastructure heavy operation, raising the importance of cost control, execution quality, and consistent plant performance for future cash generation.
- We will now look at how Torex Gold Resources' investment narrative could be reshaped by the completed ramp up at Media Luna.
Torex Gold Resources Investment Narrative Recap
To be a shareholder in Torex Gold Resources, you need to be comfortable with a single complex asset, the Morelos Complex in Mexico, doing most of the heavy lifting. The investment case hinges on stable production and disciplined spending at Media Luna now that ramp up is complete, so that higher volumes actually translate into durable cash generation.
In the near term, the main catalyst is consistent underground output and plant performance from Media Luna, supported by infrastructure such as the paste backfill plant and ore passes. The biggest risk is that all-in sustaining costs stay elevated through ramp up or that execution issues at new infrastructure undo the benefits of the higher production base.
The completion and ramp up of Media Luna is the announcement that matters most here because it directly addresses earlier concerns about timing and execution risk. With this phase done, the story tilts more toward how well Torex Gold Resources can run what it has built, and less toward whether it can finish on schedule.
That success also frames every other potential catalyst, from efficiency projects and automation to any future work at adjacent deposits. If management can hold the line on non-sustaining capex and keep cost inflation contained while Media Luna runs steadily, the operational narrative shifts from project risk toward the quality and longevity of the Morelos Complex cash flows.
What The Media Luna Ramp Up Means For Torex Gold Resources' Forecasts
Torex Gold Resources now has analyst expectations that lean heavily on Media Luna running consistently rather than simply getting built. The consensus view ties the successful ramp up to a steady 6.4% yearly increase in revenue over the next three years, alongside only a small projected squeeze in profit margins from 33.0% today to 32.4% by 2029, which keeps profitability at the center of the story.
Forecasts in the stock research point to earnings today of $602.5 million and a consensus target of $713.1 million by 2029, which is an earnings increase of about $110.6 million over that period. The implied fair value work uses that 2029 profit figure together with an assumed P/E of 9.5x, which is below the current 16.5x industry multiple for Canadian metals and mining groups, so the narrative leans on Media Luna being run efficiently rather than on Torex Gold Resources being re-rated to a premium.
Torex Gold Resources' narrative projects $2.2 billion revenue and $713.1 million earnings by 2029. This assumes 6.4% yearly revenue growth and an earnings increase of about $110.6 million from $602.5 million today.
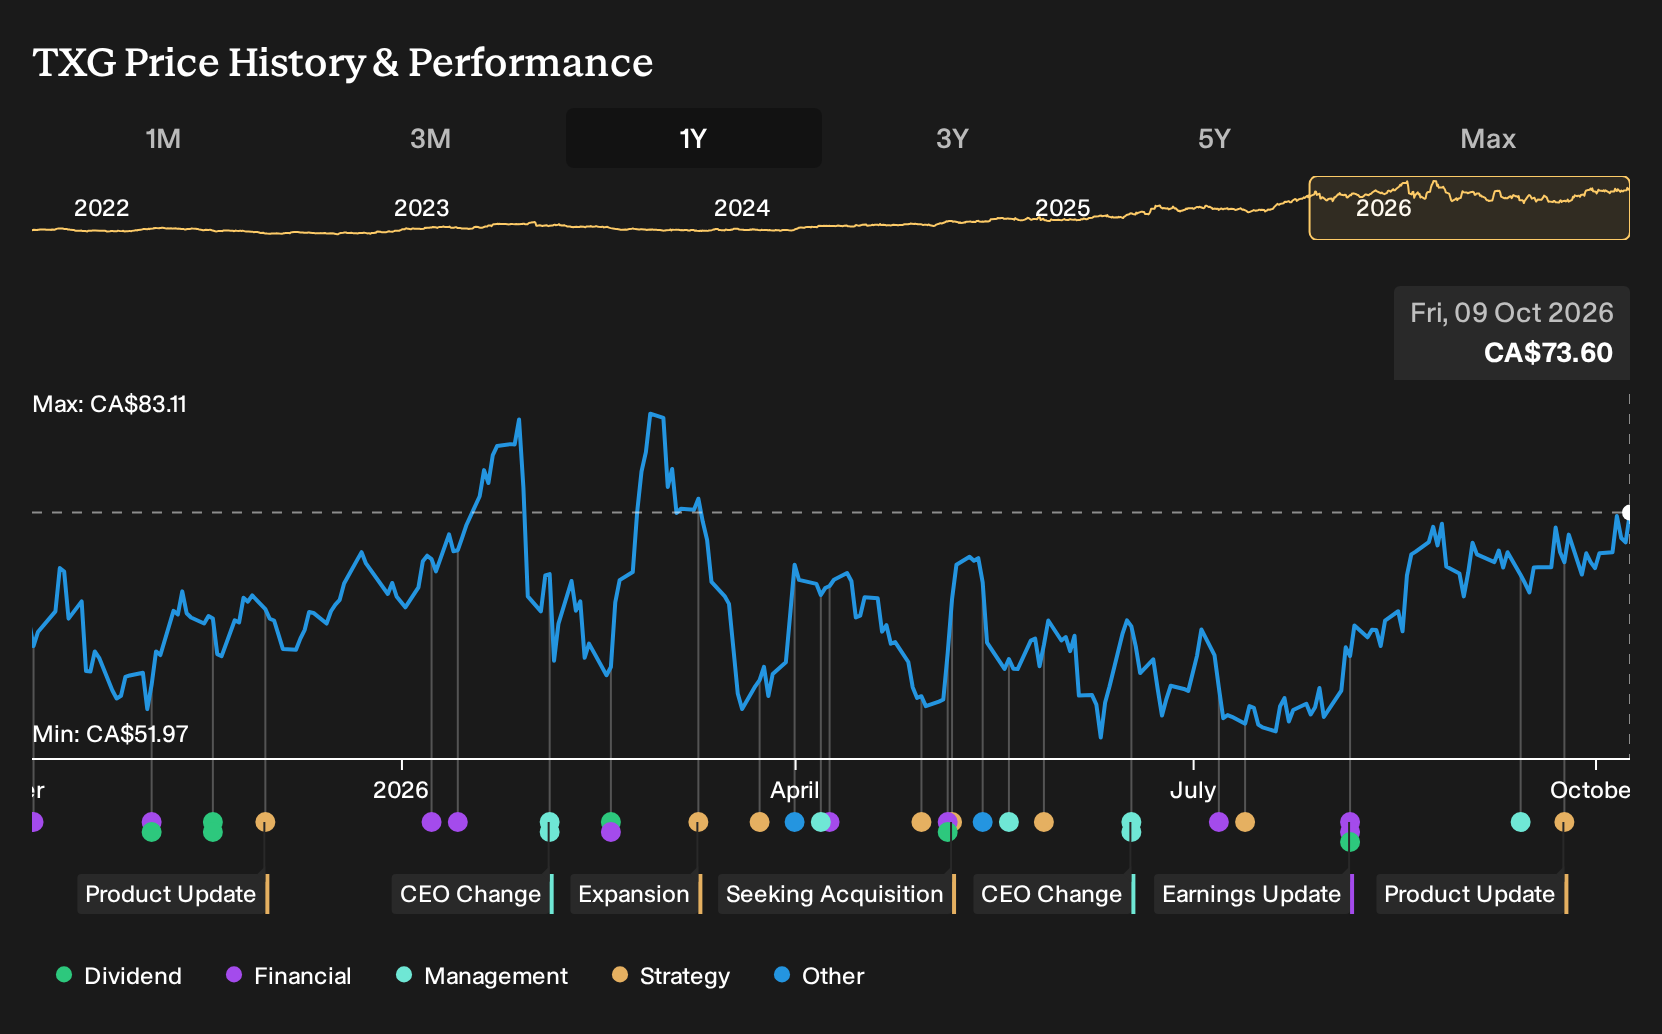
Analysts also map this earnings profile into a consensus price target of CA$92.36 per share on Torex Gold Resources, with a range from CA$83.00 to CA$100.00. That range reflects different views on how smoothly Media Luna and the broader Morelos Complex can run in practice and on how much value to assign to the expected 3.69% yearly reduction in shares outstanding over the next three years, which would amplify per share outcomes if the operational plan holds together.
Uncover why Torex Gold Resources' fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about CA$73.69 and CA$93.70, with one view reaching the very top of that band. Torex Gold Resources now faces real world tests around all in sustaining costs, Mexican regulation, and project integration. Opinions will differ, so explore several viewpoints before committing capital.
Explore 2 other Torex Gold Resources fair value estimates, including one that suggests as much as 27% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Torex Gold Resources research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Torex Gold Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Torex Gold Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Torex Gold Resources?
If Torex Gold Resources has sharpened your interest in metals, cash flows, and balance sheet strength, use that same lens across a broader watchlist. The Simply Wall St Screener can help you filter for specific traits so you spend time on companies that actually fit your approach rather than scrolling through tickers at random.
- For those hunting for strong fundamentals at a sensible price, start with a curated set of value focused opportunities through the 8 high quality undervalued stocks.
- If resilience and risk control matter most to you, aim your research at businesses with steadier profiles by scanning the 8 resilient stocks with low risk scores.
- When you want quality operations that may not yet be widely followed, widen your horizons with the 10 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com