
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Apple (AAPL) iPhone Production Cuts
- Apple has reduced component orders and production for its recently launched iPhone 18 Pro models after weaker than expected demand and sharply higher memory chip costs that are linked to heavy AI data center usage.
- This pullback in premium iPhone volumes comes as Apple prepares to launch the new foldable iPhone Duo, tightening the balance between high pricing, unit demand, and near term profitability for its flagship hardware line.
- We will now look at how Apple’s investment narrative could be affected by weaker iPhone 18 Pro demand and production cuts.
Broaden your playbook beyond Apple by scanning hand-picked mega-cap peers and potential challengers powered by AI and mobile data demand through 92 AI infrastructure stocks.
Apple Investment Narrative Recap
To own Apple today, you need to believe the ecosystem around iPhone, Macs, wearables, and services can offset bumps in any single product cycle. Softer iPhone 18 Pro demand and higher memory costs put the spotlight on how Apple balances pricing, volumes, and margins through this upgrade cycle.
The key short term catalyst is execution on Apple Intelligence, new devices like iPhone Duo, and smart home hardware that can deepen attachment to the platform. The biggest risk remains prolonged memory cost pressure combined with pushback on higher flagship prices. The latest production cuts make that margin versus volume trade off more immediate, but not yet transformative.
The Dolby Atmos and Dolby Vision expansion for Formula 1 on Apple TV ties directly to that ecosystem story. Live sports in 4K with premium audio give the services unit a clearer hook, especially as Apple TV becomes the exclusive U.S. home for F1 with every session available to subscribers.
For investors, this matters because it shows Apple leaning into content quality, not just device specs, as a potential catalyst. Execution in this area can support engagement on Apple TV hardware, the coming Apple TV 4K refresh, and the broader services portfolio. That, in turn, can help cushion any short term pressure from iPhone mix shifts and hardware promotions.
What Current Forecasts Assume About Apple
Apple's consensus roadmap has clear numbers attached to it. Analysts are penciling in 9.8% yearly revenue growth over the next three years, while also baking in a slight squeeze on profitability as margins move from 27.6% today to 26.6% over that period.
On earnings, the group view is that net income rises from US$128.9b today to US$164.4b by 2029. That is an increase of roughly US$35.5b in profit over the period, with earnings per share expected to reach US$12.06 as buybacks trim the share count by about 1.23% each year for the next three years.
Valuation assumptions line up with those operating forecasts. The analyst pack is working off a 2029 revenue figure of US$618.2b and the same US$164.4b earnings target, discounted back using an 8.6% rate to support an average price target of US$328.09. That implies Apple would trade on a P/E of 35.9x those 2029 earnings, compared with 37.8x today and above the 26.7x multiple cited for the broader US tech sector.
Apple's narrative projects US$618.2b revenue and US$164.4b earnings by 2029. This requires 9.8% yearly revenue growth and an earnings increase of about US$35.5b from US$128.9b today.
Uncover why Apple's fair value indicates a 4% potential downside to its current price, suggesting that this premium may not be sustainable.
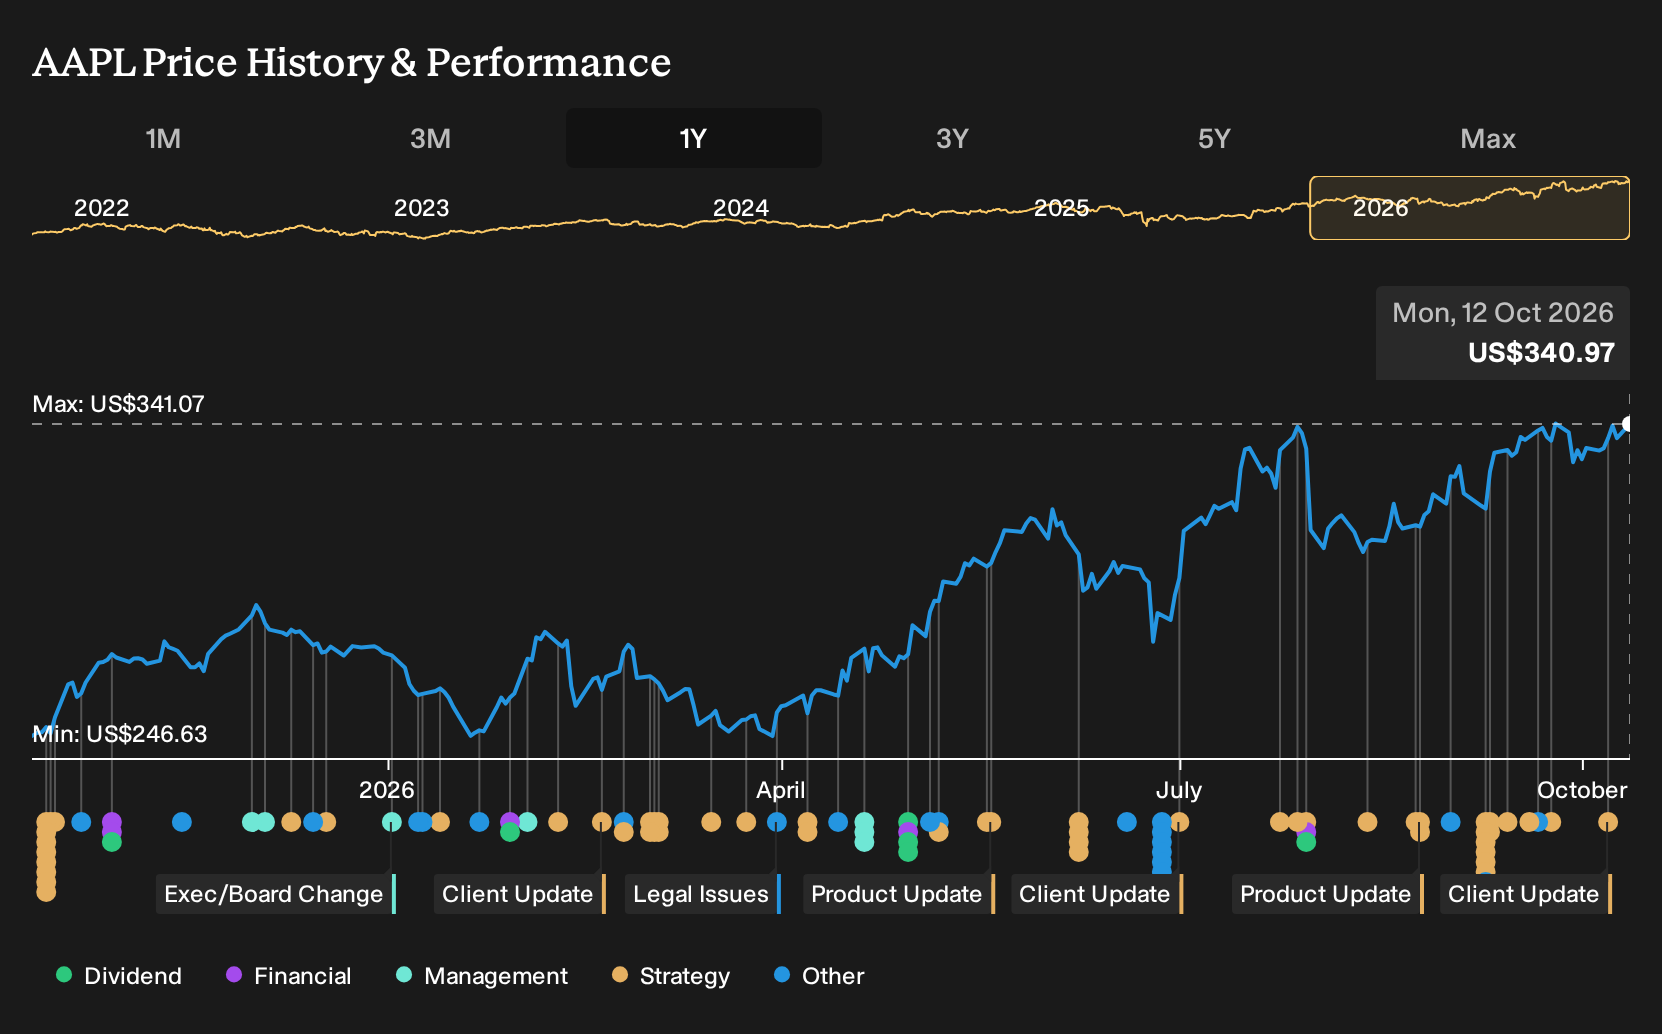
Exploring Other Perspectives
One alternate view treats Apple’s new smart home push and Dolby Atmos Formula 1 coverage as a weaker offset to hardware strain. Those more cautious analysts were already working with about US$623.9b in 2029 revenue and US$156.0b in earnings, yet still saw a much lower fair value. Your own take might shift as this latest iPhone 18 Pro news feeds into fresh forecasts, so treat these spreads as a reminder to compare several stories before you commit capital.
Explore 42 other Apple fair value estimates, including one that suggests as much as 46% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Apple research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Apple. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Apple's overall financial health at a glance.
Looking for more investment ideas beyond Apple?
Apple can anchor a portfolio, but your risk and return profile will often depend on the rest of your watchlist. If you want to balance concentration in a single mega cap with a broader mix of opportunities, the Simply Wall St Screener offers several focused ways to surface stocks that might fit different roles in your plan.
- If capital protection sits high on your priority list, consider building a shortlist using a screener focused on 31 resilient stocks with low risk scores.
- For investors who care most about quality at a sensible entry point, filter for companies that currently screen as 29 high quality undervalued stocks.
- Those seeking a pipeline of potential future leaders can start with a curated pool of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com