
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bodycote (LSE:BOY), Why Is The Market Paying Closer Attention?
Bodycote (LSE:BOY) is back in focus after several hedge funds, including Millennium International Management, Balyasny Asset Management and Qube Research & Technologies, disclosed sizeable cash settled derivative positions under the UK Takeover Code.
At a £9.11 share price, Bodycote has given investors a 38.98% 90 day share price return and a 42.16% total shareholder return over one year. As a result, the recent hedge fund disclosures land on a stock where momentum has been building rather than fading.
Spot opportunities where hedge fund interest and recent momentum are already lining up by scanning our hand picked 7 high quality undervalued stocks with solid cash flows and balance sheets.
Bulls point to Bodycote’s solid revenue and net income, while bears focus on how much of that strength is already in the £9.11 price. The numbers start to tip the argument once valuation enters the frame.
Most Popular Narrative: 3% Overvalued
The most followed narrative for Bodycote now points to a fair value of £8.87, slightly below the £9.11 last close, which puts the spotlight on whether investors are paying a small premium for execution and capital allocation.
The expanded Optimise program, including site consolidations and divestitures of low-margin and structurally lower-growth assets, is set to deliver at least £15 million in recurring annual cost benefits by mid-2027, materially boosting EBIT margins and cash flow. Bodycote's rollout of its Carbon Smart program, offering customers reduced carbon footprint heat treatment solutions, aligns with growing sustainability and electrification trends across automotive and industrial sectors. This positioning enables the company to maintain pricing power, win new business, and protect or expand margins as decarbonization pressures mount.
See why 11 investors see Bodycote as 3% overvalued.
Result: Fair Value of £8.87 (OVERVALUED)
Still, the narrative around Bodycote can easily shift if exposure to weaker Western European automotive and industrial demand drags revenue, or if rising compliance and restructuring costs weigh on cash generation.
Find out about the key risks to this Bodycote narrative.
Another View: Bodycote Through The Cash Flow Lens
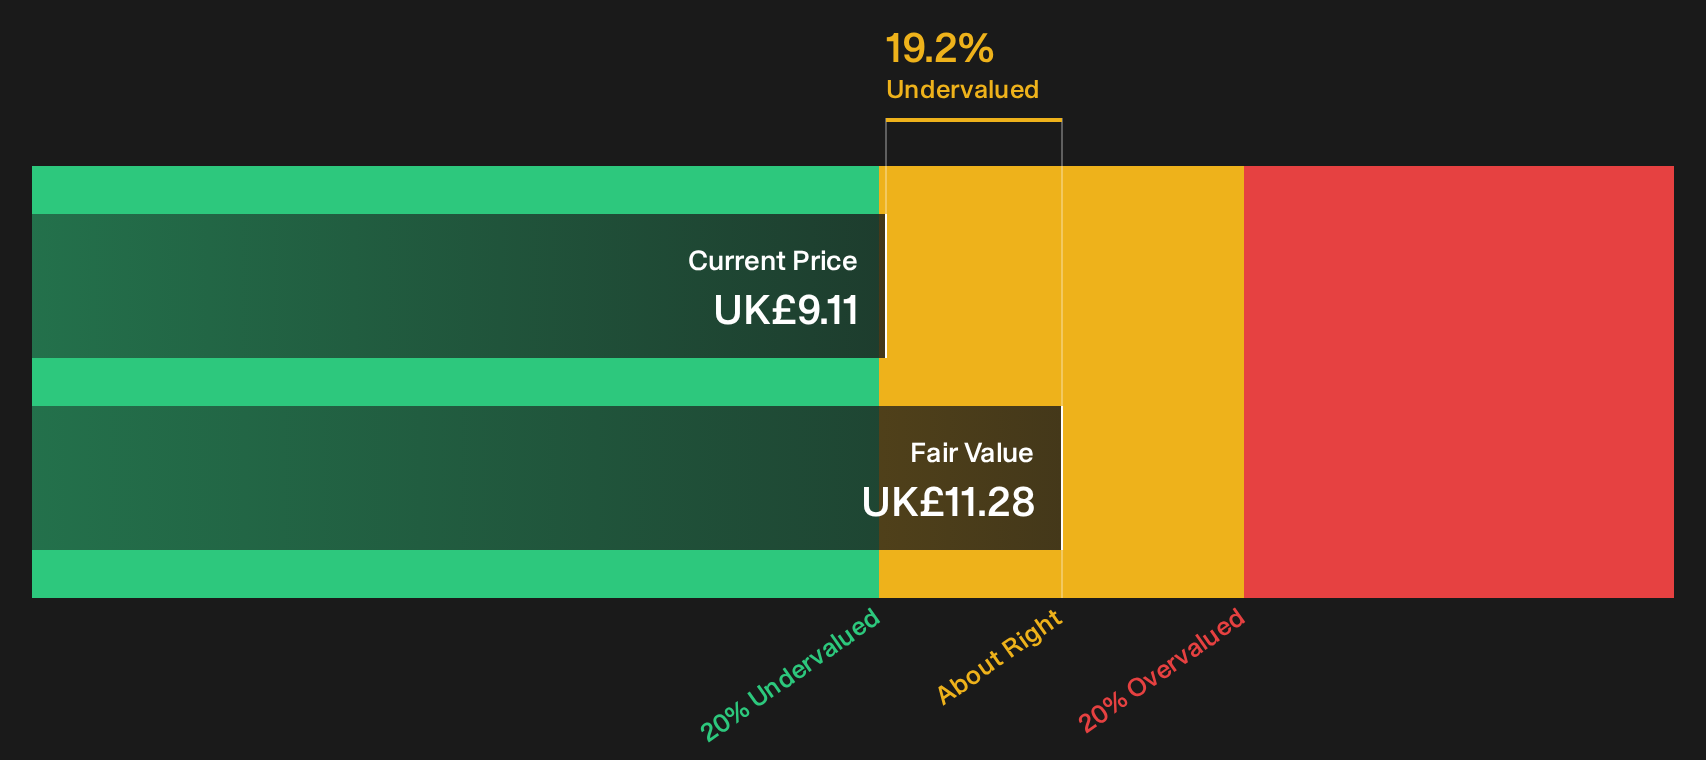
Price-based ratios flag Bodycote as slightly expensive, yet the SWS DCF model points the other way. On that cash flow view, the shares trade about 19.2% below an estimated fair value of £11.28, which hints at a possible disconnect between headline multiples and underlying cash generation. Which signal do you trust more when the market disagrees?
For readers who want to see how that cash flow estimate is built step by step, Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bodycote for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum and mixed signals around Bodycote can feel exciting, but the real edge comes from testing the numbers yourself and moving decisively once you have a view, especially when the data flag 3 key rewards and 2 important warning signs
Looking for more Bodycote sized investment ideas?
Do not stop your research at Bodycote. Broaden your watchlist with focused stock ideas so you are ready when the next opportunity lines up.
- Target potential upside in overlooked opportunities by scanning the 5 high quality undiscovered gems before attention and expectations catch up.
- Prioritise resilience by reviewing the 4 resilient stocks with low risk scores that aim to pair sturdier fundamentals with lower risk profiles.
- Strengthen your core holdings by checking the list of solid balance sheet and fundamentals (9 results) that combine firmer financial footing with consistent fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com