
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SLB (SLB) Could Be 22% Undervalued As TotalEnergies And Exxon Wins Add Support
What the TotalEnergies and ExxonMobil wins mean for SLB
SLB (SLB) just picked up two high profile contracts: a global DrillPlan deployment with TotalEnergies and subsea work on ExxonMobil’s Rovuma LNG project in Mozambique, putting its digital and subsea offerings in focus.
These contract wins arrive after a choppy spell for SLB’s share price, which is up 21.32% year to date but down 13% over the past month. The 1 year total shareholder return of 54.83% contrasts with a 3 year total shareholder return decline of 11.39%, while the 5 year total shareholder return of 59.44% points to long term momentum with some recent re-rating risk.
Compare SLB’s digital and subsea push with peers by scanning our hand picked list of 20 high quality undiscovered gems across the wider energy supply chain.
Bulls point to SLB’s digital and subsea wins and a 54.83% 1 year return, while bears point to the recent 13% pullback and 3 year decline. Which story does the current valuation support?
Most Popular Narrative: 22% Undervalued
SLB last closed at $48.77, while the most followed narrative pegs fair value at $62.41. The contract news therefore lands against a backdrop of implied upside and a higher required return of 7.63% baked into that model.
Rapid scaling of SLB’s Data Center Solutions business, backed by a backlog that underpins an annualized revenue run rate exceeding US$2 billion by the end of 2027 and medium term targets of US$4.5 billion to US$5.0 billion of data center revenue and US$700 million to US$800 million of adjusted EBITDA in 2028 after the Kelvion acquisition, introduces a large, capital light revenue stream that can add meaningfully to consolidated revenue, EBITDA and cash generation.
See why 161 investors see SLB as 22% undervalued.
Result: Fair Value of $62.41 (UNDERVALUED)
Still, the SLB story can break if Middle East disruption drags on or if data center and Kelvion integration targets prove harder to deliver.
Find out about the key risks to this SLB narrative.
Another View on SLB: Is the P/E Telling a Different Story?
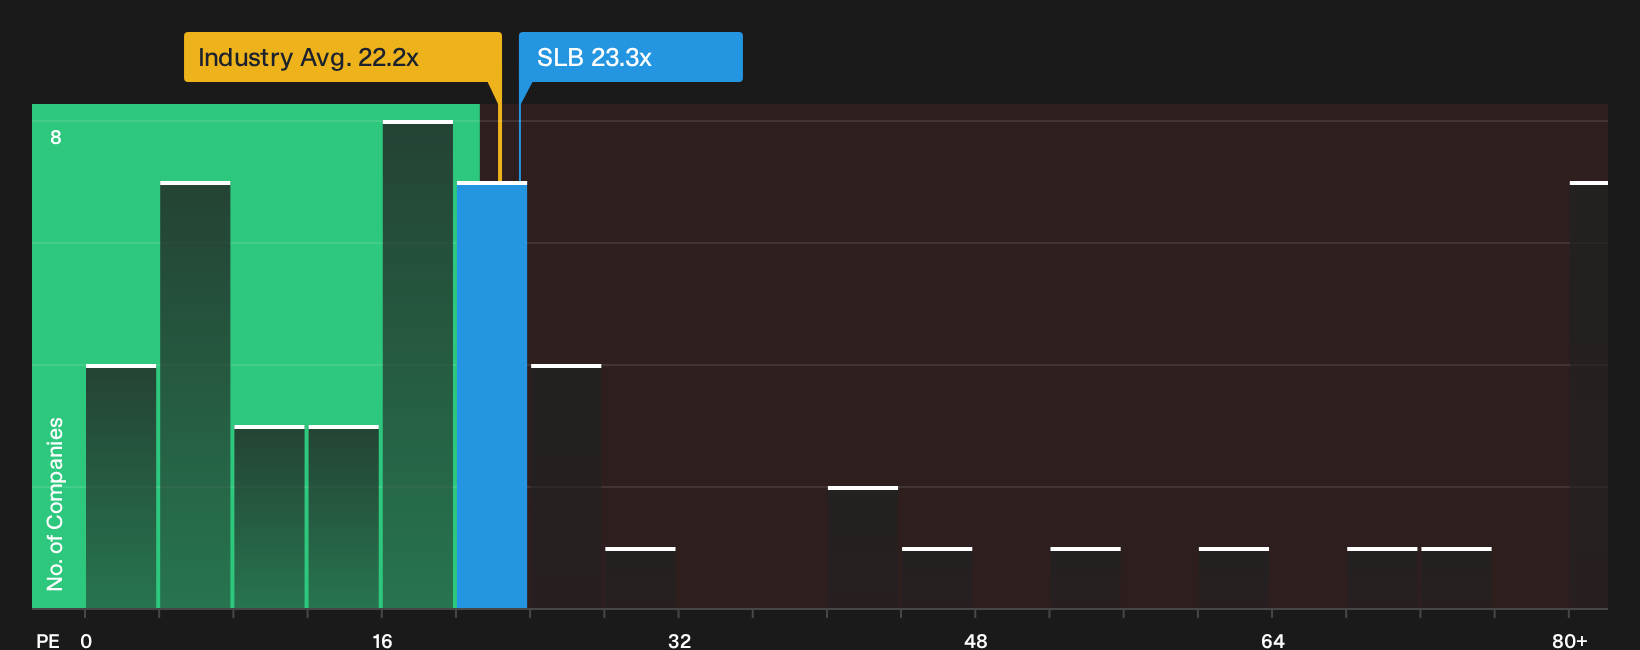
The earlier fair value of $62.41 comes from a detailed cash flow narrative. On simple earnings metrics, SLB trades on a P/E of 23.3x, which is slightly above both its fair ratio of 22.6x and the US Energy Services sector on 22.2x. That premium can either signal quality or shrink quickly if sentiment cools.
For a closer look at how this earnings multiple compares with peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SLB so far. If you want to move quickly and ground your decision in data, not headlines, start by weighing the 3 key rewards and 2 important warning signs
Looking for more SLB sized investment ideas?
Do not stop with one ticker. Broaden your watchlist now so you are not chasing the crowd after the next move has already happened.
- Target stronger balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) and focus on companies that combine resilience with fundamentals that many investors overlook.
- Hunt for mispriced opportunities through the 29 high quality undervalued stocks and filter for quality businesses trading below their assessed worth.
- Prioritize sleep at night holdings with the 31 resilient stocks with low risk scores and concentrate on companies with more resilient risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com