
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DraftKings (DKNG) Faces A Fresh Test On Super App Push As Valuation Stays In Focus
DraftKings (DKNG) is leaning into its Super App push, tying together sports betting, prediction markets and broader gaming products as it reacts to weaker sportsbook margins from recent unfavorable football outcomes.
DraftKings’ push into a broader Super App comes against a tougher tape, with the share price at US$19.66 and sliding about 21% over the past month and 22% over the last quarter, while the year to date share price return is down roughly 45% and the 1 year total shareholder return has declined about 41%. This signals fading momentum as investors reassess growth potential and earnings risk after weaker sportsbook margins and rising competition in prediction markets.
Spot similar rebound or reset stories by scanning our curated list of 29 high quality undervalued stocks. These combine solid fundamentals with more grounded expectations than high-flying betting peers.For DraftKings at US$19.66 after a sharp pullback, the choice is simple but not easy. Is this reset enough to justify stepping in now, or does patience still offer the better entry as the Super App story gets priced in?
Most Popular Narrative: 6% Undervalued
DraftKings is trading at $19.66 against a most-followed fair value estimate of $20.97. This implies only a modest discount and places more emphasis on how the Super App strategy and prediction markets story develops rather than on valuation multiples alone.
The legalization of online sports betting created one of the fastest-growing industries in consumer discretionary. DraftKings emerged as one of its biggest winners, rapidly expanding their customer base as more states embraced regulated wagering.
However, the industry's next chapter may look different. As legalization slows, competition intensifies, state tax rates rise, and new prediction market platforms such as Kalshi and Polymarket begin competing for users, DraftKings may find sustaining its growth increasingly difficult. We believe the market may be underestimating the structural headwinds that could emerge over the coming years.
See why 7 investors see DraftKings as 6% undervalued.
Result: Fair Value of $20.97 (UNDERVALUED)
Still, the bearish DraftKings narrative can break if prediction markets stall out, or if regulators slow new tax hikes and advertising restrictions.
Find out about the key risks to this DraftKings narrative.
Another View: What Multiples Say About DraftKings
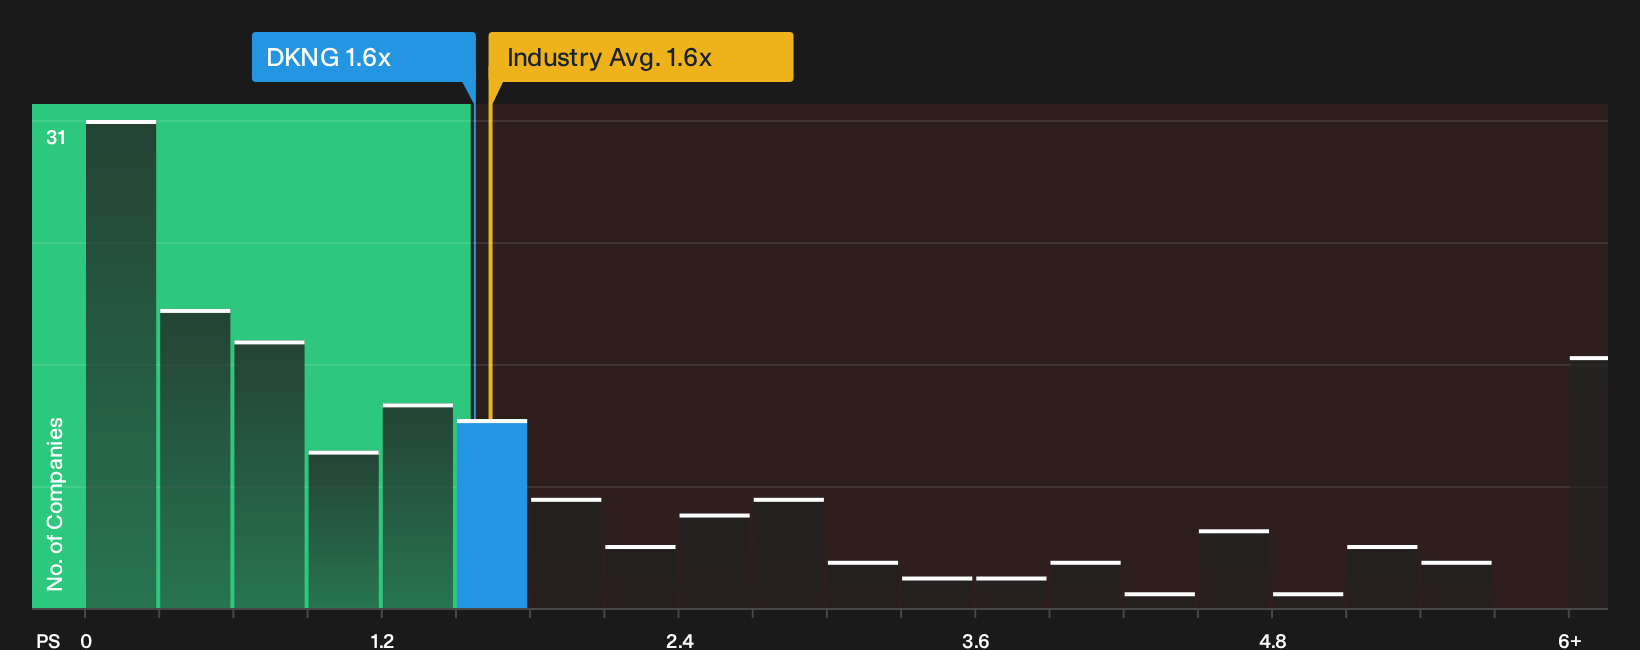
There is a very different message coming from the simple sales multiple. DraftKings trades on a P/S of 1.6x, which is the same as the US Hospitality industry average of 1.6x and below an estimated fair ratio of 2.9x that the market could move toward over time.
This mix, in plain terms, means the stock is priced like a typical peer, while a higher fair ratio suggests room for re-rating if execution improves. The peer gap and fair ratio both point to valuation risk if sentiment weakens again. The question is which signal you place more weight on: the cautious narrative or the multiple math.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around DraftKings is mixed, so this is exactly the moment to move fast, dig into the underlying drivers, and decide where you stand. To see what the current optimism is built on, review the 3 key rewards.
Looking for more investment ideas beyond DraftKings?
Do not stop your research with DraftKings. Broaden your watchlist with focused stock ideas that align with how you prefer to balance risk, income, and value.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Look for potential mispricing opportunities by reviewing the 29 high quality undervalued stocks.
- Build a cash flow focused watchlist by checking out the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com