
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Russian Write Down Change Palfinger (WBAG:PAL) Stock Narrative
- Palfinger has written down its Russian business, prepared those entities for deconsolidation, and stated that the impairment is excluded from EBIT but will reduce net income under discontinued operations.
- The group is reinforcing a ring-fenced legal structure around its Russian units, which reshapes how investors may view geographic risk concentration and the quality of future earnings for Palfinger.
- Now the focus turns to how Palfinger's investment narrative might change as the Russian deconsolidation and related write-down affect reported profitability.
Compare how Palfinger is reshaping its geographic risk with a curated list of solid balance sheet and fundamentals (202 results) that, like PAL, aims to ring-fence shocks and keep core earnings cleaner.
What Is Palfinger's Investment Narrative?
Palfinger appeals to investors who buy into a fairly simple idea: heavy kit, sticky service relationships and a long industrial heritage like Omaha Standard’s PAL Pro line, all built around load handling that customers rely on every day. The Russian write down and deconsolidation fit that story by trying to keep recurring operations, particularly in EMEA and North America, more insulated from geopolitical noise. Management still points to around €120 million in EBIT for the first nine months of 2026, which keeps the operational lens on execution, pricing discipline and order quality rather than accounting hits.
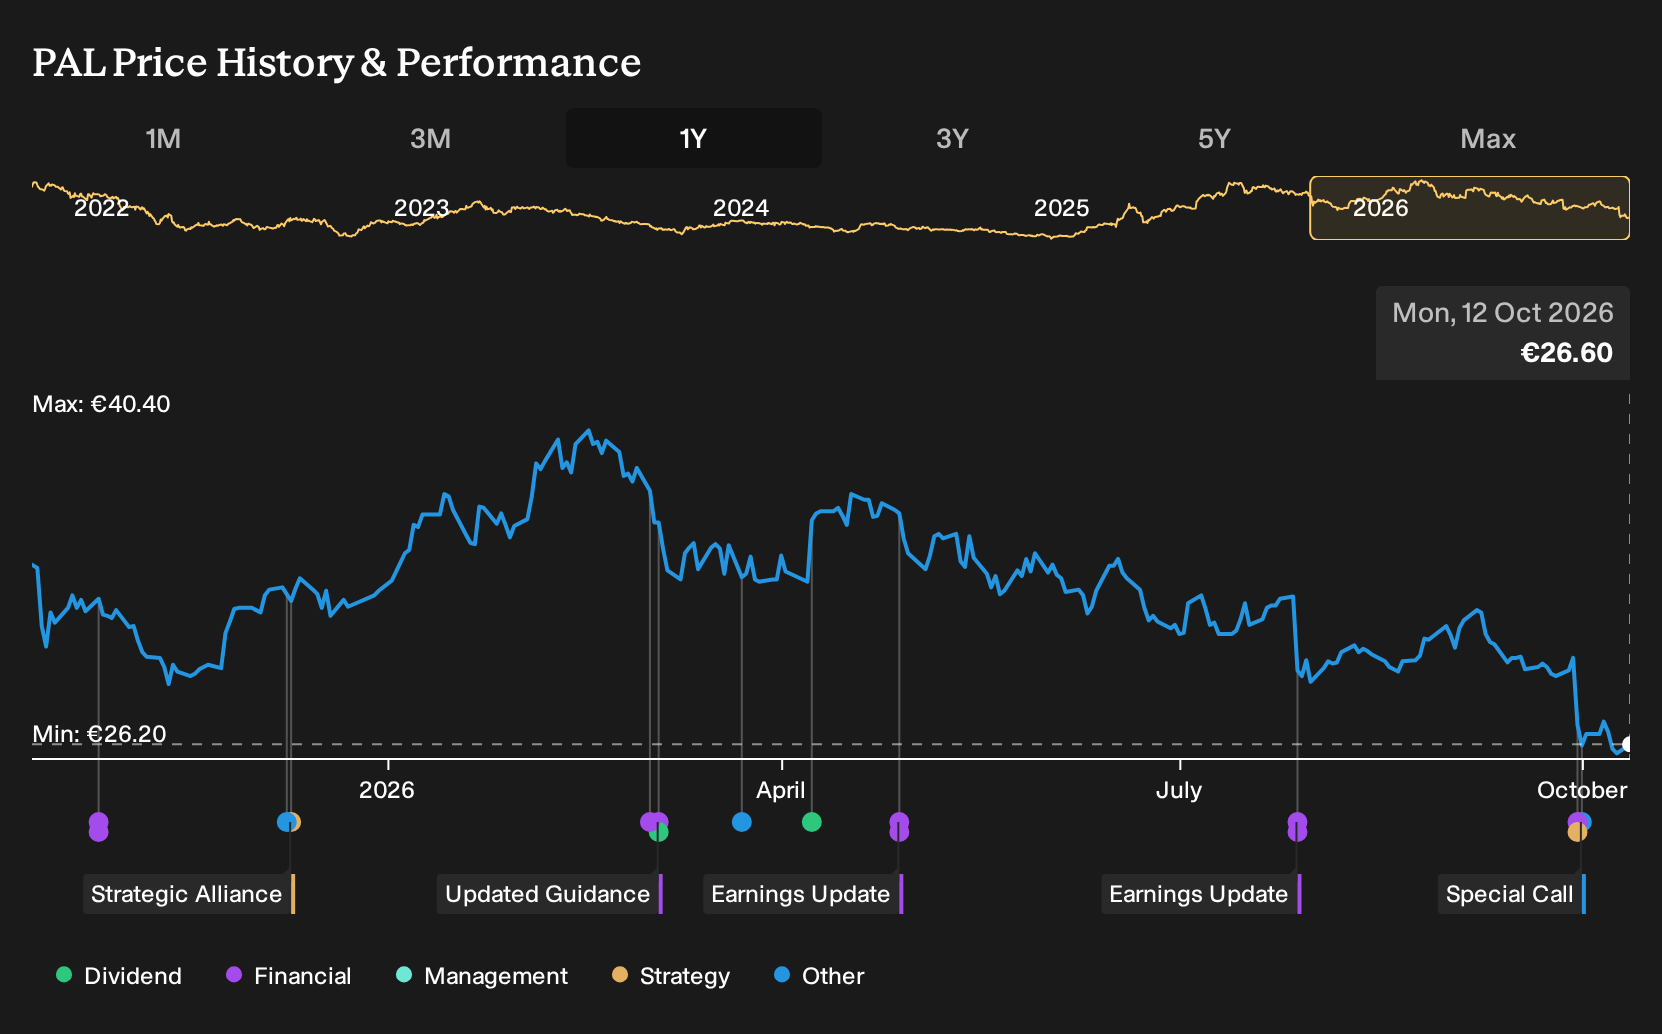
In the short term, the key swing factors sit in how well the group turns that EBIT into cash while managing a capital intensive manufacturing footprint and a high debt load. Recent share price weakness, with the stock down around 21% year to date and roughly 20% over 12 months, suggests the market is already wrestling with that trade off despite improving profit growth and a P/E of 10.6x that screens as “good value” versus peers. The Russian ring fencing trims one source of volatility, but it does not remove the most important pressure point on the Palfinger story.
Even so, there is one structural issue that could matter far more to Palfinger holders once you look closely at ...
There's only one way to know the right time to buy, sell or hold Palfinger. Head to Simply Wall St's company report for the latest analysis of Palfinger's Fair Value.
Exploring Other Perspectives
One upbeat angle on Palfinger comes from the most optimistic analysts who frame European and U.S. infrastructure spending as the real swing factor rather than Russian risk. They were pencilling in about 6.0% annual revenue growth and earnings of €200.2 million by around 2029. Those views pre date this write down, so your own take may shift as the story evolves.
Explore 3 other Palfinger fair value estimates, including one that suggests as much as 62% upside from the current price!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Palfinger research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Palfinger. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Palfinger's overall financial health at a glance.
Looking For More Investment Ideas Beyond Palfinger?
If Palfinger has sharpened your focus on risk, quality and cleaner earnings, it can help to widen the lens and line it up against other opportunities with different strengths.
- For investors who want potential mispricings with resilient fundamentals, filter for companies that look attractively priced on both earnings power and balance sheet strength using the 179 high quality undervalued stocks.
- If income reliability is a priority, scan for businesses built around robust cash generation and payouts with the 219 dividend fortresses.
- For a focus on financial resilience and shock absorption, compare Palfinger with companies screened for stronger balance sheets and sturdier fundamentals through the 227 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com