
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Principal Financial Group Climbed While Profit Fell
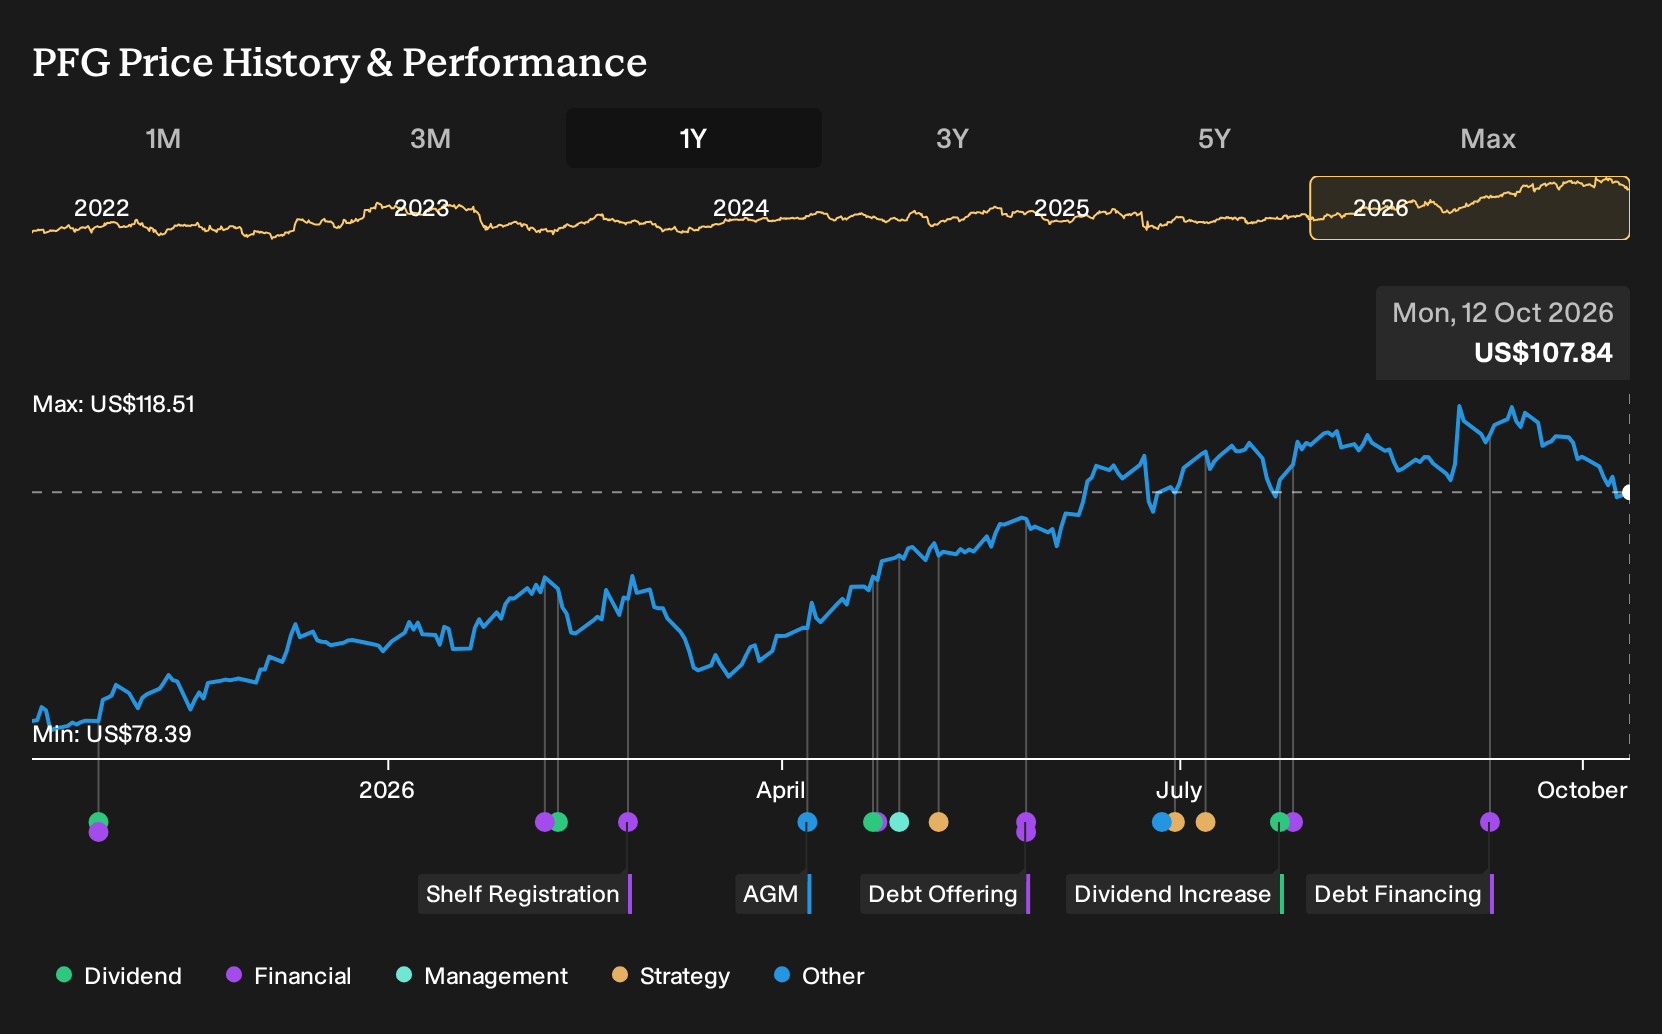
If Principal Financial Group sat on your watchlist instead of in your portfolio, the outcome may feel expensive. Investors who held Principal Financial Group over the past year are up 40.0%, including dividends. That move now sits alongside upbeat 2026 earnings headlines, dividend increases, and the Beam Benefits deal targeting small and mid-sized employers. The key question is whether the earlier bet that retirement ecosystems and global asset management would carry future fee power was already visible enough to act on.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Principal Financial Group. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Argument Principal Financial Group Investors Were Really Weighing
The shares cost US$79.42 at the start of the period, and Principal Financial Group holders were effectively choosing between two very different stories about where fee power and retirement flows might lead.
The bullish narrative put fair value at US$86.02, based on the idea that focusing on small and mid-sized employers and global asset management could support future retirement related revenue, helped by disciplined cost control.
The bearish view set fair value at US$72, stressing that persistent market volatility and cautious client behavior might pressure retirement and asset management fees, even if expense discipline supported profit margins.
What The Principal Financial Group Results Put To The Test
The Beam Benefits deal and the Q1 and Q2 2026 reports gave Principal Financial Group bulls some backing, with retirement ecosystems, small and mid-sized employer benefits, and global asset management all reporting momentum. The same period showed pressure on profitability though. Q2 2026 revenue reached US$3,905.8m while net income slipped to US$403.4m and net margin moved from 11.1% to 10.3%. Overall, the evidence cut both ways.
The investable lesson is simple. When a story leans on fee power and retirement ecosystems, track segment fee income, AUM mix, and net margin together rather than focusing on headline earnings alone.
What Principal Financial Group’s Price Already Assumes
Principal Financial Group now trades at US$108 after a 40.0% total return over the past year. The selected Narrative’s Fair Value sits below that level, reflecting a more cautious view of what the current quote already factors in.
This Narrative leans on strong EPS and margins but questions how resilient fee driven earnings, flows, and mix will be if conditions soften. A buyer today has to weigh whether cost control, underwriting and funding for planned private markets and pension activity can offset pressure from active equity outflows and any slower retirement deposits.
"Key Takeaways: Bearish analysts expect Principal Financial Group’s earnings growth to slow as continued market volatility and ongoing net outflows in certain active equity strategies pressure fee revenue and profitability. The main thing that has to go right is that Principal Financial Group continues to translate its cost discipline and underwriting results in Specialty Benefits and Benefits and Protection into sustained margin strength, even while funding technology and AI investments."
The price and this Narrative do not agree. → Uncover what this Narrative says Principal Financial Group is actually worth
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 47% below our estimate - targets online bettors moving from in-person venues through owned payment technology.
- Company 2 - 33% below our estimate - converts subsea opportunities into integrated installation work and repeat equipment servicing contracts.
- Company 3 - 43% below our estimate - advises on safety and regulatory issues as complex products demand more technical investigations.
That is three of the list. See the full list of 25 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com