
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OSI Systems (OSIS) After A $23 Million Order Is The Undervalued Narrative Still Intact
OSI Systems (OSIS) drew fresh attention after its Security division reported approximately US$23 million in new orders from a North American customer for civil works, service, and support related to cargo inspection systems.
For context, OSI Systems shares trade at US$195.32, with the stock down 23.58% on a year-to-date share price basis while the 1-year total shareholder return has declined 20.96%. However, longer-term holders have seen total shareholder returns of 65.30% over three years and 107.43% over five, suggesting recent weakness contrasts with a stronger multi-year record.
Compare how OSI Systems stacks up against hand-picked security and industrial technology peers by scanning the list of solid balance sheet and fundamentals (25 results) before the next contract win hits the headlines.
OSI Systems now trades well below its recent highs despite fresh contract momentum. The key question is whether recent gains already reflect the opportunity or if the valuation still leaves meaningful upside on the table.
Most Popular Narrative: 30% Undervalued
Against the last close of $195.32, the most followed narrative pegs OSI Systems at a fair value of $278.29 using a 9.8% discount rate. That gap rests on the idea that today’s share price reflects more caution than the backlog, earnings profile, and contract mix might imply.
The current valuation implies the market is discounting OSI Systems, despite record FY26 EPS of US$10.35, record operating cash flow of US$276m and active share repurchases. Taken together, these point to a company priced more cautiously than its recent results and backlog might suggest.
See why 5 investors see OSI Systems as 30% undervalued.
Result: Fair Value of $278.29 (UNDERVALUED)
Still, the OSI Systems story can be knocked off course if Security revenues remain under pressure after the recent 7% decline and if guidance continues to fall short of expectations.
Find out about the key risks to this OSI Systems narrative.
Another View: OSI Systems Through The Cash Flow Lens
The earlier narrative leans on earnings power and analyst targets to argue OSI Systems looks undervalued around $195.32. Our DCF model paints a very different picture. On that framework, the estimated future cash flow value sits at $79.25, which points to a stock price that screens as expensive rather than cheap.
That kind of gap between an earnings based fair value of $278.29 and a DCF output of $79.25 raises a practical question. Are you more comfortable trusting reported profitability and analyst forecasts, or a cash flow model that demands a bigger margin of safety for OSI Systems?
Look into how the SWS DCF model arrives at its fair value.
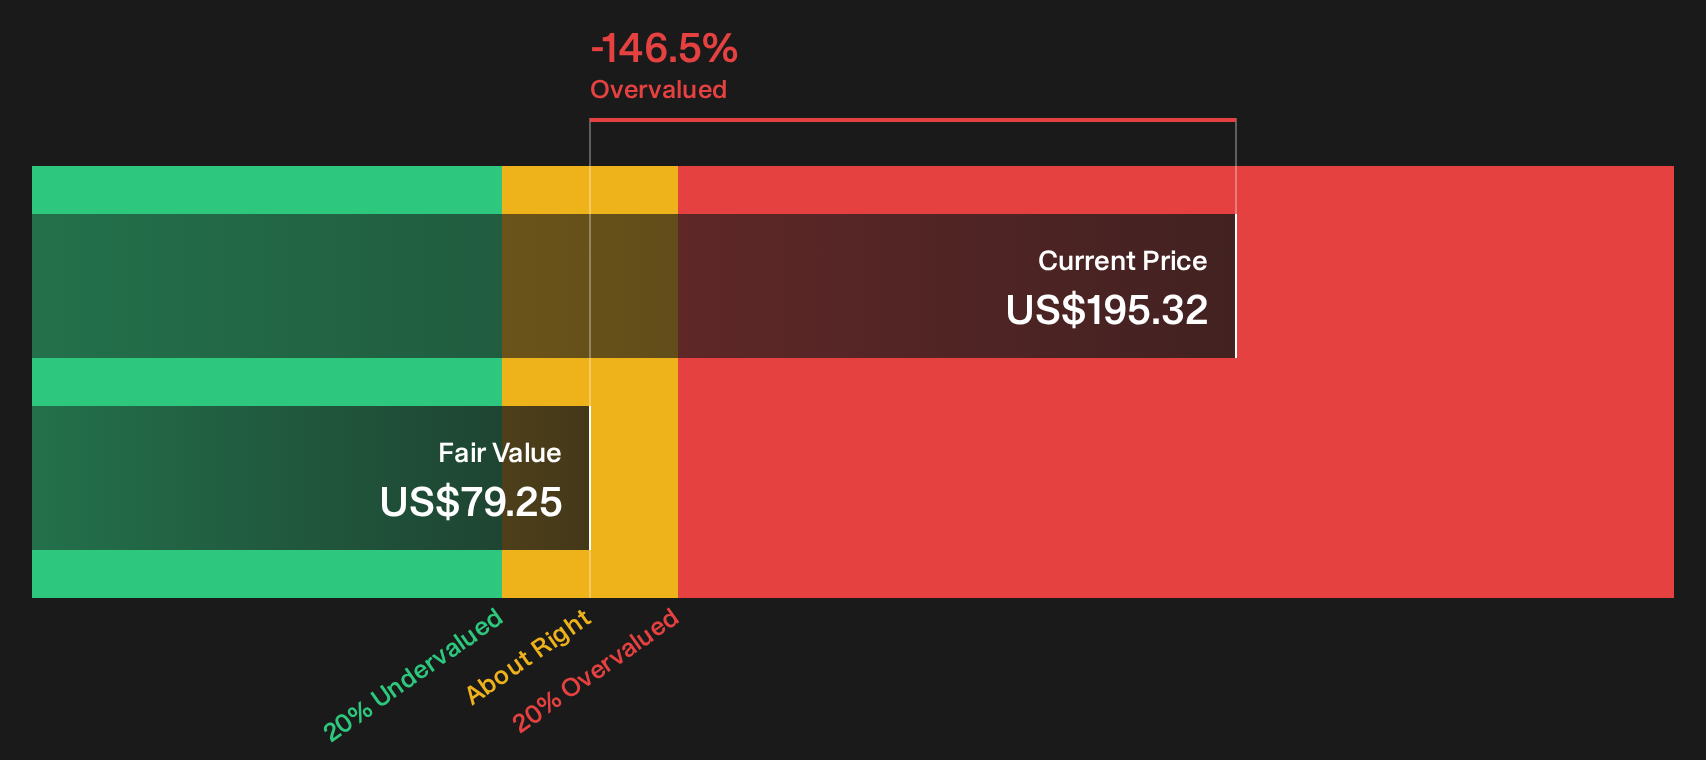
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OSI Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these rarely stay ignored for long. Treat this as your cue to review the numbers, stress test your own thesis, and weigh the 5 key rewards and 1 important warning sign.
Looking for more OSI Systems style investment ideas?
If OSI Systems has you rethinking your watchlist, do not stop here. Use the Simply Wall St Screener to uncover fresh opportunities before others move first.
- Target quality at a discount by scanning companies that combine strong fundamentals with appealing valuations through the 29 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses flagged for sturdier finances with the 31 resilient stocks with low risk scores.
- Hunt for future leaders before they hit the spotlight by running the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com