
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Newmont (NEM) Stock Looks Above Fair Value On Its 210% Run
Newmont has delivered a powerful multi year run, and the current share price now raises a straightforward question for you as an investor. Are today’s levels adequately supported by the cash flows that the gold producer can generate over time, or has sentiment moved ahead of the underlying economics of the business?
- Over the past 3 years the stock has returned about 209.9%, which puts a lot of past optimism about Newmont’s cash generation and capital discipline under the microscope.
- Newmont’s work on the Ahafo North project in Ghana may support expectations for future production and cash flow, while also shaping when heavy investment gives way to stronger free cash generation.
- Prefer to judge Newmont on earnings? See why Newmont's 14.2x P/E tells a different valuation story.
The stock’s next move may depend on whether Newmont’s current price can be justified by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
If you want a second reference point alongside Newmont and its cash flow story, start a shortlist with a focused screen of 36 elite gold producer stocks.
Does Newmont Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Newmont can return to shareholders over time. On the latest figures the miner generated roughly $8.7b of free cash flow over the last twelve months, which is a hefty base for any valuation model to work from.
Analysts feeding this DCF are assuming that Newmont’s free cash flow eases back from that recent level toward the end of the decade rather than climbing steadily, so the framework leans on a recovering and then moderating cash profile rather than an aggressive growth story. Because those projections still lead to an estimated intrinsic value that sits meaningfully below the current share price of $117.15, the model suggests investors are paying up for qualities that do not fully show in the cash flow math. Newmont’s progress on the Ahafo North project in Ghana gives a clear production and cash flow angle, yet this kind of expansion focus helps explain why the market is comfortable valuing the equity ahead of what the DCF alone supports. Find out what Newmont could be worth using our Discounted Cash Flow (DCF) estimate.
The Newmont Narrative: What Would Justify Today's Price?
Narratives for Newmont follow on from the DCF question and describe what path for growth, margins and earnings would need to occur for the share price to look meaningfully higher or lower than today. Each Narrative focuses less on a single valuation output and more on the specific assumptions that support its fair value view, so you can compare those expectations with Newmont's actual results as new numbers appear on Simply Wall St's Community page.
The community reading Newmont splits into two clear camps, with one group seeing upside and the other flagging valuation pressure.
Bull case: 15% undervalued
"The realization of synergies and increased production scale following the Newcrest Mining acquisition, together with ongoing asset optimization and the ramp-up of expansion projects such as Ahafo North and Tanami..."
Discover why this Narrative puts Newmont at 15% undervalued.
Bear case: 25% overvalued
"Compounded by ongoing depletion of economically viable reserves, Newmont will be forced to develop more lower-grade, higher-cost deposits, leading to a structural rise in all-in sustaining costs..."
Explore why this Narrative puts Newmont at 25% overvalued.
One more Newmont signal that could change how you read the story
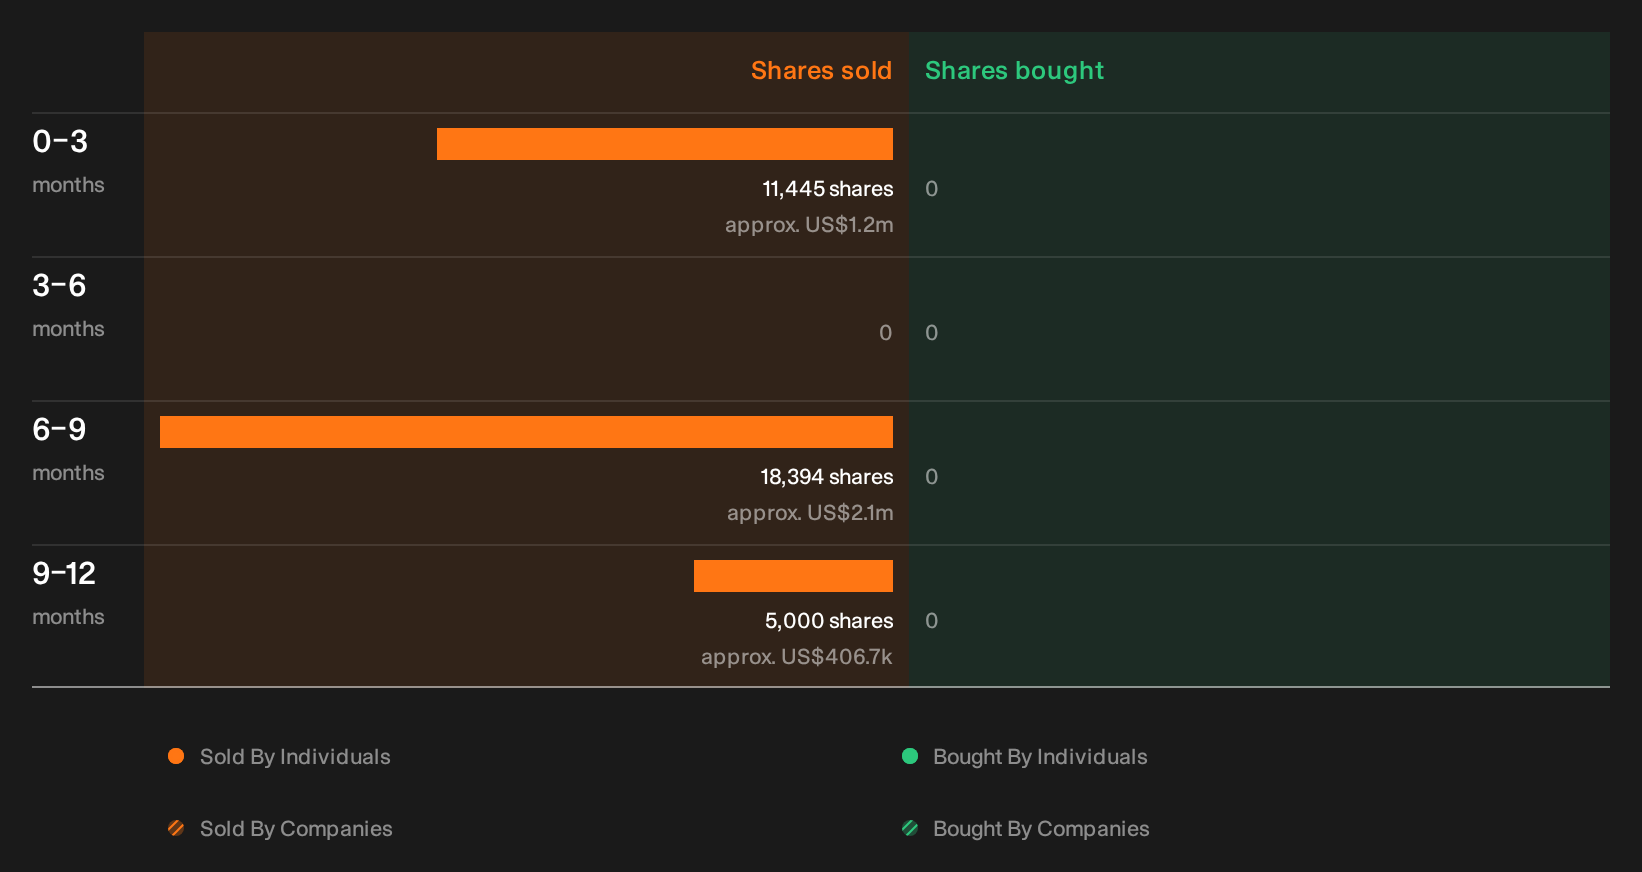
There is one more piece of context that can sharpen your view on Newmont, since recent trading by company insiders has been flagged by our checks and the who, how much and why still needs your own scrutiny. See the recent insider selling flagged for Newmont.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com