
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Discover 3 Asian Stocks Trading At A Possible Discount To Enhance Your Portfolio
Amidst the backdrop of geopolitical tensions and fluctuating oil prices, Asian markets have experienced a mix of volatility and opportunity. In this environment, identifying stocks that may be trading at a discount can be an effective strategy for investors looking to enhance their portfolios.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Riken Technos (TSE:4220) | ¥2444.00 | ¥4775.36 | 48.8% |
| Nissui (TSE:1332) | ¥1085.00 | ¥2151.38 | 49.6% |
| Monde Nissin (PSE:MONDE) | ₱6.35 | ₱12.68 | 49.9% |
| Marco Polo Marine (SGX:5LY) | SGD0.12 | SGD0.23 | 48.7% |
| Kumagai GumiLtd (TSE:1861) | ¥1196.00 | ¥2375.95 | 49.7% |
| Kona ILtd (KOSDAQ:A052400) | ₩34650.00 | ₩68975.22 | 49.8% |
| Innocean Worldwide (KOSE:A214320) | ₩18090.00 | ₩35794.48 | 49.5% |
| ENN Energy Holdings (SEHK:2688) | HK$49.52 | HK$97.00 | 48.9% |
| Astellas Pharma (TSE:4503) | ¥2247.50 | ¥4494.42 | 50% |
| Apex Mining (PSE:APX) | ₱16.68 | ₱33.13 | 49.6% |
Let's explore several standout options from the results in the screener.
HUAYU Automotive Systems (SHSE:600741)
Overview: HUAYU Automotive Systems Company Limited researches, develops, manufactures, and sells automotive parts globally, with a market cap of CN¥49.21 billion.
Operations: HUAYU Automotive Systems generates revenue through the research, development, manufacturing, and sale of automotive parts on a global scale.
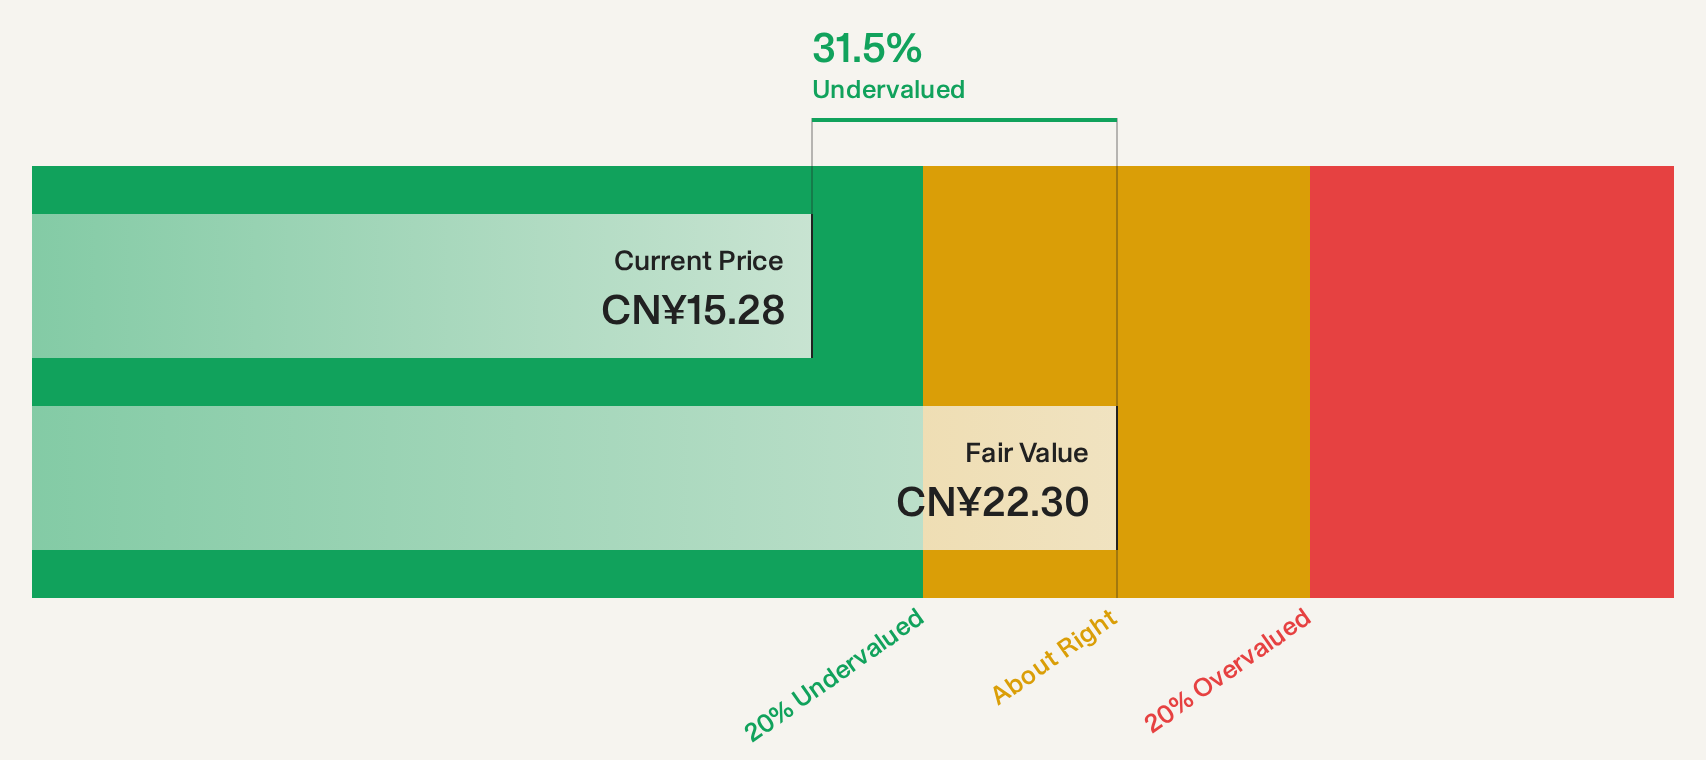
Estimated Discount To Fair Value: 29.6%
HUAYU Automotive Systems is trading at CN¥15.61, significantly below its estimated future cash flow value of CN¥22.18, suggesting undervaluation. Despite a decline in recent earnings and revenue compared to the previous year, the stock is valued 29.6% below fair value estimates by analysts who predict a 33.9% price increase potential. However, expected annual profit and revenue growth rates are slower than market averages, with a forecasted low return on equity of 9.4%.
- The analysis detailed in our HUAYU Automotive Systems growth report hints at robust future financial performance.
- Click here and access our complete balance sheet health report to understand the dynamics of HUAYU Automotive Systems.
LiJiang YuLong Tourism (SZSE:002033)
Overview: LiJiang YuLong Tourism Co., LTD. is involved in the development and operation of tourism businesses in China, with a market capitalization of CN¥4.54 billion.
Operations: The company's revenue is primarily generated from its tourism operations in China, totaling CN¥1.25 billion.
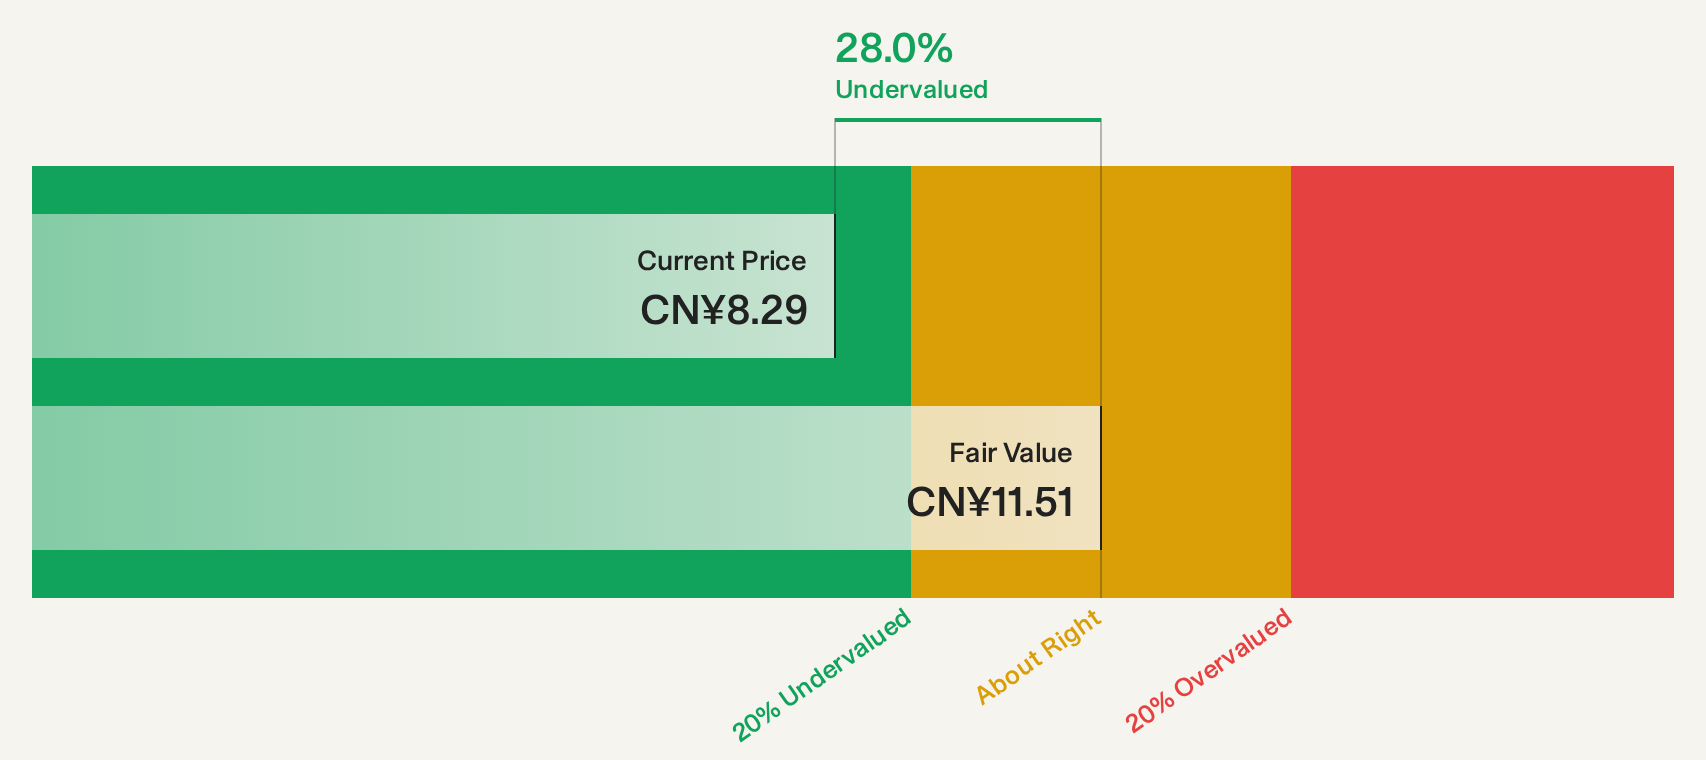
Estimated Discount To Fair Value: 28.2%
LiJiang YuLong Tourism trades at CN¥8.26, below its estimated future cash flow value of CN¥11.5, indicating undervaluation by over 20%. Despite slower forecasted revenue growth (6.4% annually) compared to the Chinese market, recent earnings increased significantly to CN¥132.74 million for the half year ended June 2026 from CN¥94.5 million previously. The dividend yield of 4.24% is not well covered by free cash flows, and return on equity is projected to be low at 10.1%.
- Our earnings growth report unveils the potential for significant increases in LiJiang YuLong Tourism's future results.
- Unlock comprehensive insights into our analysis of LiJiang YuLong Tourism stock in this financial health report.
Rakus (TSE:3923)
Overview: Rakus Co., Ltd. and its subsidiaries offer cloud services in Japan, with a market cap of ¥401.56 billion.
Operations: Revenue segments (in millions of ¥): Cloud services: ¥12,345; IT outsourcing: ¥3,678; Consulting: ¥2,456.
Estimated Discount To Fair Value: 45.3%
Rakus is trading at ¥1,134, significantly below its future cash flow value of ¥2,073.83. Despite a volatile share price and slower revenue growth than the Japanese market, earnings rose sharply to ¥14.63 billion for Q1 2026 from ¥3.54 billion a year ago. The company is expanding its business scope with amendments to its Articles of Incorporation and strategic alliances like the one with ROBOT PAYMENT Inc., potentially enhancing future cash flows.
- Our comprehensive growth report raises the possibility that Rakus is poised for substantial financial growth.
- Click here to discover the nuances of Rakus with our detailed financial health report.

Make It Happen
- Unlock more gems! Our Undervalued Asian Stocks Based On Cash Flows screener has unearthed 172 more companies for you to explore.Click here to unveil our expertly curated list of 175 Undervalued Asian Stocks Based On Cash Flows.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com