
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Corebridge Financial (CRBG) Could Change Following Annuity Feature Launch
- Corebridge Financial has introduced Progressive Trigger, a new index annuity interest-crediting approach within Power Select Builder that uses a five-year evaluation period and a Memory feature to carry forward eligible interest percentages after years of negative index performance.
- The Memory mechanism gives Corebridge Financial another way to address customer concerns about missing out on future upside after down markets, while still keeping principal protection at the center of the annuity design.
- We will look at how Corebridge Financial's long term retirement narrative is affected by Progressive Trigger's multi year Memory feature.
Compare the annuity focus of Corebridge Financial with other insurers that are building for longevity and capital protection by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
Corebridge Financial Investment Narrative Recap
To own Corebridge Financial, you need to believe the retirement and annuity engine can translate demographic tailwinds into steadier earnings despite choppy investment income. The short term swing factor remains how variable investment income and alternative assets track against management’s expectations, since guidance already flags pressure on 2026 results from weaker private equity marks.
Progressive Trigger fits that backdrop by widening Corebridge Financial’s shelf of principal protection products at a time when investors have fresh memories of volatility. It does not change the main execution hurdle, which is delivering merger synergies and shifting toward more fee based, capital light earnings while managing debt that is not well covered by operating cash flow.
The Progressive Trigger launch inside Power Select Builder is the announcement that links most directly to current catalysts. It aims to keep customers engaged through down years using a five year evaluation period and a Memory feature that carries forward eligible interest percentages, which could help retention if markets have uneven annual returns.
For you as a shareholder, the operational question is whether products like Progressive Trigger strengthen Corebridge Financial’s positioning in individual retirement enough to offset softer institutional volumes or delayed fee income targets. Execution risk around investment returns, earnings misses and capital access remains, so the value of this product will be judged on sales traction, mix shift and how it supports the move toward more stable, less spread dependent earnings.
Corebridge Financial Forecasts Behind Progressive Trigger
Corebridge Financial's long term pitch rests on analysts' assumptions that retirement focused products like Progressive Trigger can help support steadier earnings while the broader business targets higher profitability.
Analysts currently assume revenue growth of 6.5% per year over the next three years, with profit margins lifting from 4.6% today to 11.3% by 2029 as integration work and mix shift play through.
On those numbers, earnings today of US$889.0 million are projected to reach US$2.7b by 2029, which would mean an earnings increase of roughly US$1.8b over that period.
To align that profit outlook with current valuation work, the analyst framework also assumes Corebridge Financial trades on a P/E of 6.9x those 2029 earnings, compared with 17.6x today and 17.0x for the broader US diversified financial peer group.
Corebridge Financial's narrative projects US$23.6b revenue and US$2.7b earnings by 2029. This requires 6.5% yearly revenue growth and an earnings increase of roughly US$1.8b from US$889.0 million.
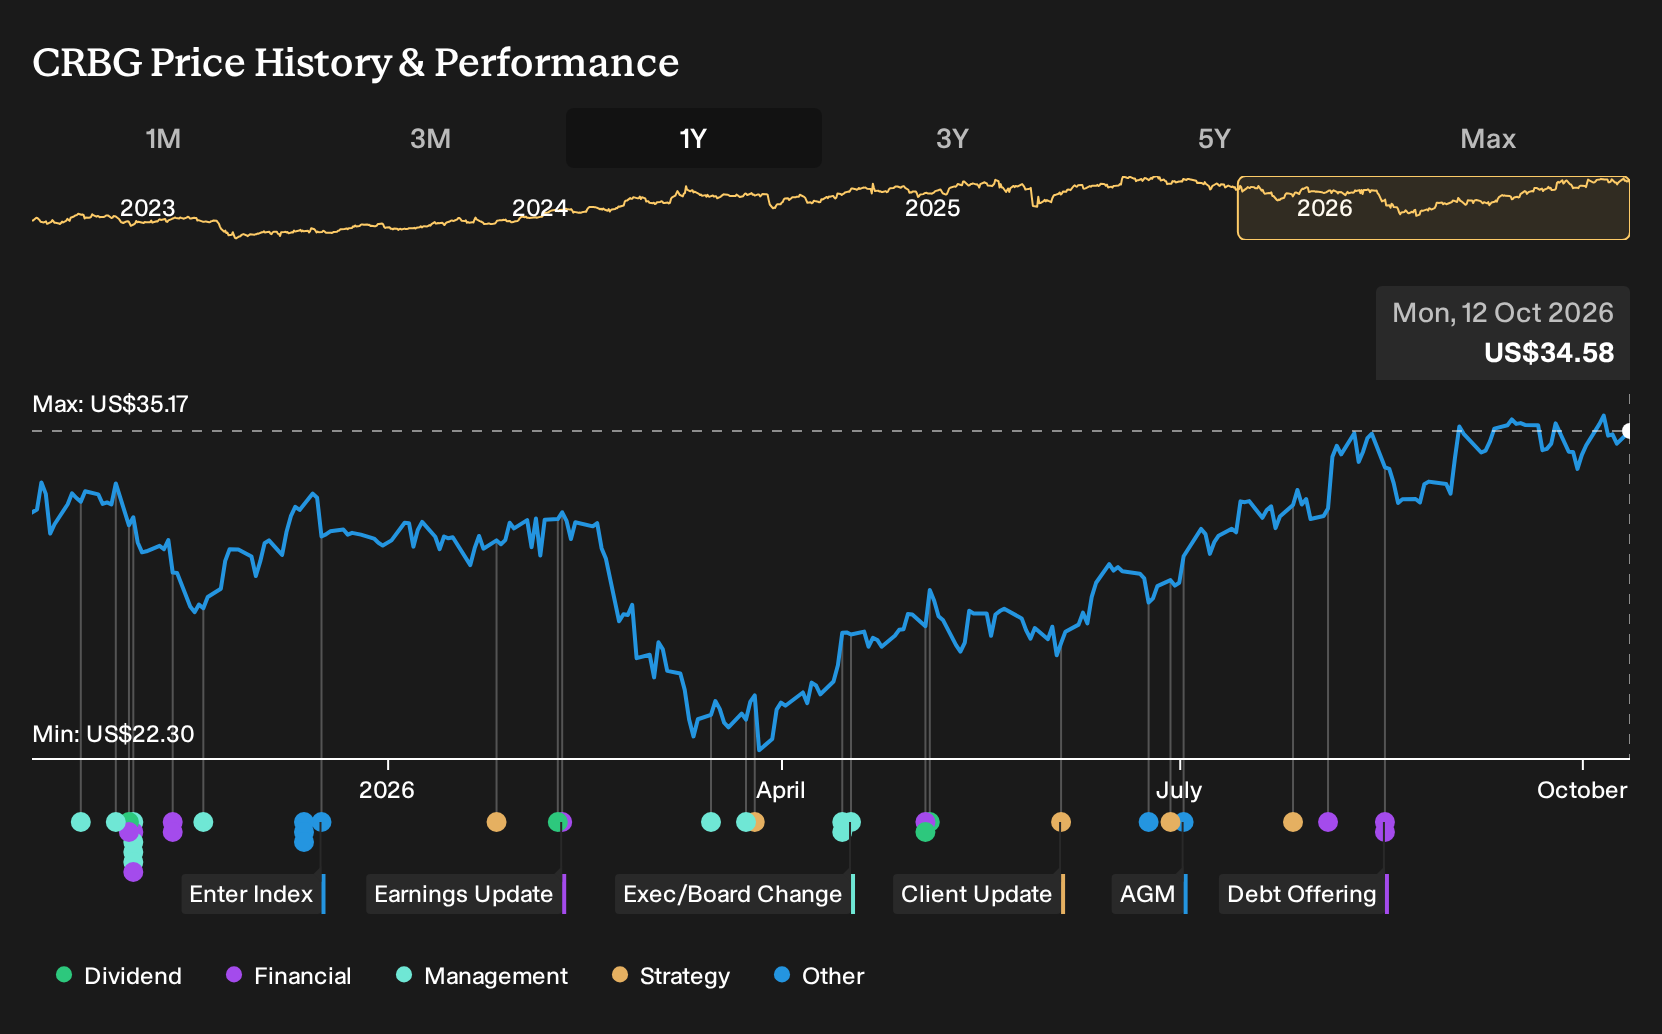
Uncover how Corebridge Financial's fair value indicates a 15% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$39.67 and US$48.80 per share, so you are seeing a relatively tight but still meaningful spread in expectations for Corebridge Financial. Those views do not factor in Progressive Trigger or current earnings risks. Use them as starting points and explore several contrasting opinions.
Explore another Corebridge Financial fair value estimate, including one that suggests it could be worth just $39.67.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Corebridge Financial research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Corebridge Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corebridge Financial's overall financial health at a glance.
Looking for more Corebridge Financial style investment ideas?
If Progressive Trigger has sharpened your thinking on capital protection and long term retirement themes, you can broaden that lens beyond Corebridge Financial by running targeted screens on the Simply Wall St platform. The right filter can surface companies with the balance sheets, cash flows, or income profiles that fit the portfolio role you care about most.
- If capital strength is top of mind, start with a list of solid balance sheet and fundamentals (25 results) that keeps financial resilience and fundamentals front and center.
- For investors hunting for mispriced quality, use the 29 high quality undervalued stocks to find candidates where fundamentals and valuation may not fully line up.
- If income is your priority, build a watchlist of higher yielding payers by scanning the 8 dividend fortresses that focuses on stronger payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com