
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TTM Technologies Stock In Focus After $400 Million AI Capacity Expansion
- TTM Technologies has committed US$400 million to expand capacity at four Chinese facilities and its Penang, Malaysia plant to support advanced N+M asymmetrical interconnect products for AI data center, hyperscaler, and networking demand, using a rapid ramp brownfield approach.
- This capacity build is part of a broader US$1.2 billion multiyear investment plan and indicates that management is aligning real-world manufacturing footprint and equipment spending directly with customer indications of increasing AI infrastructure needs.
- We will now examine how this rapid ramp, AI-focused capacity expansion could reshape TTM Technologies' existing investment narrative.
TTM Technologies Investment Narrative Recap
To own TTM Technologies, you need to believe the company can turn heavy spending on advanced PCBs and engineered solutions into durable returns from AI infrastructure and defense customers. The US$400 million AI focused expansion fits that thesis by leaning into customer signaled demand. The key near term swing factor remains execution on these ramps, especially Penang and the upgraded China sites, without letting start up friction erode margins.
The biggest current risk is stacking new capacity and higher cost footprints on top of customer concentration and geopolitical exposure in China. If utilization or pricing disappoints, the same AI driven buildout that excites investors could weigh on free cash flow. The latest expansion does not remove those issues. It concentrates them in a more AI centric mix that needs clean, on time qualification and stable orders.
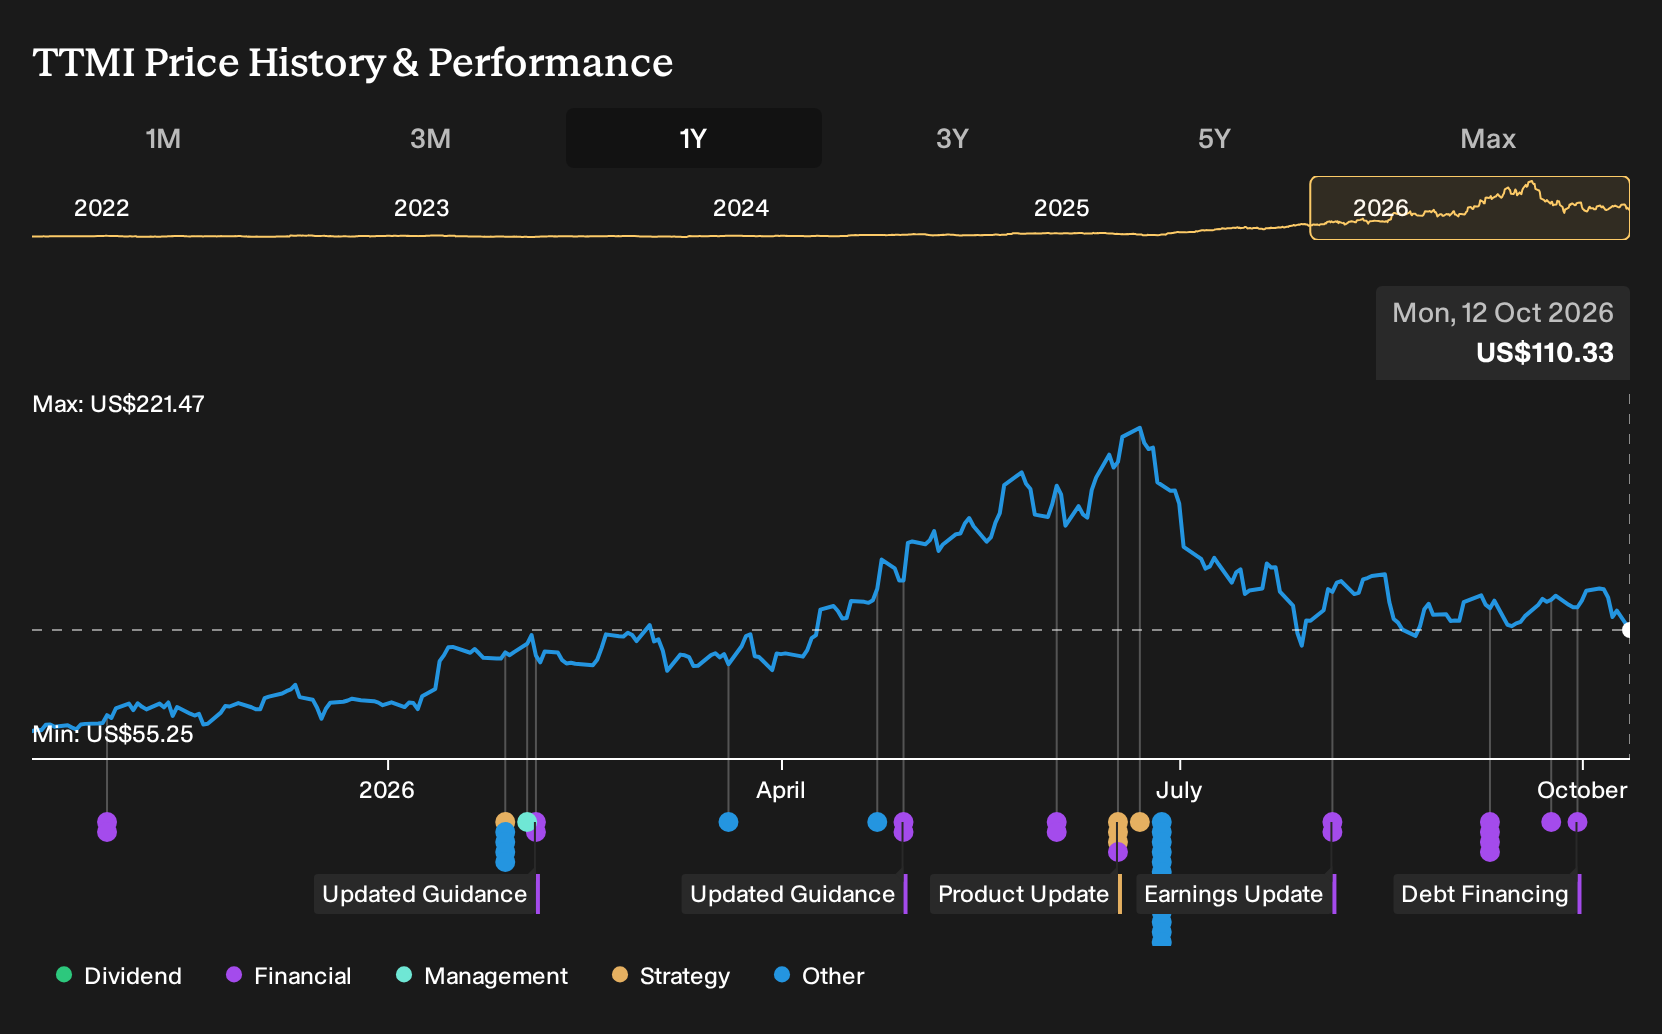
The September 30 credit agreement that added US$300 million of term loan A and US$800 million of term loan B sits in the background of this new capacity push. It helped fund the roughly US$1.1 billion Epiq Solutions acquisition alongside 6.750% senior notes due 2034. For investors, that means a more leveraged balance sheet supporting both M&A and capex at the same time.
That extra debt raises the bar on execution. TTM Technologies now has to integrate Epiq, absorb higher interest costs, and bring AI ready PCB capacity online efficiently across China and Penang. If AI and defense related programs ramp as customers indicate, the enlarged footprint and engineered systems portfolio could support the growth story analysts model. If qualification delays, pricing pressure, or geopolitical issues hit, leverage and capital intensity could turn into the main constraint on the equity story.
TTM Technologies' current analyst narrative points to US$7.1b in revenue and US$1.1b in earnings by 2029, based on an assumed 27.9% yearly revenue growth rate and an earnings increase of about US$863.2m from US$236.8m today.
Uncover why TTM Technologies' fair value indicates an 84% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on TTM Technologies focuses on AI demand resilience. The most optimistic analysts were already modeling US$9.3b of revenue and US$1.2b of earnings by 2029 before this US$400m expansion news. You can read that as a far more upbeat story that could be revised again as fresh information lands.
Explore 4 other TTM Technologies fair value estimates, including one that suggests as much as 114% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own independent research.
- A great starting point for your TTM Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TTM Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TTM Technologies' overall financial health at a glance.
Looking for more TTM Technologies sized investment ideas?
If the TTM Technologies story has you thinking about where AI infrastructure, cash flow resilience, and balance sheet strength intersect, it can help to scan a broader set of companies built around similar traits.
- For investors who want potential mispricing combined with quality fundamentals, consider starting with a curated group of 29 high quality undervalued stocks that already clear strong basic checks.
- If dependable balance sheets matter most to you, focus on businesses in the list of solid balance sheet and fundamentals (25 results) that aim to keep financial risk in check while still funding growth.
- Those hunting for businesses that fly under the radar but still show solid fundamentals may find fresh ideas in a carefully filtered pool of 20 high quality undiscovered gems that rarely make headline lists.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com