
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How First Quarter Earnings Will Impact Sakata Seed Stock Investors
- Sakata Seed reported first quarter 2026 results for the period ended August 31, with sales of ¥24,670 million and net income of ¥2,239 million, compared with sales of ¥23,005 million and net income of ¥3,637 million a year earlier.
- The latest figures show higher top line but lower net income and basic earnings per share of ¥53.03 versus ¥84.09, which highlights pressure on profitability even as demand supports sales.
- The focus now turns to how Sakata Seed's higher revenue but weaker earnings profile could influence the broader investment narrative for the stock.
What Is Sakata Seed's Investment Narrative?
Sakata Seed appeals to shareholders who care about a real, operating franchise built around genetics, breeding and long product cycles rather than short term trading stories. The first quarter update fits that picture. Sales of ¥24,670 million point to demand holding up, yet net income and earnings per share softened, which keeps the spotlight on cost control, mix and pricing discipline. For a capital intensive breeder and producer, the question is whether management can keep reinvesting in R&D and facilities without letting profitability slide too far.
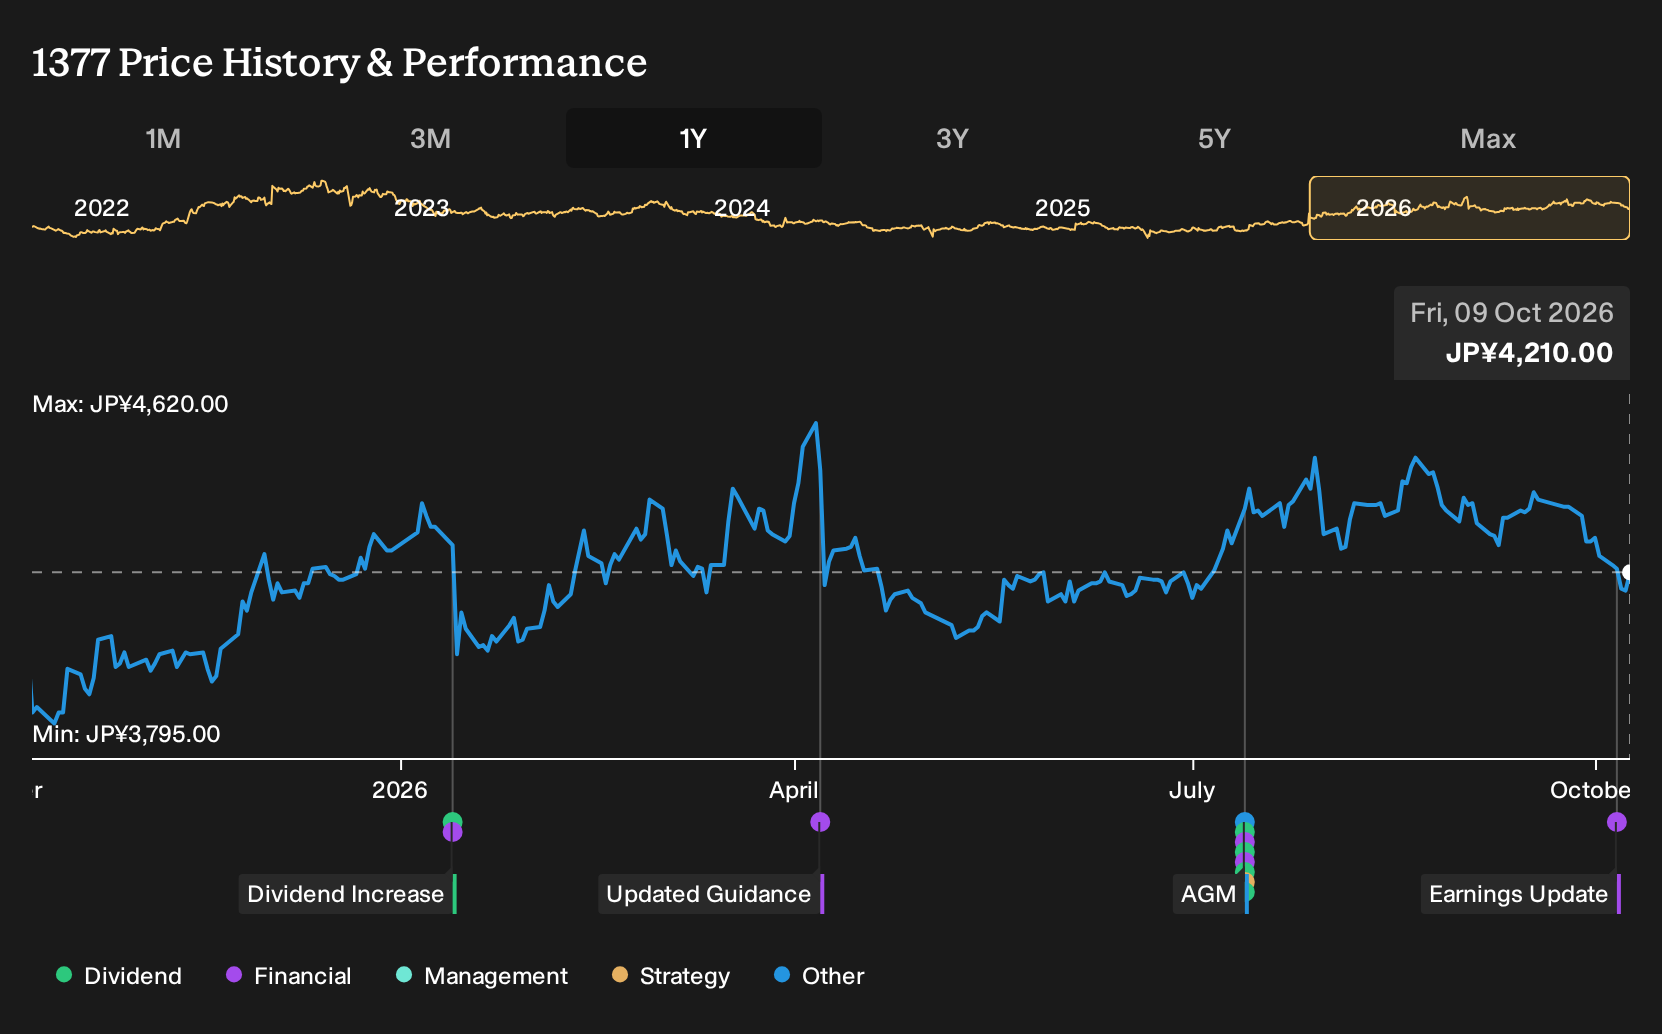
In the short term, the weaker earnings print comes on top of pressure on profit margins compared with last year and a share price that has eased over the past 30 and 90 days. Forecasts still point to earnings growth of 5.7% a year and revenue growth of 4.3% a year, with the stock trading below some estimates of fair value. The latest quarter therefore looks more like a profitability wobble than a broken story. The bigger watchpoints now are execution on pricing, maintaining high quality earnings and how management balances a 2.14% dividend yield with free cash flow that does not fully cover it.
Yet the picture becomes more complicated once you factor in ...
There's only one way to know the right time to buy, sell or hold Sakata Seed. Head to Simply Wall St's company report for the latest analysis of Sakata Seed's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sakata Seed research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sakata Seed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sakata Seed's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sakata Seed?
If this Sakata Seed update has sharpened your questions about valuation, balance sheet strength and income reliability, it can help to line it up against other businesses with different profiles. The Simply Wall St Screener lets you do that quickly by focusing on the traits you care about most.
- For investors who want potential upside with some earnings and balance sheet support, scan a curated set of 74 high quality undiscovered gems that combine quality fundamentals with lower market attention.
- If capital preservation sits high on your priority list, filter for companies with steadier finances and business risk using our focused 24 resilient stocks with low risk scores to see which stocks offer more resilient profiles.
- Income focused readers who care about getting paid while they wait can review a hand picked 28 dividend fortresses that aim to pair higher yields with sturdier underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com