
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Boozt Bulls Got Right
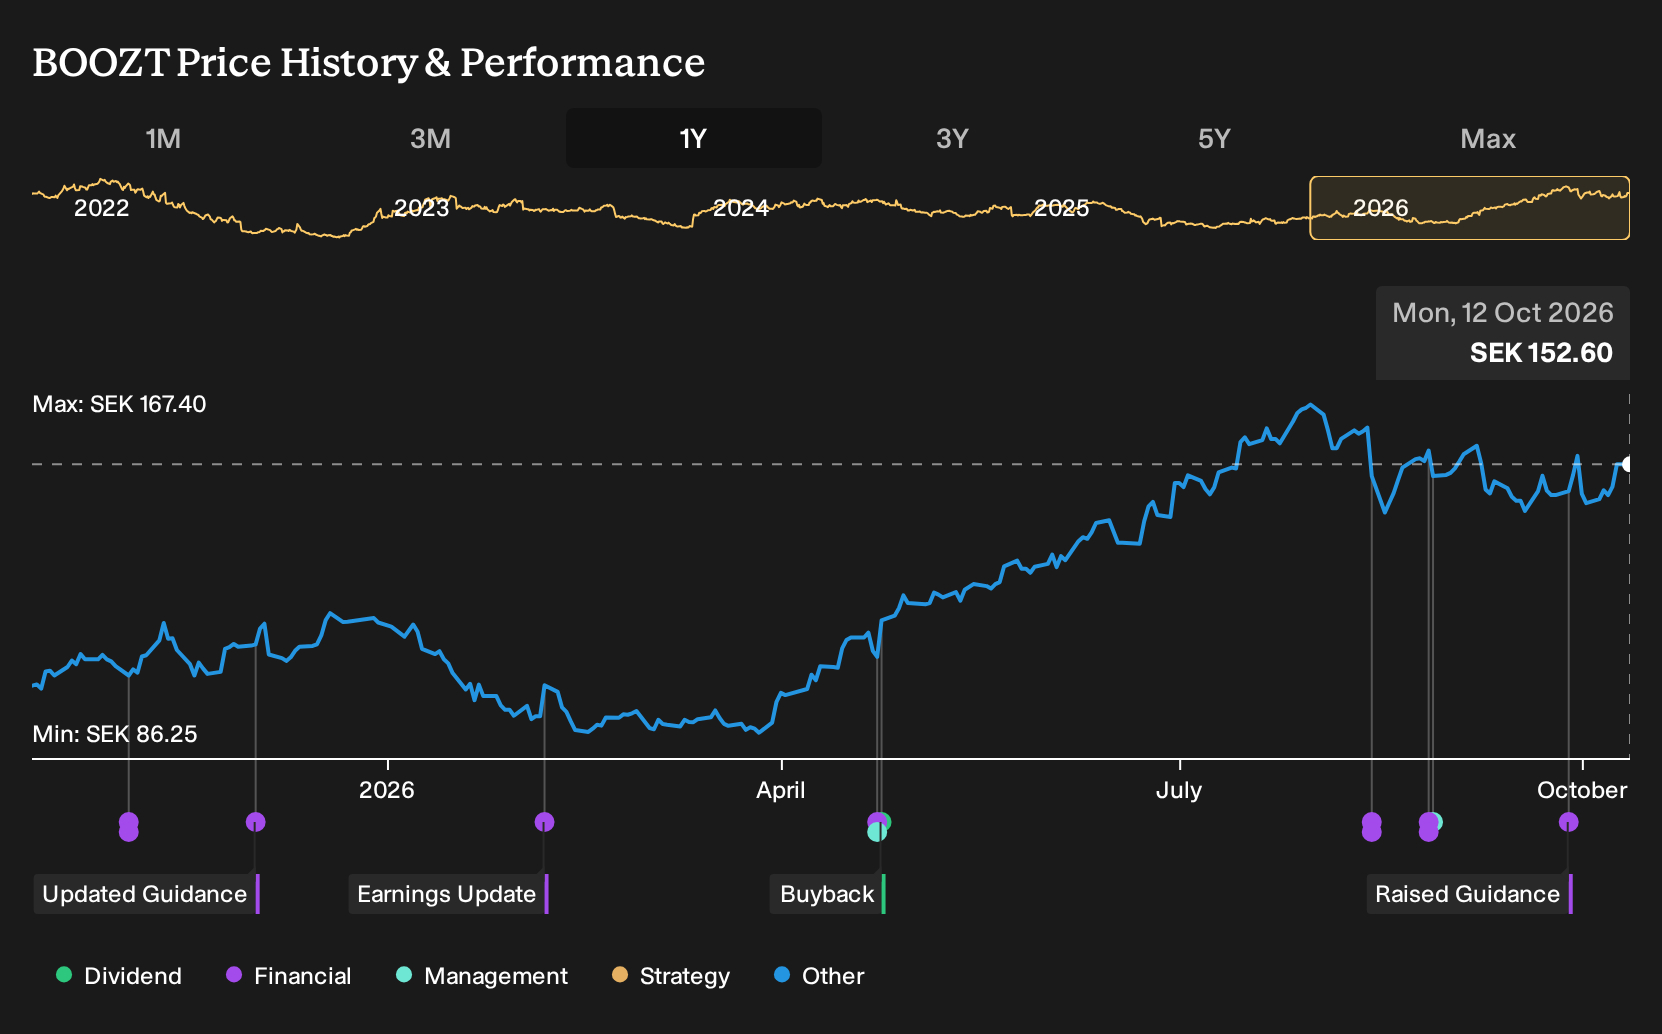
If Boozt was sitting on a watchlist instead of in a portfolio, the past year may feel like a sharp miss. Investors who held Boozt over the past year are up 55.4%, including dividends. That outcome landed even as the latest Q2 report showed revenue at 2,061 million SEK with profit at 70 million SEK and a lower net margin. If you rewind to October 2025, what clues around Booztlet’s scalability could have flagged that margin worries might not cap returns?
If the move has made Boozt harder to judge, start where the gap is still open and scan 179 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Boozt
The shares cost SEK97.3 at the start of the period, and Boozt sat between two very different but credible stories about where the business could head next.
On the optimistic side, the bullish narrative pointed to a Fair Value of SEK110, a price implied by assumptions rather than a hard fact. This view was built on annual revenue growth of 7.8% and profit margin lifting to 4.9% over three years.
The cautious view anchored to a Fair Value of SEK85 and focused on rising environmental and digital marketing costs. In this case, revenue growth was assumed at 5.0% and profit margin easing to 3.7% over the same horizon.
What The Results Changed In The Boozt Debate
The Q2 2026 numbers gave Boozt investors a split message. Revenue moved from 1,823 million SEK in Q2 2025 to 2,061 million SEK, which supported the optimistic call for ongoing top line expansion. Net income slipped from 76 million SEK to 70 million SEK and net margin moved from 4.2% to 3.4%, which challenged the higher margin path. Taken together, the evidence cut both ways.
The whole episode turned on one assumption, that Boozt could widen profitability while growing sales. When you test another retailer, track whether margin trends in filings actually move in the same direction as the revenue story you are being sold.
What Boozt's Run Leaves You Paying For Today
Boozt now trades at SEK153, after a 55.4% gain over the past year. The selected Narrative places its Fair Value above that level and ties the case to how Booztlet, logistics and technology shape profit quality rather than just headline growth.
In practical terms, the Narrative argues today's price still does not fully credit Booztlet’s potential operating leverage and the impact of higher value, multi category baskets on long run profitability.
"While analysts broadly agree that Booztlet is effective for inventory clearance and margin protection, they may be underestimating the platform's potential to unlock significant long-term operating leverage as it scales. This would turn Booztlet from a margin-dilutive clearance channel into a high-volume, lower-cost driver of both revenue and net margin, particularly as multi-category purchases and average basket size expand."
The price and this Narrative do not agree. → Uncover what this Narrative says Boozt is actually worth
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 43% below our estimate - sells hardware-neutral oncology planning tools shifting clients to automation subscriptions.
- Company 2 - 28% below our estimate - expands field teams to secure maintenance work feeding lucrative modernization projects.
- Company 3 - 34% below our estimate - builds high-speed networking platforms for hyperscale customers upgrading data center capacity.
Three companies from the same screener. Open all 202 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com