
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AutoZone (AZO) Board Change Draws Focus, Is The Stock Undervalued?
Board change puts fresh attention on AutoZone stock
AutoZone (AZO) drew fresh focus after director Claire R. McDonough told the board on October 6, 2026, that she will not stand for reelection because of schedule conflicts with a new executive role.
The announcement comes at a time when AutoZone is already being watched for its earnings outlook and recent estimate revisions. This is prompting investors to reassess how board turnover fits alongside fundamentals and the stock’s recent performance profile.
AutoZone’s board news lands at a time when the share price has slipped year to date, with a 12.26% decline in year to date share price return and a 29.26% drop in 1 year total shareholder return, even though the 5 year total shareholder return of 64.85% still reflects a much stronger long run outcome.
Scan how board-sensitive stories like AutoZone’s compare with other retailers by focusing on resilient operators in our list of solid balance sheet and fundamentals (25 results)
AutoZone now trades below both analyst targets and some intrinsic value estimates after a sharp one year pullback. Is that discount compensation for real risks, or is the market becoming too cautious about the retailer’s cash flows?
Most Popular Narrative: 2% Overvalued
AutoZone’s most followed valuation storyline pegs fair value at $2,829.08, a touch below the recent $2,898.85 close. This puts the stock on a small premium in that framework and raises fresh questions about how much good news is already in the price.
AutoZone closed its fiscal fourth quarter with earnings per share up 15.1% and a store count that crossed 8,000 for the first time. These figures were built substantially on a $96 million tariff refund and a LIFO charge that landed $65 million lighter than the year-ago period. Underneath that headline, domestic DIY sales turned negative, and the SG&A discipline management explicitly promised three months earlier gave way to the fastest per-store expense growth of the year.
See why 1 investors see AutoZone as 2% overvalued.
Result: Fair Value of $2,829.08 (OVERVALUED)
Still, the AutoZone narrative faces pressure if DIY traffic weakness persists or if SG&A growth continues to outpace sales and erodes the expense discipline story.
Find out about the key risks to this AutoZone narrative.
Another view on AutoZone’s valuation
The user narrative paints AutoZone as about 2% overvalued at $2,829.08, yet the SWS DCF model points the other way. On that cash flow view, AutoZone at $2,898.85 is trading below an estimated future cash flow value of $3,386.11, which presents the current pullback as a possible undervaluation. Which story do you rely on when the models disagree by this much?
Look into how the SWS DCF model arrives at its fair value.
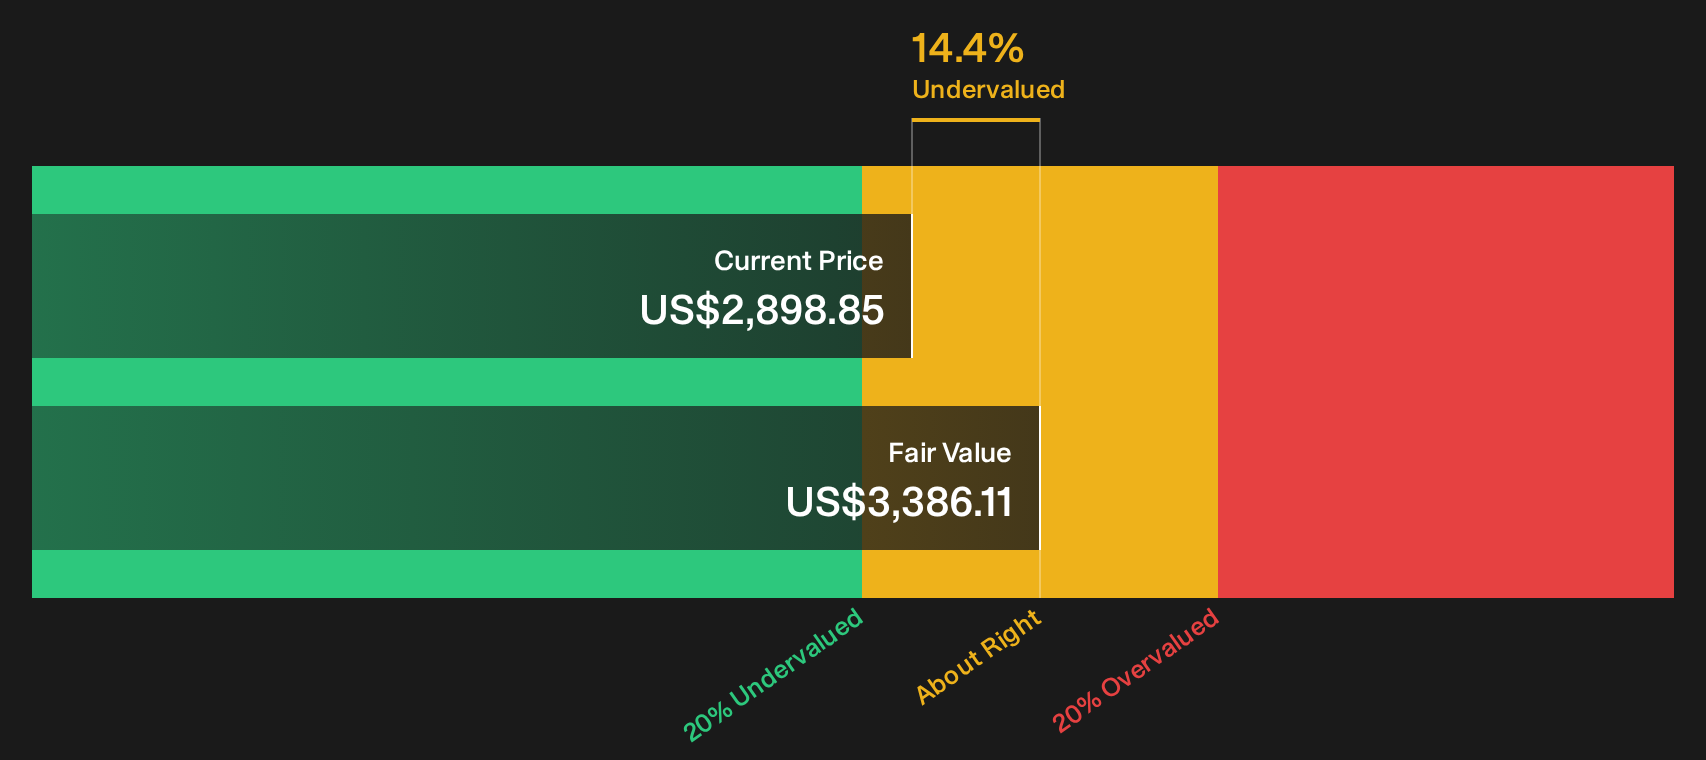
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AutoZone for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around AutoZone can feel confusing, so move quickly to check the full picture and shape your own view with the 4 key rewards and 2 important warning signs
Looking for more AutoZone investment ideas?
If AutoZone has sharpened your thinking, use that momentum and scan wider opportunities so you are not relying on a single stock for your next move.
- Target durable compounding potential by reviewing companies that screen as 29 high quality undervalued stocks and may warrant deeper fundamental research.
- Strengthen defensiveness in your portfolio by assessing a 32 resilient stocks with low risk scores that could help balance more volatile holdings.
- Stay early to quality stories by tracking a 20 high quality undiscovered gems that the broader market may not be focusing on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com