
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Canadian Imperial Bank of Commerce (TSX:CM) Below Fair Value As Strong Earnings Reassure Investors?
Canadian Imperial Bank of Commerce (TSX:CM) has put its recent earnings front and center, highlighting a 16.8% adjusted return on equity and an excess returns model that points to profitability above its cost of capital.
Recent trading paints a mixed picture for Canadian Imperial Bank of Commerce. In the short term, the 1-day share price return of 1.27% contrasts with a 30-day share price decline of 2.06% and a 90-day drop of 6.63%, which hints that near term momentum has cooled. At the same time, the year-to-date share price return of 23.30% points to a stronger underlying trend. Over a longer horizon, the 1-year total shareholder return of 43.42% and the very large 3-year total shareholder return near 2.4x suggest investors who stayed the course have been rewarded. The current CA$155.63 share price sits against that backdrop of strong multi-year gains and fresh earnings, plus new product launches and a recent fixed income offering that all factor into how the market prices both growth potential and risk today.Compare Canadian Imperial Bank of Commerce’s run and earnings power with other institutions that screen for similar quality using 8 high quality undervalued stocks to see where the market may be missing the story.
Canadian Imperial Bank of Commerce has sprinted higher over the past year, yet still trades below both analyst targets and intrinsic value estimates. Where does fair value really land in that kind of gap?
Price-to-Earnings of 14.6x: Is it justified?
Canadian Imperial Bank of Commerce trades on a P/E of 14.6x, which puts the CA$155.63 share price in a zone where the market is paying up relative to some peers while still leaving room compared with several value checks.
The P/E ratio compares the current share price to earnings per share and, for a lender like Canadian Imperial Bank of Commerce, it gives you a quick read on how much investors are willing to pay for today’s profit base. For a bank with high quality earnings and profit growth, a richer P/E can signal that the market is comfortable paying more for each dollar of net income.
Here, the 14.6x multiple sits below the estimated fair P/E of 17.6x and under the peer average of 17x. That combination points to a market that is pricing Canadian Imperial Bank of Commerce at a discount to what regression based fair value suggests could be justified, even though the stock is more expensive than the wider North American banks industry average of 11.4x.
Explore the SWS fair ratio for Canadian Imperial Bank of Commerce.
Result: Price-to-Earnings of 14.6x (UNDERVALUED).
Still, Canadian Imperial Bank of Commerce faces pressure if credit losses rise or if funding markets tighten, which could quickly challenge the current valuation story.
Find out about the key risks to this Canadian Imperial Bank of Commerce narrative.
Another View on Canadian Imperial Bank of Commerce’s Value
The SWS DCF model points to a very different picture for Canadian Imperial Bank of Commerce. At a CA$155.63 share price against an estimated future cash flow value of CA$228.24, the bank screens as undervalued, which raises a simple question for you: Is the gap a margin of safety or a sign the model is too optimistic?
Look into how the SWS DCF model arrives at its fair value.
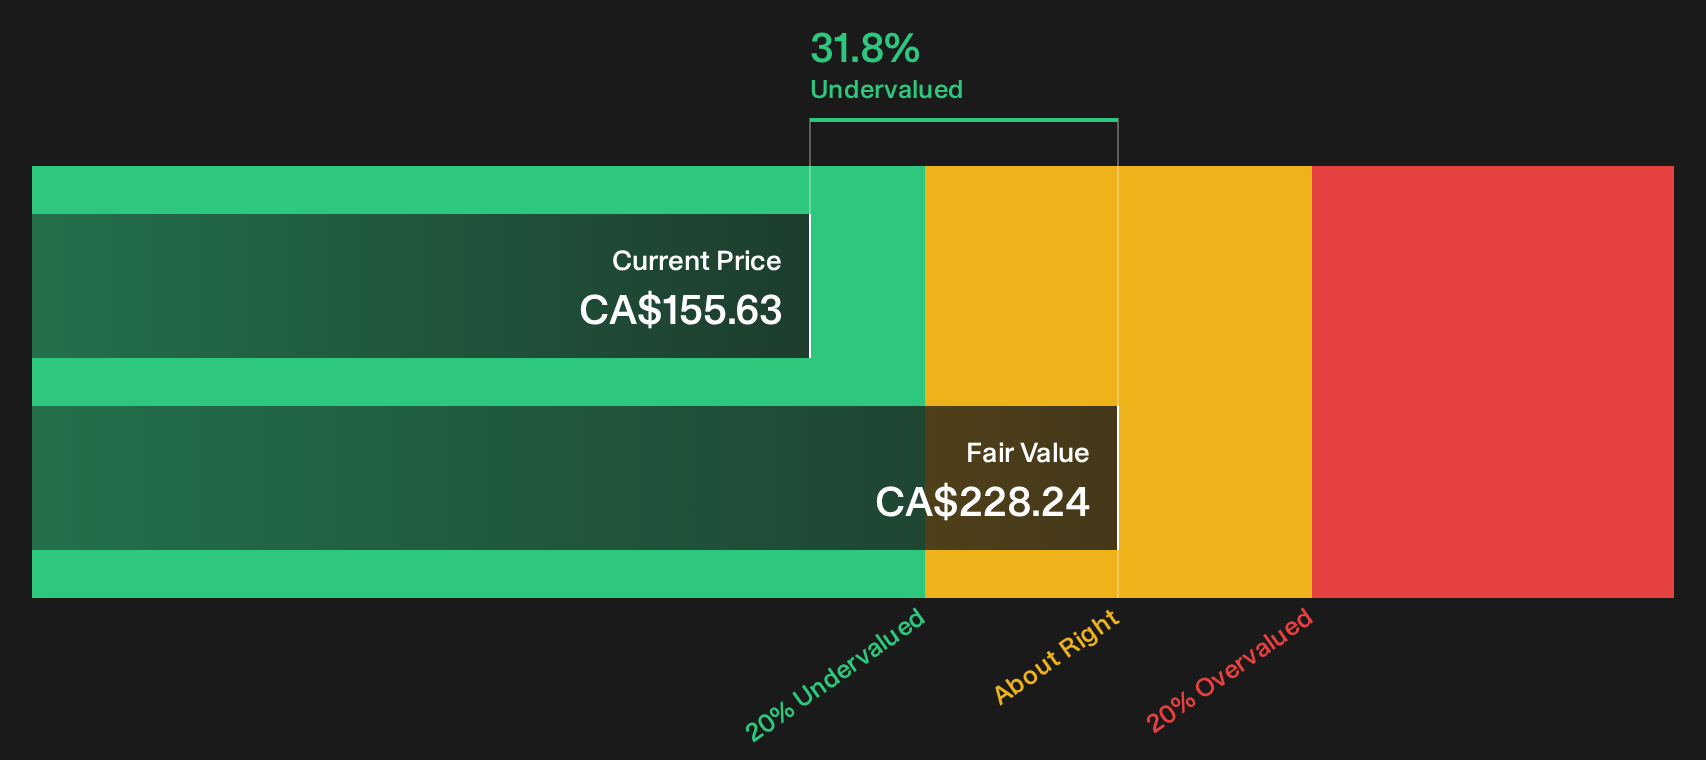
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Canadian Imperial Bank of Commerce for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Canadian Imperial Bank of Commerce in this review tilts positive, with valuation and return signals drawing attention. Act quickly, pressure test the thesis against your own expectations, and see what stands out in the 4 key rewards.
Looking for more investment ideas beyond Canadian Imperial Bank of Commerce?
Do not stop with one bank. Broaden your watchlist using targeted stock ideas that match the kind of balance between quality, risk, and price that you care about.
- Spot potential bargains early and review the 8 high quality undervalued stocks that combine solid fundamentals with pricing that may not fully reflect their performance yet.
- Prioritize resilience and scan the 8 resilient stocks with low risk scores if you want businesses with steadier risk profiles to anchor your portfolio.
- Hunt for underfollowed opportunities and check the 10 high quality undiscovered gems before others catch on to stocks with strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com