
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Minerals 260 (ASX:MI6) Is Getting Attention Today
Minerals 260 earnings jolt grabs investor focus
Minerals 260 (ASX:MI6) has swung from a full year loss to a net profit of A$83.48 million, after reporting results for the year ended June 30, 2026. That earnings shift is now at the center of investor attention.
The net profit news lands after a powerful run in Minerals 260’s share price over 2026, with a year to date share price return of 93.02% and a 1 year total shareholder return of 167.74%. However, shorter term momentum has cooled, with a 30 day share price return of 5.68% and a 7 day share price return of 2.92% into the latest close at A$0.83.
See how Minerals 260 compares with other miners experiencing sharp earnings swings by reviewing the hand picked 15 high quality undiscovered gems in the current market.
Minerals 260 has just swung to profit after a huge share price run, yet the stock has cooled in recent weeks. Do you lean into the earnings turnaround now, or wait for a cheaper entry later?
Price-to-earnings of 24.6x: Is it justified for Minerals 260?
Minerals 260 now trades on a P/E of 24.6x, which prices the recent swing to a A$83.48 million profit at a premium to both peers and the wider metals and mining group.
The P/E ratio compares today's share price with current earnings per share. For a business like Minerals 260 that has only just moved into profitability and reports no meaningful revenue, that metric effectively asks how much investors are willing to pay upfront for each dollar of current profit.
That willingness looks high. The stock is described as expensive relative to its own estimated fair P/E of 24.5x. The market could eventually move closer to that level if enthusiasm cools. The current 24.6x multiple also sits well above the Australian metals and mining industry average of 11.6x and beyond a 20.8x peer group average, which signals investors are already paying up compared with comparable miners.
Explore the SWS fair ratio for Minerals 260.
Result: Price-to-earnings of 24.6x (OVERVALUED)
Still, the Minerals 260 story carries clear risks, including zero reported revenue and reliance on exploration outcomes that may not support today’s rich P/E.
Find out about the key risks to this Minerals 260 narrative.
Another view on Minerals 260 valuation
The P/E work says Minerals 260 looks expensive, yet the SWS DCF model tells a different story. On that cash flow view, A$0.83 trades above an estimated value of A$0.42, so the shares screen as overvalued on both earnings and cash flow. Which lens do you trust more when the business has zero revenue today?
Before leaning on a single approach, it can help to see how the SWS DCF model builds up that A$0.42 figure and what would need to change in the inputs for Minerals 260 to look closer to fairly priced. Look into how the SWS DCF model arrives at its fair value.
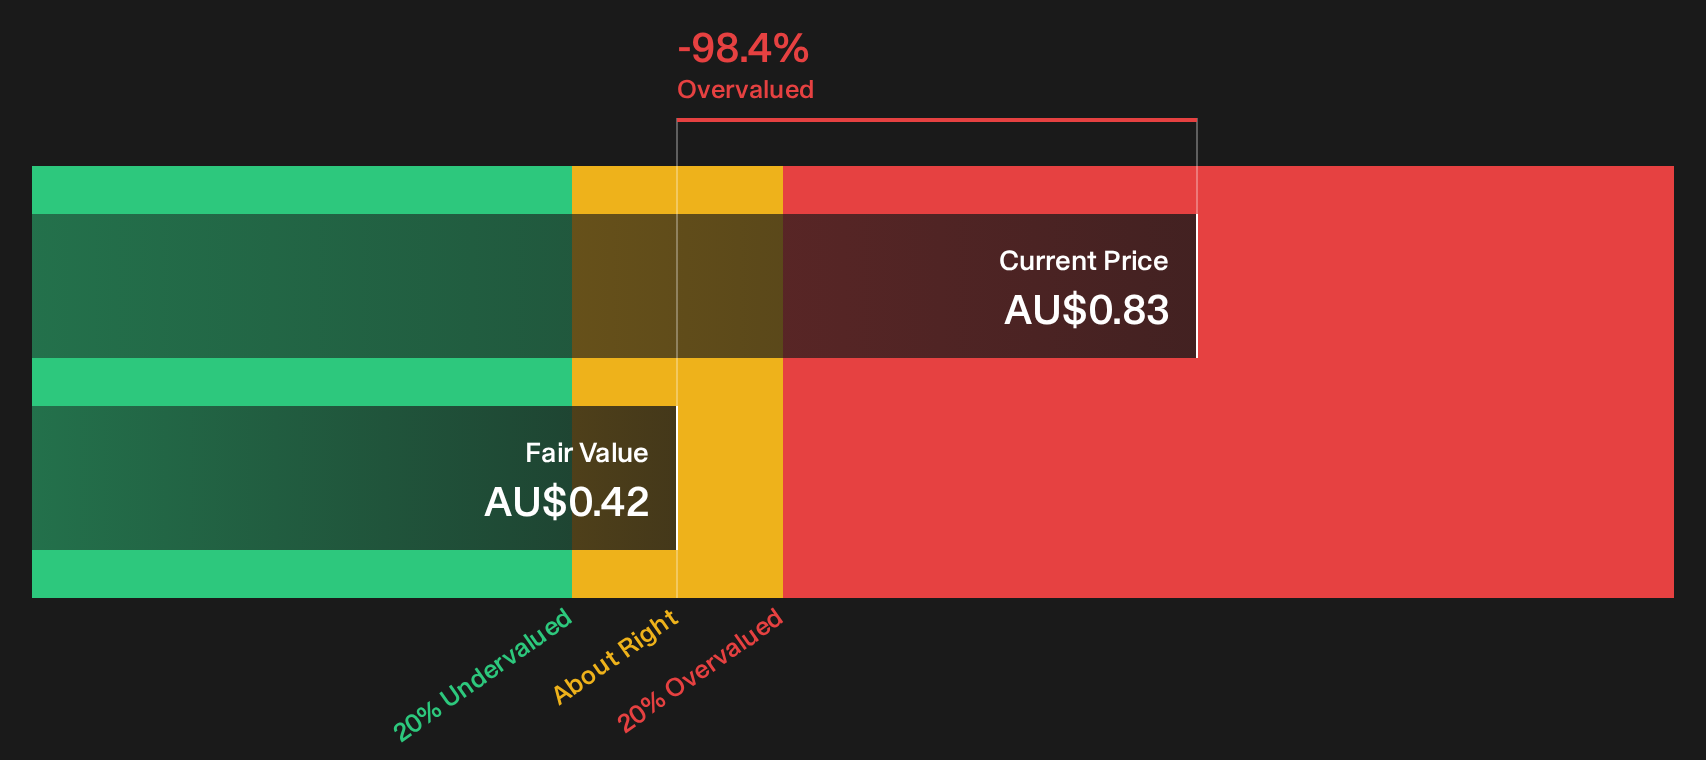
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Minerals 260 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Minerals 260 so far. If that leaves you on the fence, move quickly from headline impressions to your own view by weighing the 3 key rewards and 3 important warning signs.
Looking for more Minerals 260 style investment ideas?
If Minerals 260 has sharpened your focus, do not stop at a single opportunity. Broadening your watchlist now can shape your next few moves.
- Target potential mispricing by scanning a 4 high quality undervalued stocks that filters for strong fundamentals paired with discounted valuations.
- Strengthen your downside protection by reviewing a 7 resilient stocks with low risk scores that prioritises resilient balance sheets and steadier risk profiles.
- Spot tomorrow's potential standouts early by working through a 19 elite penny stocks with strong financials packed with smaller companies that already show solid financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com