
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Stocks That Could Benefit If Washington Ramps Up Corporate Investigations
A potential Democratic win in the midterms could flood Washington with new corporate probes, turning legal risk into the story everyone is suddenly forced to care about. While some companies face hearings and headlines, others quietly sell the tools, expertise, and D&O insurance that help businesses cope. This article walks through 3 stocks from that second group and explains how fresh investigations could reshape their opportunity set.
The three stocks below are only a starter set. The full screen surfaced 20 more publicly traded legal, investigations, and D&O insurance providers with equally compelling stories that are not covered here. If you want to identify and analyze the businesses that best fit your own thesis, head straight into the US-Listed Legal, Investigations, and D&O Insurance Providers screener
Exponent (EXPO)
Exponent fits directly into the screener theme because its scientists and engineers are often called in when legal disputes, regulatory questions, or complex failures demand expert evidence. This is exactly the kind of work that can become more important if investigations pick up.
Exponent runs a science and engineering consulting business across areas like mechanical, electrical, environmental, and health science. Most revenue comes from Engineering and Other Scientific work at about US$541 million, with Environmental and Health adding roughly US$91 million, and the stock valued at about US$3.3b.
Growing demand for utility risk modeling, infrastructure engagements, and data center failure analysis linked to rising power needs, more complex grids, and challenging energy and cooling systems is expanding Exponent’s pipeline of engineering projects. This can feed into higher net revenues and support EBITDA margins as this work converts from studies into billable hours.
The question is what happens if a single pressure point in that mix quietly shifts and changes how much of that high value work actually reaches margins.
When that pressure point moves, read the full narrative for Exponent to see whether Exponent’s project mix is quietly decoupling revenue strength from long term earnings power.

Crawford (CRD.B)
Crawford & Company plugs into the screener theme because it operates where investigations, liability events, and insurance claims all intersect, and the business has been reshaped around higher value outsourced claims work that leans heavily on technology.
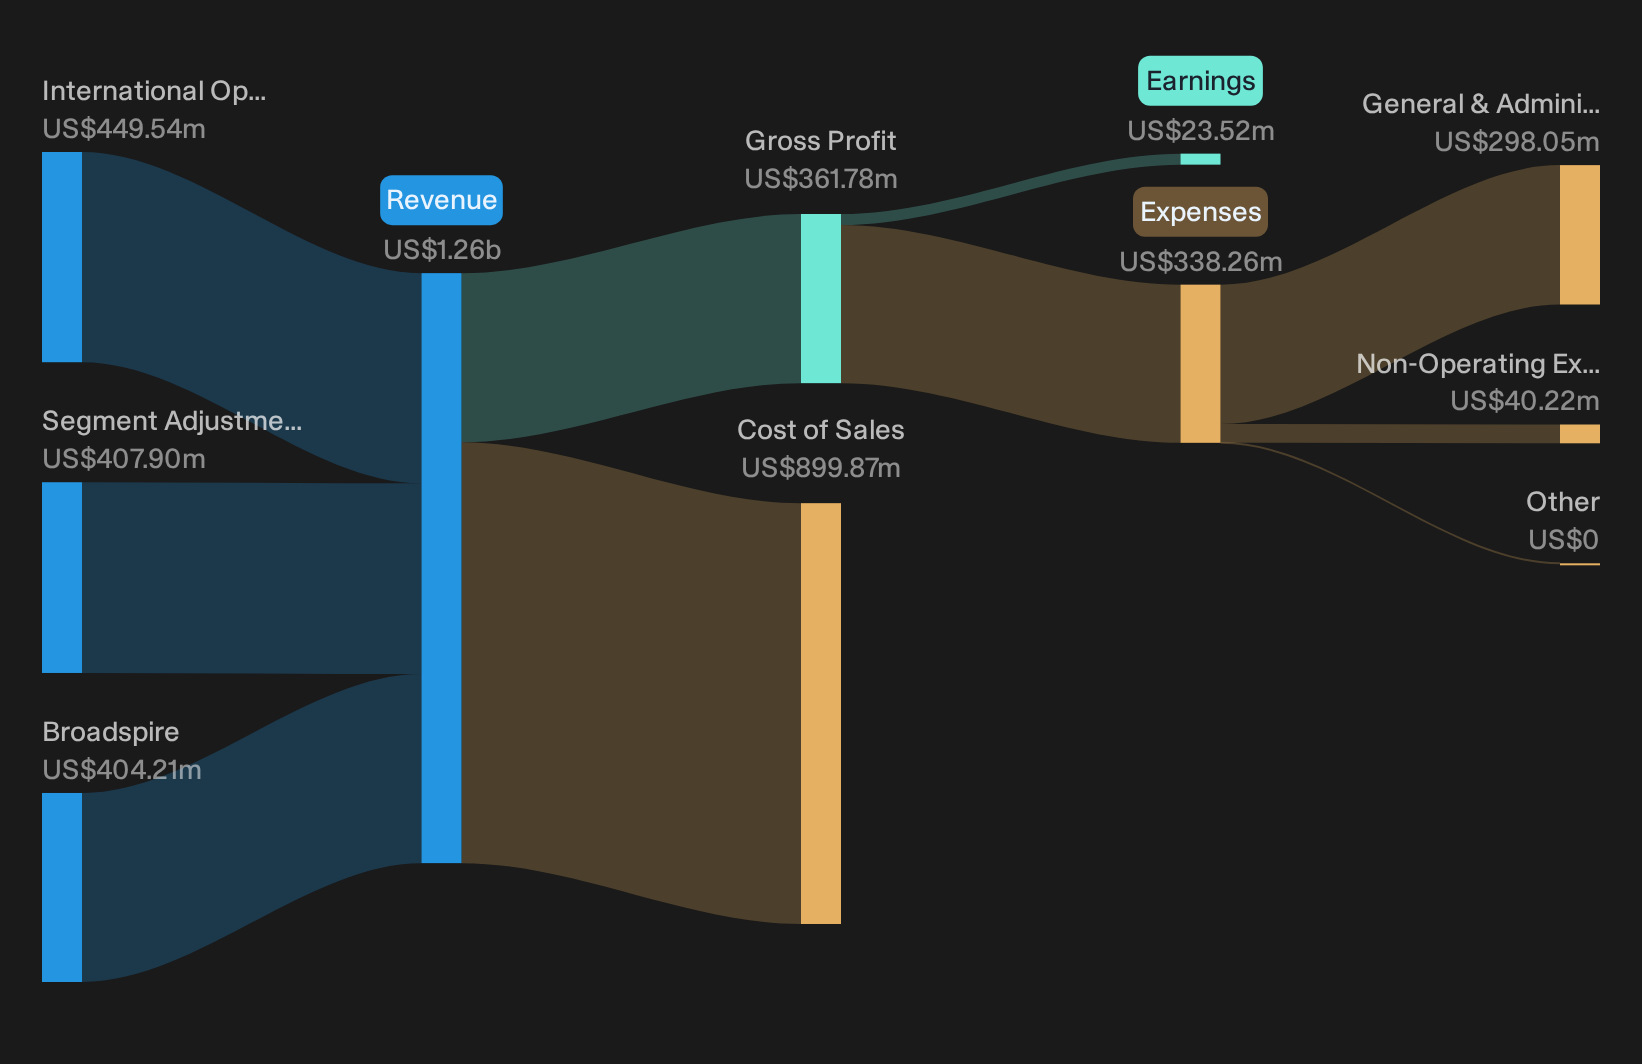
Crawford & Company runs outsourced claims management and related legal, repair coordination, and risk support services for insurers and corporations worldwide, producing about US$449 million from International Operations and US$404 million from Broadspire, with a segment adjustment of roughly US$408 million, and a market cap near US$607 million.
Crawford's focus on insurtech solutions is now reinforced by targeted AI and data tools across claims workflows that are intended to shorten cycle times and lift adjuster productivity, which can support net margin and earnings performance.
A key variable is whether a gradual shift in the mix of complex, higher value claims work eventually reshapes Crawford’s earning power.
That shift in claim complexity is exactly what full narrative for Crawford unpacks, showing where Crawford’s tech heavy model could be quietly accelerating earnings power.
LegalZoom.com (LZ)
LegalZoom.com gives this screener direct exposure to the legal and compliance workflows that flare up when scrutiny on business behavior rises. It packages those services into an online platform that aims to turn complex requirements into repeatable, subscription friendly tasks for smaller enterprises and households.
LegalZoom.com runs an online portal for small businesses and consumers that provides legal, compliance, and business management services, with about US$792 million generated from its business formation platform, and the stock valued at roughly US$1.0b.
For this screener, LegalZoom.com matters because heightened investigations and new rules often drive founders and existing owners toward digital legal help rather than traditional law firms. This plays directly to its blend of self service tools and human in the loop subscriptions.
The shift in Google toward AI powered search has already coincided with a 5% decline in business formations to about 125,000 in Q2 2026 and a 1% decline in transaction revenue to US$72 million.
What happens if one unseen pressure in that evolving mix quietly decides whether richer subscription work can more than offset softer formation volume.
If that pressure point decides the story, read the full narrative for LegalZoom.com to see whether LegalZoom.com’s subscription engine is quietly masking a stronger long term opportunity.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, entry points can vanish as prices react and stories get fully priced while it matters. Scan these under the radar for now opportunities and get in early.
- Spot resilient cash engines early by running the list of solid balance sheet and fundamentals (25 results) and focus your research on businesses where financial risk does not crowd out long term potential.
- Track income workhorses before yields get compressed by studying the 8 dividend fortresses and concentrate on payouts that look built to endure real world stress.
- Ride infrastructure and electrification trends while they are still forming by screening the 43 power grid technology and infrastructure stocks and zero in on operators behind tomorrow’s grid upgrades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com