
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exploring Three Undiscovered Gems In The Asian Market
In recent weeks, the Asian markets have exhibited a mixed performance, with Japan's stock indices gaining amid global technology rallies and China's mainland shares facing pressure from elevated bond yields and geopolitical tensions. As investors navigate these dynamic conditions, identifying stocks that demonstrate resilience and growth potential becomes crucial. In this context, exploring lesser-known companies in Asia could uncover opportunities that align well with the current market landscape.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Shanghai Fudan Microelectronics Group | 16.49% | 9.29% | -6.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
Sejin Heavy Industries (KOSE:A075580)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Sejin Heavy Industries Co., Ltd. is a South Korean company that specializes in the manufacturing and sale of shipbuilding equipment, with a market capitalization of ₩528.70 billion.
Operations: Sejin Heavy Industries generates revenue primarily from its shipbuilding sector, totaling ₩386.76 billion. The company's financial performance is influenced by the dynamics of this sector, with particular attention to cost management and profitability metrics.
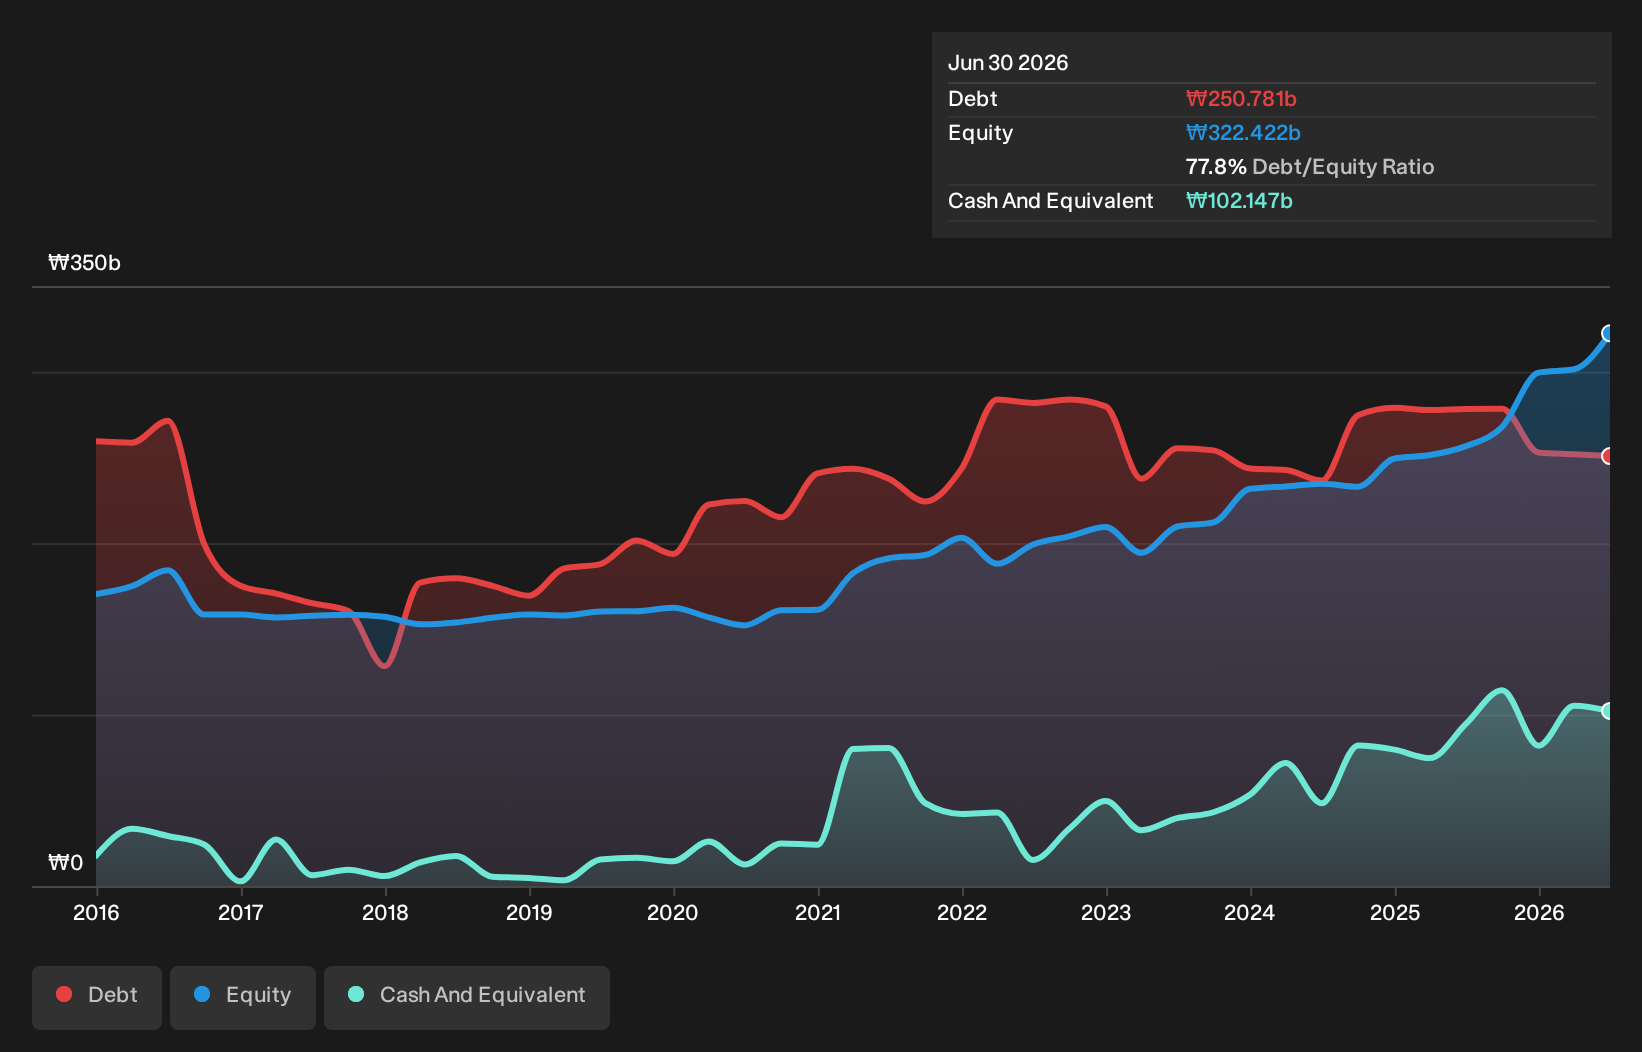
Sejin Heavy Industries, a smaller player in the machinery sector, has seen its earnings grow by 116.5% over the past year, outpacing the industry’s 47.8%. Trading at 37.2% below estimated fair value suggests it offers good relative value compared to peers. Despite a high net debt to equity ratio of 46.1%, debt levels have decreased from 124.3% to 77.8% over five years, indicating improved financial health. Recent results showed second-quarter sales of KRW 828 million and net income jumping to KRW 16,542 million from KRW 4,279 million last year, reflecting robust profitability and potential for future growth.
Hong Leong Asia (SGX:H22)
Simply Wall St Value Rating: ★★★★★★
Overview: Hong Leong Asia Ltd. is an investment holding company that manufactures and distributes powertrain solutions, building materials, and rigid packaging products across the People’s Republic of China, Singapore, Malaysia, and internationally with a market cap of SGD2.04 billion.
Operations: Hong Leong Asia generates significant revenue from its Powertrain Solutions segment at SGD4.87 billion, followed by Building Materials at SGD757.33 million. The company has a notable focus on the Powertrain Solutions sector as a primary revenue driver.
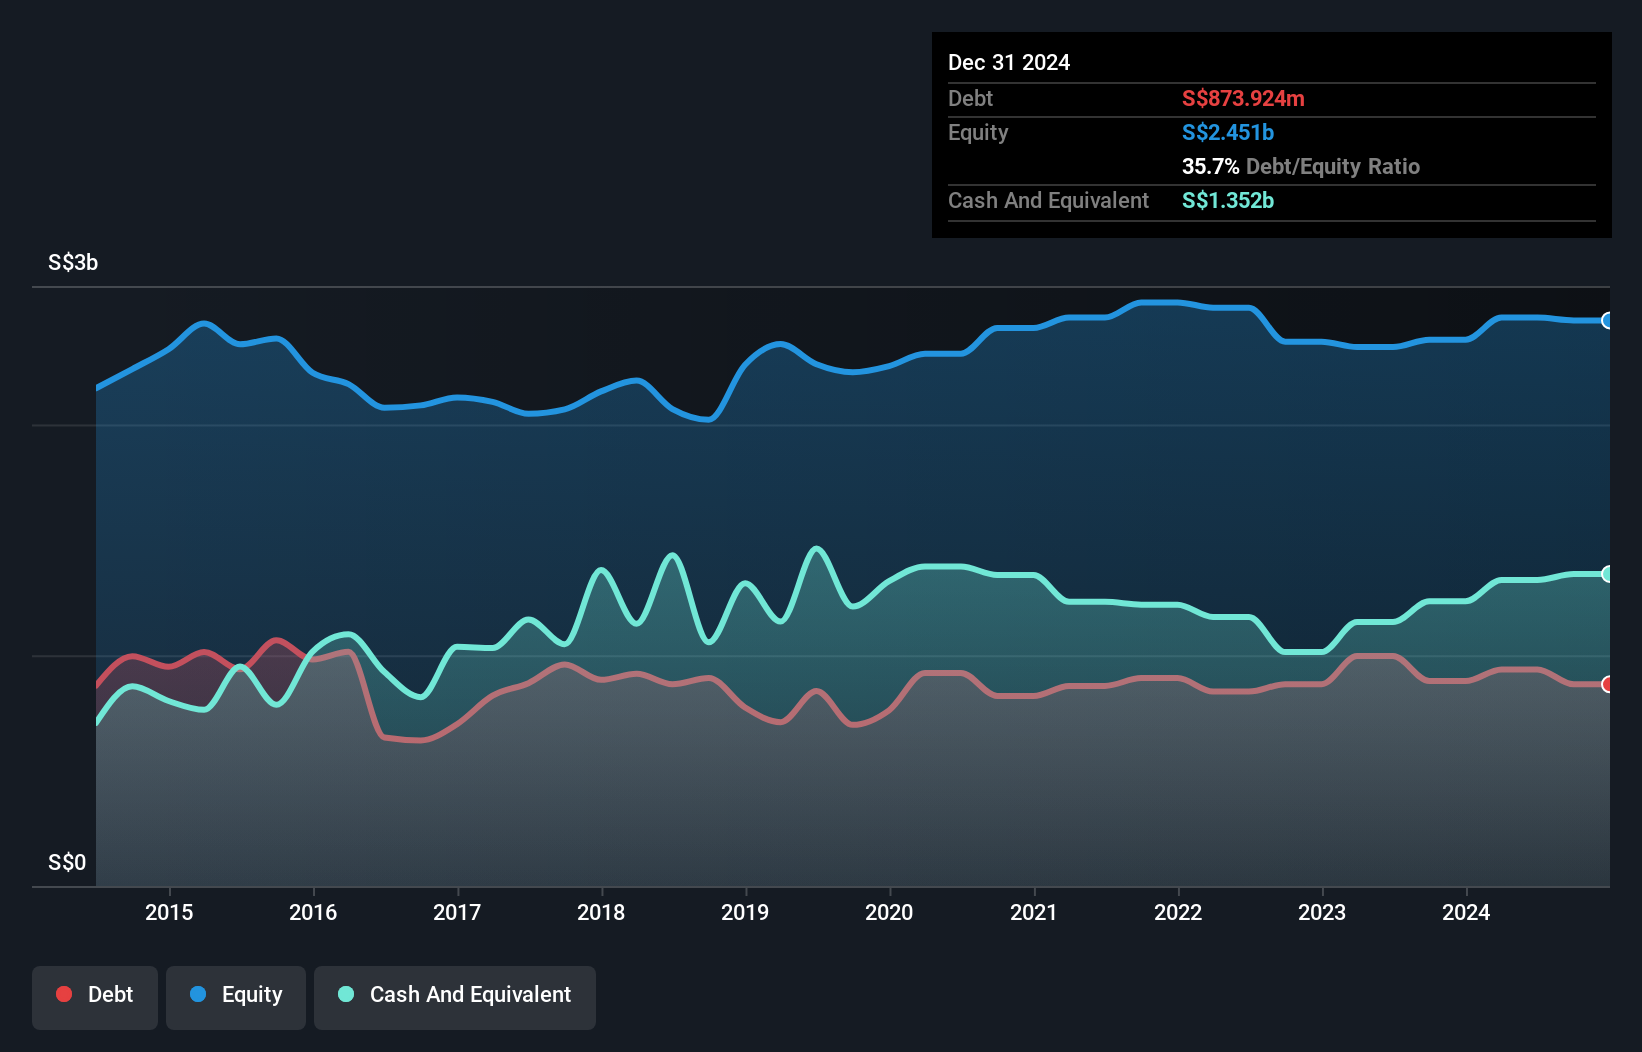
Hong Leong Asia, a dynamic player in the machinery sector, is trading at 74.6% below its estimated fair value, making it an intriguing prospect. Over the past year, earnings surged by 58.2%, outpacing the industry's growth of 12.7%. The company reported sales of SGD 3.13 billion for H1 2026, up from SGD 2.66 billion last year, with net income rising to SGD 91.91 million from SGD 56 million previously. Additionally, Hong Leong Asia's debt-to-equity ratio has improved over five years from 35.2% to a healthier level of 24.7%, indicating stronger financial stability and potential for future growth.
- Click to explore a detailed breakdown of our findings in Hong Leong Asia's health report.
Gain insights into Hong Leong Asia's past trends and performance with our Past report.
L&K Engineering (Suzhou)Ltd (SHSE:603929)
Simply Wall St Value Rating: ★★★★★★
Overview: L&K Engineering (Suzhou) Co., Ltd. provides specialized engineering technical services in China and has a market capitalization of CN¥28.27 billion.
Operations: L&K Engineering (Suzhou) Co., Ltd. generates revenue primarily through its specialized engineering technical services in China. The company's net profit margin is 9.5%, reflecting its profitability from these operations.
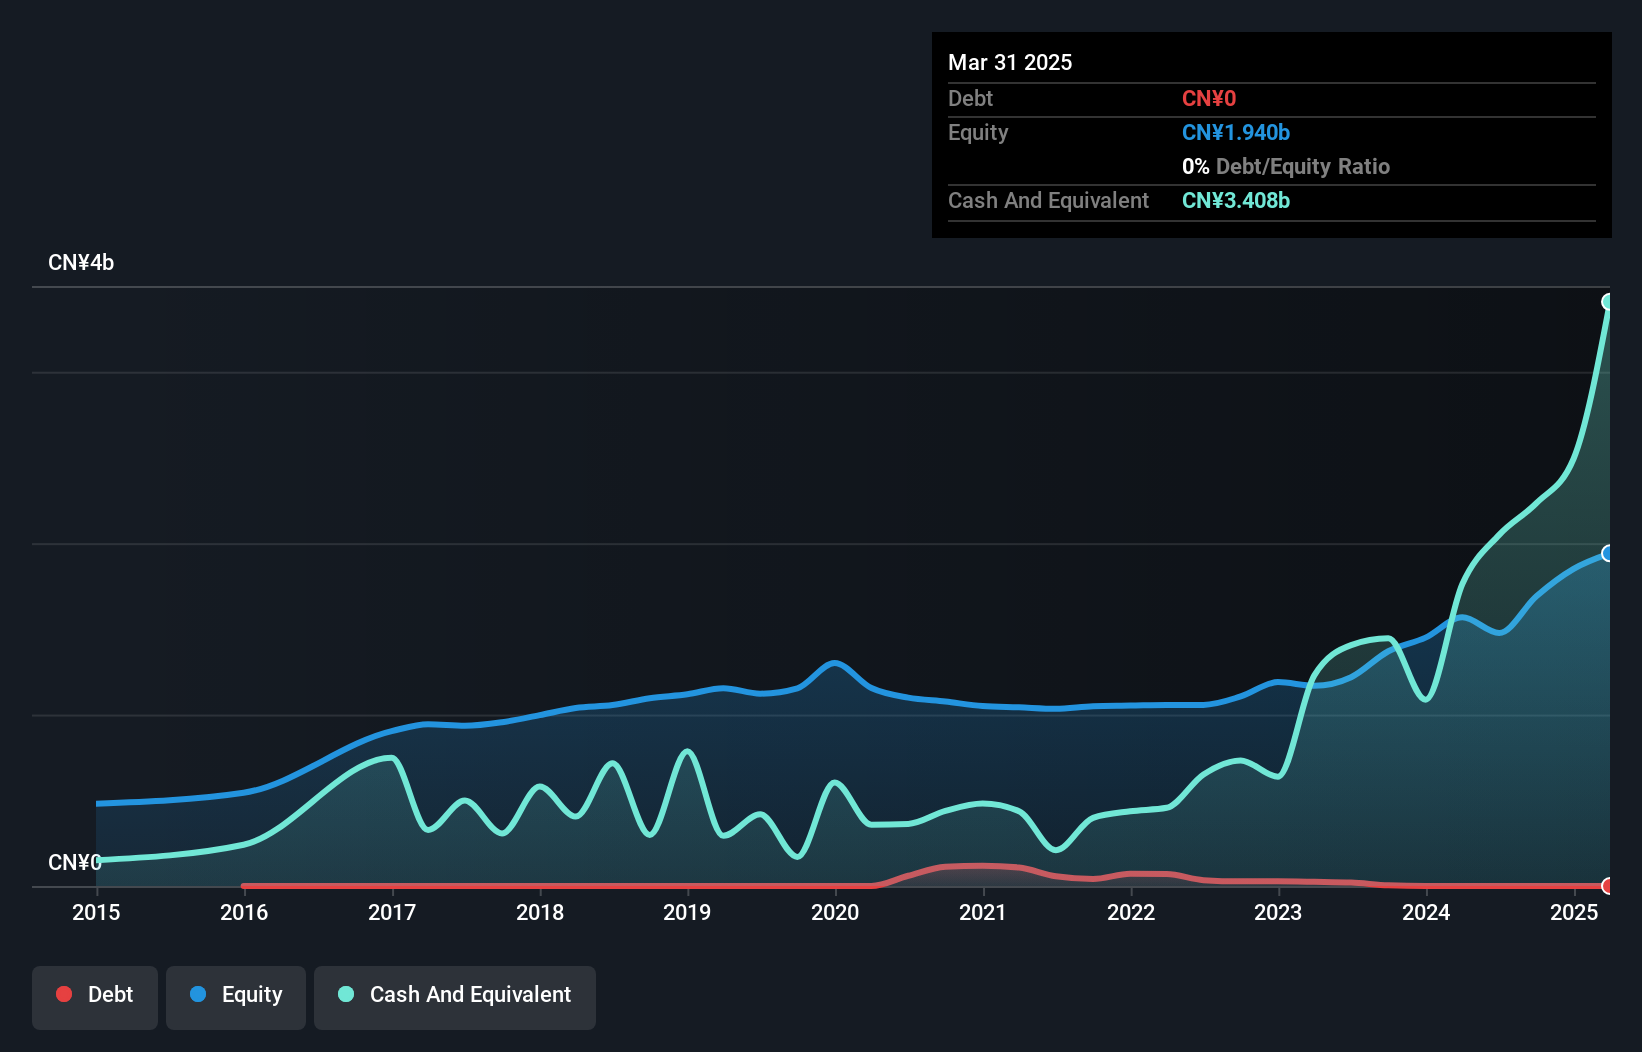
L&K Engineering (Suzhou) Co., Ltd. showcases impressive financial growth, with earnings rocketing by 118% over the past year, far outpacing the construction industry's -16% trend. The company reported a net income of CNY 490 million for H1 2026, up from CNY 161 million in the previous year, reflecting its robust performance. Trading at a substantial discount of around 70% below estimated fair value suggests potential upside for investors. Its debt-to-equity ratio has improved from 5.5 to 4.2 over five years, indicating prudent financial management and more cash than total debt further strengthens its position.
Seize The Opportunity
- Delve into our full catalog of 117 Asian Undiscovered Gems With Strong Fundamentals here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com