
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Tokyo Electric Power Company Holdings (TSE:9501) A Bargain Following Fresh Government Support?
Tokyo Electric Power Company Holdings (TSE:9501) just received another JPY 33.5 billion grant from the Nuclear Damage Compensation and Decommissioning Facilitation Corporation, extending long running government support for its nuclear accident compensation obligations.
The fresh JPY 33.5 billion grant lands at a time when Tokyo Electric Power Company Holdings’ 1 day share price return of 1.20% contrasts with a year to date share price decline of 27.47%, alongside a 1 year total shareholder return down 31.79% but a 5 year total shareholder return still up 45.88%. This suggests that recent weakness has pulled momentum back after earlier gains.
Scan beyond Tokyo Electric Power Company Holdings and compare it with 16 nuclear energy infrastructure stocks, which could also be influenced by shifts in nuclear policy, regulation, and long term infrastructure spending.
Bulls see Tokyo Electric Power Company Holdings as a backed utility with steady aid and long term assets, while bears point to heavy nuclear obligations and recent share price weakness. Which story does the valuation lean toward next?
Price-to-Earnings of 2.1x: Is it justified for Tokyo Electric Power Company Holdings?
On simple valuation metrics, Tokyo Electric Power Company Holdings looks inexpensive. The shares last closed at ¥520.8, and the stock trades on a P/E of 2.1x, which aligns with assessments that it is trading at good value compared with both its industry and its peers.
The P/E ratio compares the current share price with earnings per share. For a utility group that earns money from power generation, transmission, and retail, it reflects how much investors are paying for each unit of profit that the business is generating.
For Tokyo Electric Power Company Holdings, the current P/E of 2.1x contrasts with the Asian electric utilities sector at 14.1x and a peer average of 7.7x. That is a steep discount. It also sits well below an estimated fair P/E of 12.1x, a level that some investors may watch as a possible longer term reference point if sentiment or earnings quality stabilise.
Explore the SWS fair ratio for Tokyo Electric Power Company Holdings.
Result: Price-to-Earnings of 2.1x (UNDERVALUED)
Still, the unresolved nuclear compensation burden and the stock’s year to date decline of 27.47% could challenge any simple undervaluation story for Tokyo Electric Power Company Holdings.
Find out about the key risks to this Tokyo Electric Power Company Holdings narrative.
Another View: What The SWS DCF Model Says About Tokyo Electric Power Company Holdings
The story shifts once the SWS DCF model is brought in. At ¥520.8, Tokyo Electric Power Company Holdings is trading about 4.2% below an estimated future cash flow value of ¥543.39. That still points to undervaluation, but the gap is modest enough that small changes in assumptions could matter a lot.
Look into how the SWS DCF model arrives at its fair value.
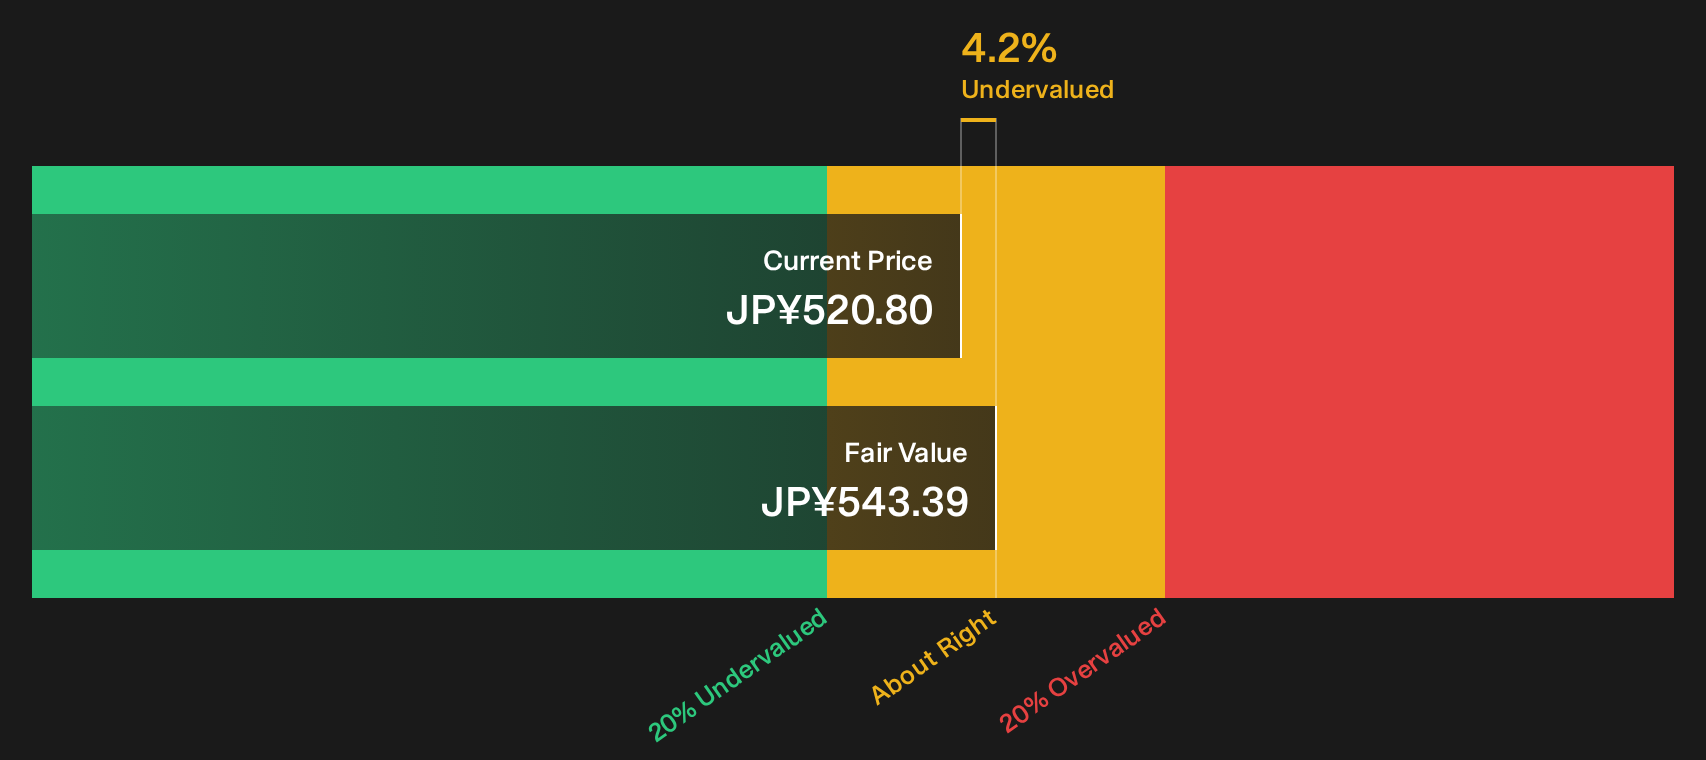
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Electric Power Company Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split between risks and rewards around Tokyo Electric Power Company Holdings is clear, and time spent with the data beats headlines every time. To see both sides in one place and pressure test your own view against the numbers, start with the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Tokyo Electric Power Company Holdings?
If you stop with Tokyo Electric Power Company Holdings, you only see one angle. Broader idea hunting gives you context, alternatives, and a better feel for risk.
- Pinpoint potential value plays by scanning our 12 high quality undervalued stocks that combine lower prices with stronger fundamentals than the wider market.
- Secure your income stream by focusing on companies in the 28 dividend fortresses that aim to pair higher yields with more resilient payout histories.
- Reduce portfolio stress by concentrating on businesses from the 23 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com