
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CareDx (CDNA) Could Be 8% Overvalued As Analysts Turn More Optimistic
Why analyst sentiment on CareDx has shifted
CareDx (CDNA) is back in focus after recent analyst commentary turned more positive, pointing to favorable transplant LCD decisions, updated Medicare fee schedules, and the Naveris acquisition as key drivers for the transplant diagnostics franchise.
The share price of CareDx has pulled back 8.85% over the past week, even after a 2.36% gain in the last session. However, the 30-day share price return of 26.68% and year-to-date share price return of 232.65% point to strong upward momentum. This mirrors a very large 1-year total shareholder return of 338.20% and a multi-year total shareholder return above 10x, before factoring in a weaker 5-year total shareholder return that is slightly below breakeven.
Scan how other potential breakout stories compare to CareDx by running through a curated list of 20 high quality undiscovered gems with similar transplant and specialty healthcare angles.
CareDx has moved from sharp losses to a multi-year gain above 10x, even though the past week turned lower. Is that curve now mostly about better fundamentals or a mood shift around the story, and what does the current valuation suggest?
Most Popular Narrative: 8% Overvalued
CareDx closed at $63.67, which sits above the most followed narrative fair value estimate of $58.83. Sentiment now leans toward the story being slightly ahead of the numbers and highly dependent on flawless execution around reimbursement and testing volumes.
The steady double-digit growth in testing volumes, particularly with the expansion of surveillance protocols for kidney, heart, and lung transplants, suggests ongoing market penetration and growing demand for CareDx's core testing services reflecting the global rise in organ transplants and chronic disease.
See why 5 investors see CareDx as 8% overvalued.
Result: Fair Value of $58.83 (OVERVALUED)
Still, the CareDx story can break if Medicare reimbursement shifts toward tighter bundled payments or if execution on AlloSure and HeartCare volumes disappoints raised expectations.
Find out about the key risks to this CareDx narrative.
Another View: What a DCF Says About CareDx
The analyst consensus calls CareDx about 8% overvalued at $63.67 versus a fair value of $58.83. A different lens tells a very different story. Simply Wall St's DCF model points to a future cash flow value of $92.25 per share, which suggests the stock trades at a steep discount. Which framework feels more realistic to you?
To understand how those projected cash flows translate into that higher figure, it helps to unpack the moving parts behind the SWS DCF model in more detail. Look into how the SWS DCF model arrives at its fair value.
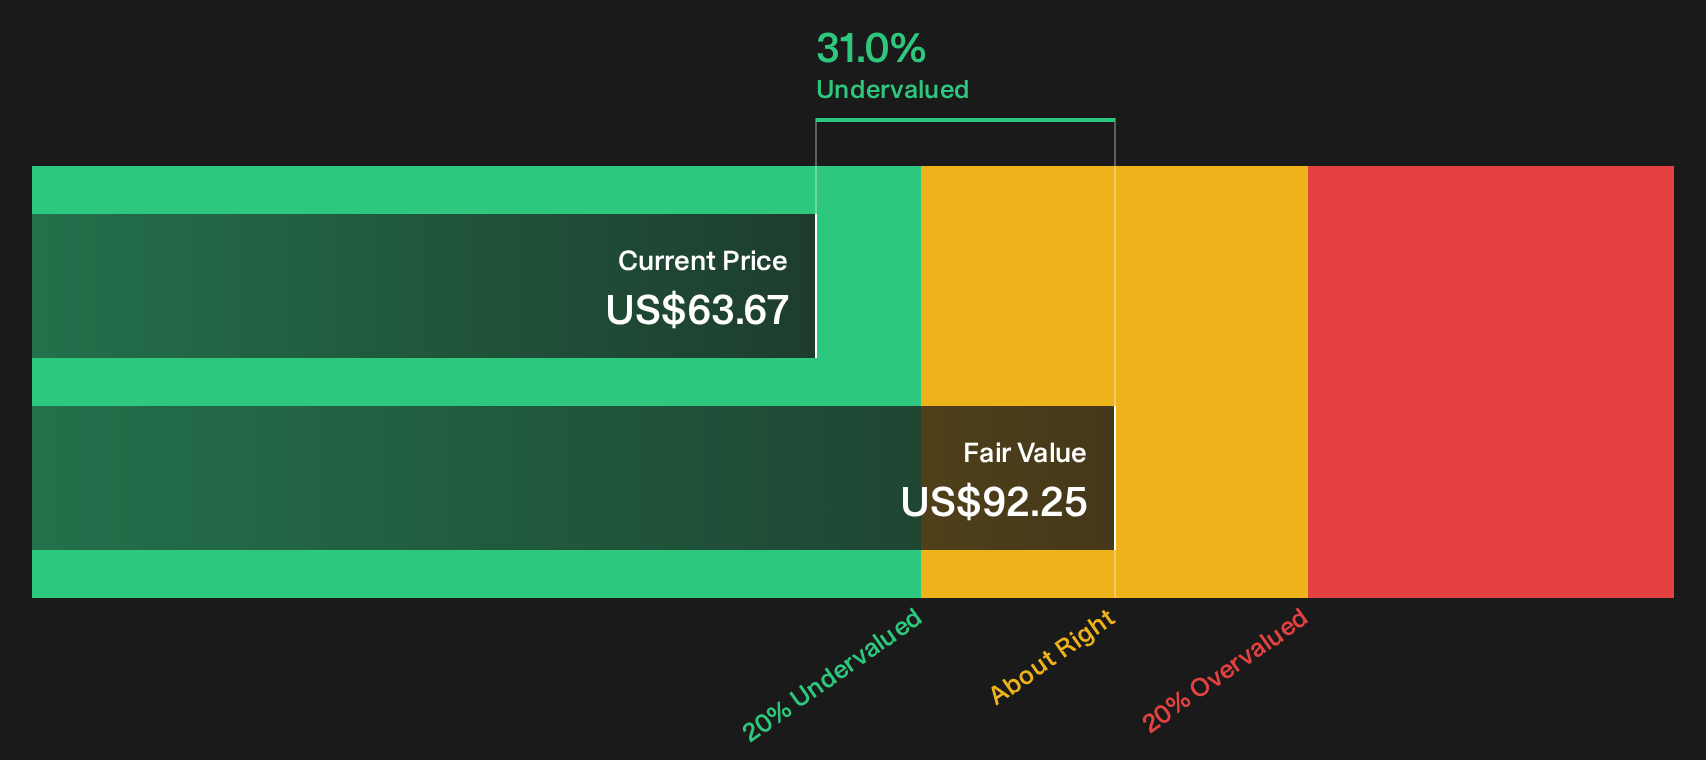
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CareDx for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around CareDx is split between concern and optimism, so consider acting promptly and review the data points that matter most to you. To weigh those trade offs in one place, start with the 2 key rewards and 4 important warning signs.
Looking for more CareDx style investment ideas?
If CareDx has sharpened your focus, do not stop here. The real edge comes from lining it up against other clear, data driven ideas on your radar.
- Pinpoint potential mispricings by scanning a 29 high quality undervalued stocks that combine stronger fundamentals with more conservative expectations baked into their current prices.
- Build a steadier portfolio core by filtering for 31 resilient stocks with low risk scores that aim to balance return potential with more resilient business profiles.
- Hunt for tomorrow's stories early by reviewing a 12 elite penny stocks with strong financials that already show cleaner balance sheets and more disciplined capital use.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com