
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Manufacturing Stocks Investors Are Watching Before The 2027 USMCA Review
North American trade rules are back under the microscope as the 2027 USMCA review looms, tariffs stay in the headlines, and governments rethink who they want building what and where. That mix can punish some businesses and quietly reward others. This article walks through three stocks from a trade resilient manufacturing screener that appear exposed to these shifting policy currents and explains why that matters for your portfolio.
The three examples below are just a starting sample, and the full screen surfaced 22 more North American manufacturers and industrial firms with equally compelling trade resilient narratives that are not covered in this article. To get straight to the data and identify your own highest conviction onshoring and regional supply chain ideas, analyze the North American Onshoring and Trade-Resilient Manufacturing screener.
Plexus (PLXS)
Plexus plugs directly into the onshoring story, acting as the behind the scenes partner that helps North American manufacturers redesign and build complex electronics closer to end customers rather than relying solely on long Asia-centric supply chains.
"Continued investment and performance in high-value engineering and design services, alongside a record US$4.5b qualified manufacturing funnel that includes growing exposure to data center power, robotics, industrial automation and energy storage, is intended to move Plexus further up the value chain."
What matters most for Plexus now is how a single pressure point ultimately shapes the balance between that higher value work and future profitability.
That trade off is exactly what the full narrative for Plexus unpacks in detail, showing where Plexus could accelerate, where risks cluster and which markets the funnel might be masking.

ATS (TSX:ATS)
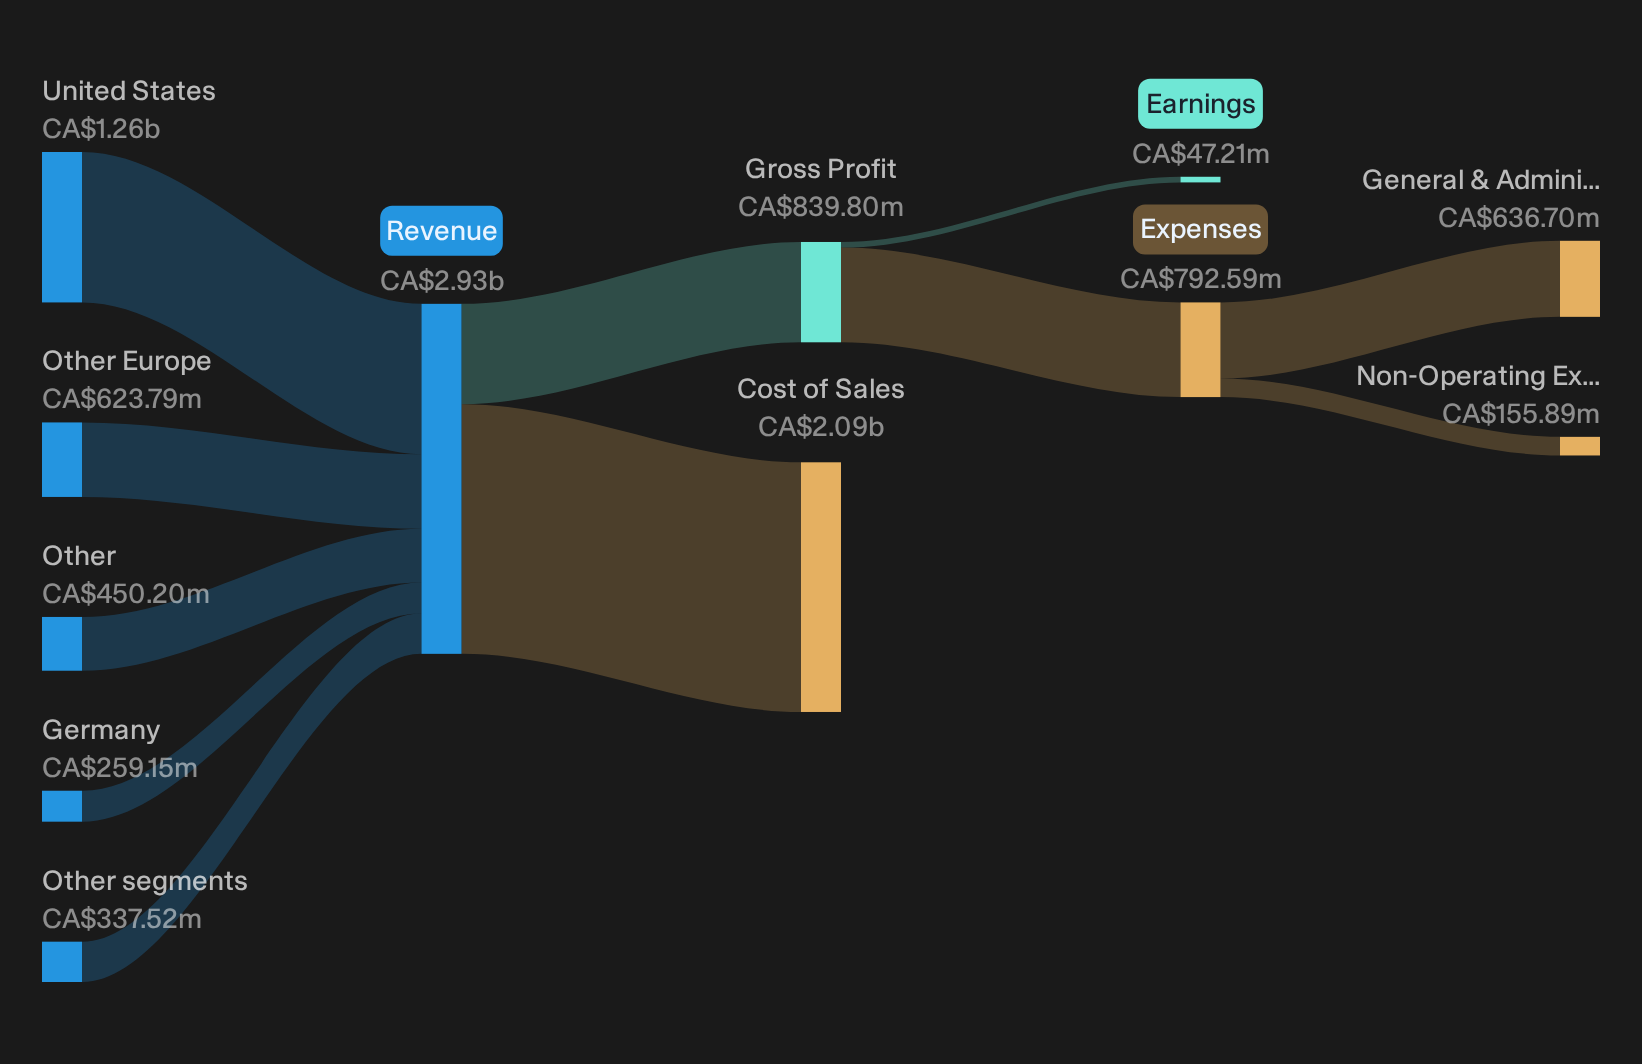
ATS builds the automated factories that many North American manufacturers want as they pull production closer to home. Its Automation Systems unit generates about CA$2.9b in sales and a market value around CA$2.4b anchors it firmly in the mid cap industrial camp.
"Although radiopharmaceutical applications are expanding and ATS is involved in isotope production projects, the high complexity and regulatory intensity of these facilities can slow project awards and ramp up timing."
What really matters for ATS now is how one underappreciated shift in its project mix eventually feeds through to margins and cash flow.
That inflection point is exactly what the full narrative for ATS unpacks in plain English, explaining how ATS could be quietly reshaping its risk reward profile.
Sanmina (SANM)
Sanmina plugs neatly into the onshoring and trade resilient manufacturing theme because it builds and runs complex electronics production and logistics for big-brand customers that want more work done in the Americas. The business generated about US$11.0b from Integrated Manufacturing Solutions and US$1.9b from Components, Products and Services, and the stock is valued at roughly US$11.7b.
Sanmina gives original equipment manufacturers a way to regionalize sensitive electronics programs without losing scale. Its integrated design, manufacturing and logistics network becomes particularly important when trade rules keep changing.
"Sanmina is expanding vertical integration in areas such as metal fabrication for AI racks, high technology PCBs, transformers and liquid cooling and test capabilities. This is intended to capture a larger share of each AI and cloud rack build and support higher gross margin and operating margin over time."
The key variable is how one pressure point on working capital and capacity use ultimately affects the margins investors are monitoring.
That margin swing is exactly what the full narrative for Sanmina unpacks, showing how Sanmina’s AI rack build, capital needs and capacity use could be quietly accelerating value creation.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time momentum headlines hit, early entry points can be gone or dropping fast. Scan under the radar for now and act now.
- Spot potential breakout turnarounds by reviewing the curated 29 high quality undervalued stocks before the crowd notices improving quality and compressing risk.
- Track where real products meet real demand by filtering through the hand picked 91 robotics and automation stocks while industrial automation is still early in its current cycle.
- Position ahead of infrastructure momentum by scanning the focused 43 power grid technology and infrastructure stocks while grid upgrades and electrification stories still feel early stage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com