
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Solaris Energy Infrastructure (SEI) Stock Looks Above Fair Value As Its Five Year Run Continues
Solaris Energy Infrastructure has logged a striking multi‑year share price run, and the question now is whether the current valuation is adequately backed by its earnings power. With the stock recently closing at US$76.40, investors are increasingly asking how much of the story is already embedded in the price.
- Over the past 5 years, Solaris Energy Infrastructure has delivered a very large total return, which puts real pressure on its earnings to justify that kind of share price progress.
- Recent expansion of long term contracts and the acquisition of Global Energy Services Alliance may support more predictable earnings and cash flow, which matters directly for how rich a P/E multiple the market is willing to pay.
- Your read on Solaris Energy Infrastructure is one view; the desks covering it have another. See what analysts think Solaris Energy Infrastructure's shares could be worth.
The stock's next move may depend on whether Solaris Energy Infrastructure's current earnings can support the valuation implied by today's share price.
If you want a broader watchlist of infrastructure and energy names while you assess Solaris Energy Infrastructure's earnings story, a focused screen of 43 power grid technology and infrastructure stocks.
Does Solaris Energy Infrastructure Look Pricey on Earnings?
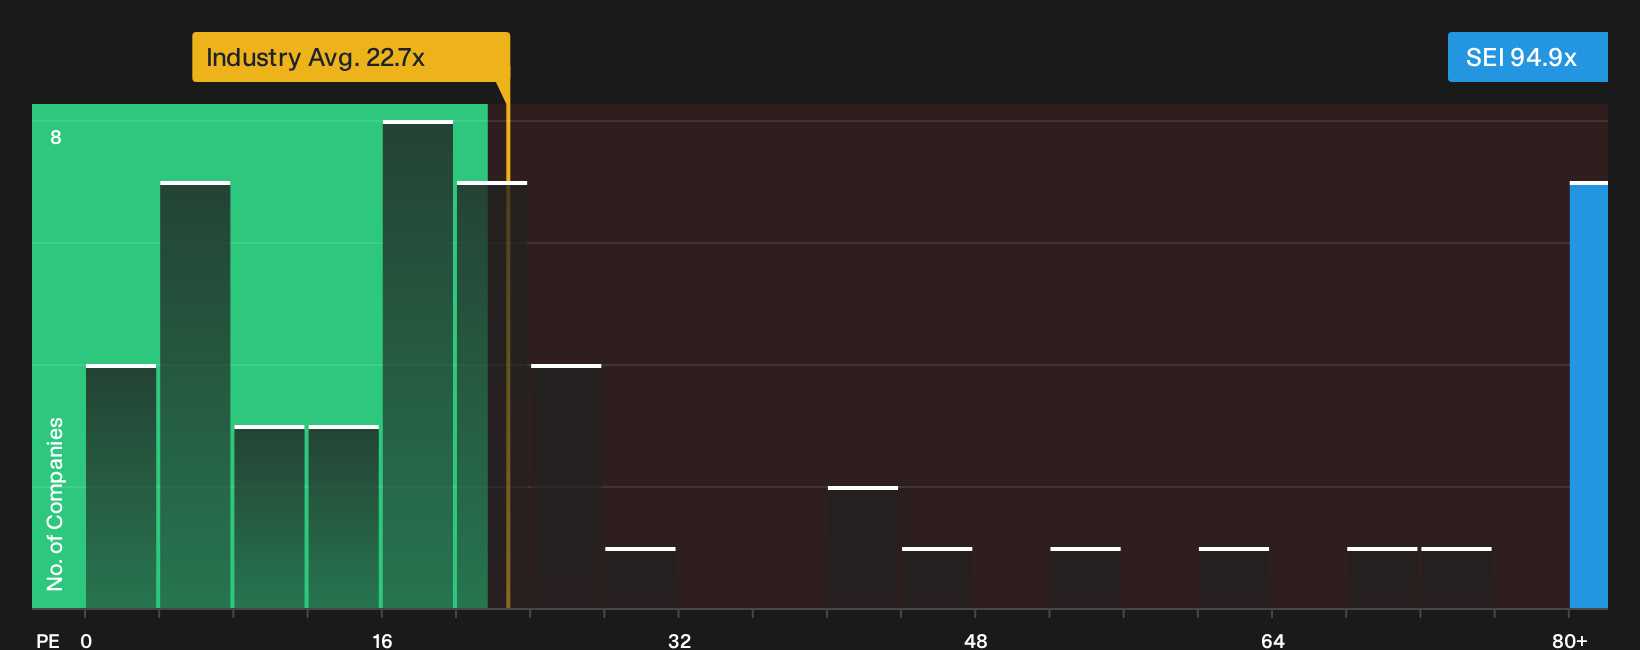
For a contract heavy business like Solaris Energy Infrastructure, the P/E ratio is a natural way to see how much investors are paying for each dollar of profit. At about 94.9x earnings, Solaris trades at a rich premium to the broader Energy Services sector, where the average P/E is roughly 22.7x, and also to closer peers which cluster around 39.1x.
The tailored fair multiple that blends Solaris Energy Infrastructure’s growth profile, margins, size and risk flags sits well below the current P/E. This framework reads the stock as overvalued, and the gap is large enough that the model is effectively flagging how aggressively the market is paying up for the story rather than pointing to a precise fair level. Because the record Q2 2026 results and the Global Energy Services Alliance deal have already pushed expectations higher, anyone buying at this multiple is relying on that earnings narrative to keep delivering. Explore the numbers behind Solaris Energy Infrastructure's P/E valuation.
The Solaris Energy Infrastructure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Solaris Energy Infrastructure valuation puzzle leaves off. They spell out which growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than today’s price on different assumptions. Each narrative treats Solaris Energy Infrastructure's implied fair value as a thesis about the business that you can revisit over time, rather than a one off snapshot, and they sit on Simply Wall St's Community page.
One of the top community narratives on Solaris Energy Infrastructure: 25% undervalued
"Expanding behind the meter power demand from data centers and large energy users, supported by Solaris Energy Infrastructure contracts covering over 2 gigawatts..."
Discover why this Narrative puts Solaris Energy Infrastructure at 25% undervalued.
One more Solaris Energy Infrastructure check that sits beside the price tag
Numbers only tell part of the story for Solaris Energy Infrastructure, since the people steering the business and how their incentives line up with shareholders can pull the whole picture in a very different direction. See who runs Solaris Energy Infrastructure and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com