
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Zebra Technologies Stock's Earnings Momentum Means For Shareholders
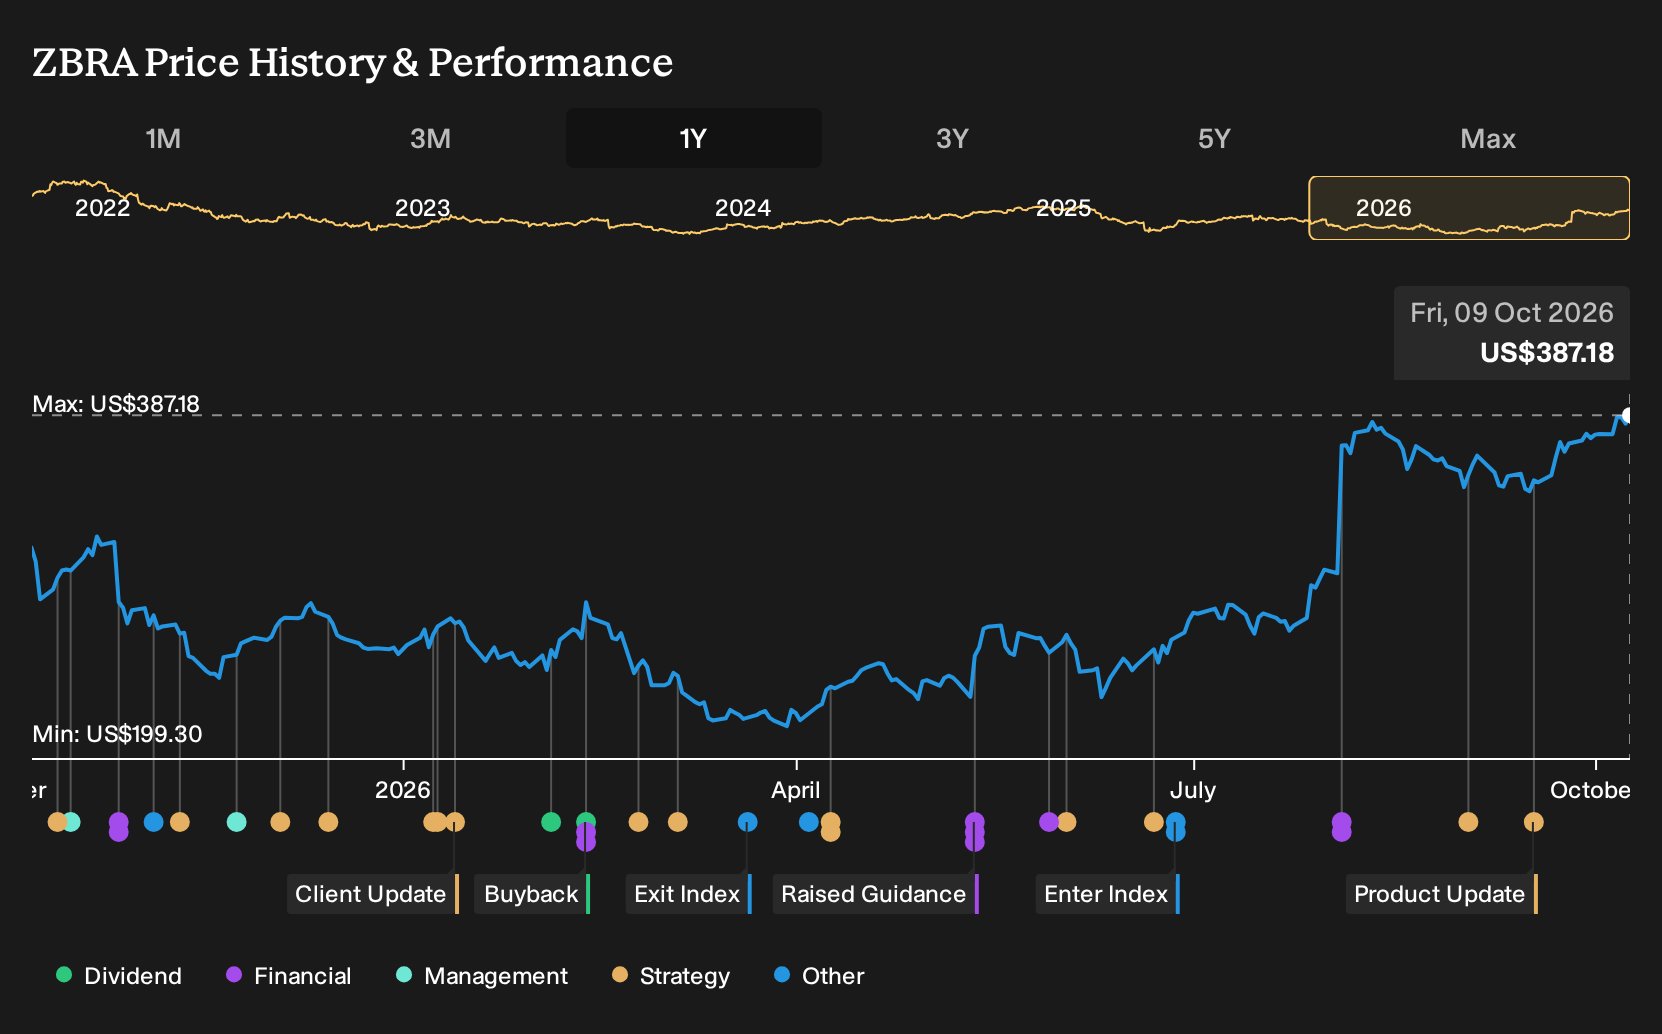
- Zebra Technologies has outperformed the wider Industrial Products sector this year, with the business supported by an 18.9% rise in consensus EPS estimates that highlights stronger earnings momentum tied to demand for its automation and data capture solutions.
- The comparison to Stanley Black & Decker, which also shows improving earnings projections and sector outperformance, points to a wider pattern of investor attention on industrials with clearer earnings trajectories and cost discipline, rather than just cyclical exposure.
- We will explore how Zebra Technologies' earnings momentum within Industrial Products reframes the longer term investment narrative built around automation and digital workflows.
Zebra Technologies Investment Narrative Recap
Zebra Technologies is still a bet on long term growth in automation, data capture, and real time visibility, with most of the heavy lifting coming from hardware, software, and services used in frontline workflows. For you to be comfortable as a shareholder, you need to believe that customers keep prioritizing these upgrades even when budgets get tight.
The recent share price strength and year to date outperformance signal renewed confidence in earnings momentum. That supports the near term catalyst, which is cleaner execution on automation projects after prior softness in regions such as EMEA. The biggest risk remains margin pressure from tariffs, high debt, and more competitive end markets such as point of sale.
With no fresh company specific announcements tied to this move, the most relevant context is still Zebra Technologies' push into customer facing and automation heavy use cases through acquisitions such as Elo Touch Solutions and Photoneo. Those deals extend the product set into kiosks, touchscreens, and machine vision that sit closer to the customer interaction point.
For catalysts, the thesis now depends on Zebra proving it can integrate those assets cleanly, avoid prolonged margin drag, and convert more of the installed base to recurring software and services. The risk is straightforward. If cross selling and SaaS adoption remain slower than expected, earnings could be more volatile than the recent share price recovery implies.
Zebra Technologies' current analyst narrative points to revenues of US$7.2b and earnings of US$999.2m by 2029. That profile is based on 7.0% yearly revenue growth and an earnings increase of about US$460m from current earnings of US$539.0m.
Uncover why Zebra Technologies' fair value indicates a 6% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts frame a different catalyst for Zebra Technologies. They focus on the potential for mid 20s EBITDA margins and at least US$1.1b in 2026 free cash flow, compared with consensus earnings of US$999.2m by 2029. Those views were set before this latest news, so opinions may shift as fresh information is released.
Explore 4 other Zebra Technologies fair value estimates, including one that suggests potential upside of up to 40% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zebra Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zebra Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zebra Technologies' overall financial health at a glance.
Looking for more Zebra Technologies style ideas?
If the Zebra Technologies setup appeals to you, it can be useful to line it up against other opportunities that share similar qualities on earnings, balance sheet strength, or income potential. The Simply Wall St Screener helps you filter that broader universe into a manageable shortlist.
- If you care most about quality at a sensible entry point, scan a curated 29 high quality undervalued stocks that combine strong fundamentals with prices that analysts see as out of step with underlying performance.
- If capital preservation is higher on your list, focus on a 31 resilient stocks with low risk scores where balance sheets, earnings stability, and risk scores are built to handle tougher conditions.
- If you want sturdier finances backing your ideas, concentrate on a list of solid balance sheet and fundamentals (25 results) that pair cleaner leverage profiles with stronger core business metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com