
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Wüstenrot & Württembergische (XTRA:WUW) Leaves The SDAX, Is The Valuation Discount Enough?
Wüstenrot & Württembergische (XTRA:WUW) has just been removed from the Germany SDAX Total Return Index, an index change that can reshape trading flows and prompt investors to reassess the stock’s role in portfolios.
Recent trading has been soft. The 30 day share price return is down 7.56% and the 90 day move is down 11.53%, while the 1 year total shareholder return has slipped 5.46%. This suggests momentum had already faded before Wüstenrot & Württembergische left the SDAX and that some investors may be reassessing both growth potential and risk after a 3 year total shareholder return of 5.32%.
Scan beyond Wüstenrot & Württembergische and compare this index exit with other insurers and financials that still show up in our 179 high quality undervalued stocks for potential value setups.
After the index exit and recent share price slide, the real tension is simple: Do current levels in Wüstenrot & Württembergische still offer enough upside potential to justify the risks on the table?
Preferred P/E of 9.2x: Is it justified?
On simple earnings terms, Wüstenrot & Württembergische looks inexpensive. The shares last closed at €13.20 and the stock trades on a P/E of 9.2x, which is low compared to both the wider German market and many listed insurance peers.
The P/E ratio links what investors are paying today to the company’s current earnings. For an insurer like Wüstenrot & Württembergische, it gives a quick read on how the market is pricing underwriting results, investment income and fee based business relative to profits the group already generates.
Here, the valuation signal is clear. Management is forecast to grow earnings by 15.5% per year, which is ahead of the German market forecast of 14.6% growth. Yet the P/E of 9.2x is below the German market level of 15.7x and well below the peer average of 38.6x. The firm also screens as good value against the European Insurance industry average multiple of 12.2x, which suggests the current rating could move closer to a higher level if those profit expectations are met.
On top of that, Simply Wall St’s fair P/E estimate sits at 12.3x. The current 9.2x ratio therefore implies the market is assigning a clear discount relative to where the valuation model suggests the multiple could be over time.
Explore the SWS fair ratio for Wüstenrot & Württembergische.
Result: Price-to-earnings of 9.2x (UNDERVALUED)
Still, you need to watch two pressure points: the SDAX exit that can sap liquidity, and any setback in net income after the recent 15.5% growth rate.
Find out about the key risks to this Wüstenrot & Württembergische narrative.
Another view on Wüstenrot & Württembergische’s value
The SWS DCF model paints a very different picture. On this approach, Wüstenrot & Württembergische at €13.20 trades above an estimated future cash flow value of €8.10, which screens as overvalued. That gap raises a simple question: Are reported earnings flattering a weaker cash flow story?
For a closer look at how that cash flow estimate is built and where the key inputs sit, Look into how the SWS DCF model arrives at its fair value.
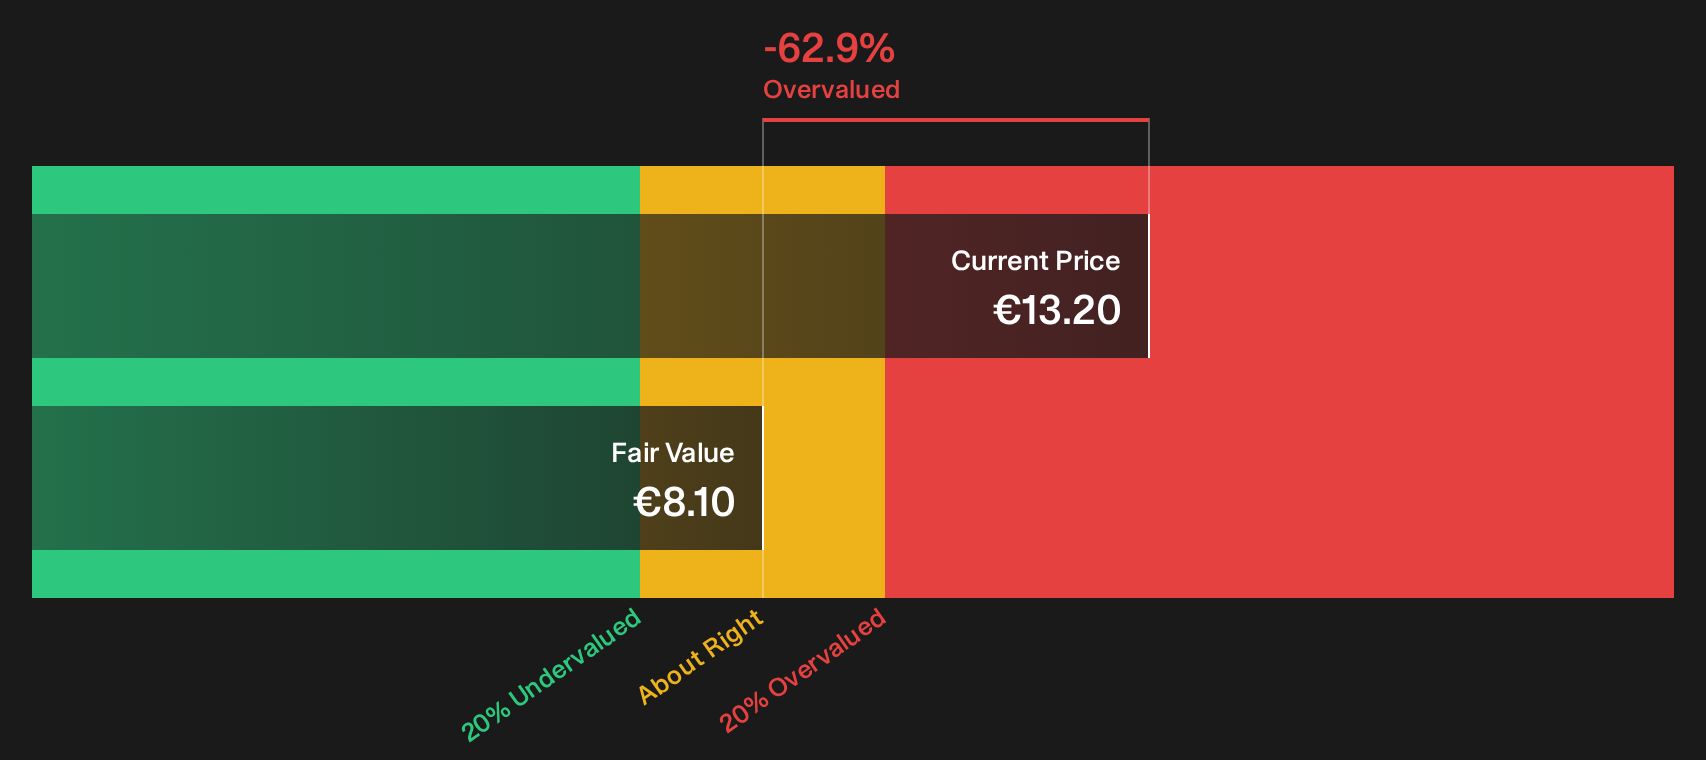
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wüstenrot & Württembergische for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment across Wüstenrot & Württembergische is mixed, so move quickly, review the full data set and stress test your own thesis against the 4 key rewards.
Looking for more investment ideas beyond Wüstenrot & Württembergische?
If Wüstenrot & Württembergische no longer feels like a perfect fit on its own, you can broaden your opportunity set with a focused screen across other high quality listed businesses.
- Target rock solid balance sheets and steadier risk profiles by scanning our 226 resilient stocks with low risk scores for candidates that may hold up better when conditions turn choppy.
- Hunt for quality at a discount by using the 179 high quality undervalued stocks to surface companies where fundamentals and current pricing appear out of sync.
- Spot potential future leaders early by running the 619 high quality undiscovered gems and flagging smaller businesses that already show strong financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com