
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Xero (ASX:XRO) Adds Mark Durcan To Its Board, Is The Upside Already Priced In?
Why Mark Durcan’s Appointment Matters For Xero
Xero (ASX:XRO) just reshaped its board, bringing in former Micron Technology chief Mark Durcan as an independent Non Executive Director following Anjali Joshi’s retirement at the 2026 Annual Meeting.
Durcan’s background spans more than three decades at Micron, current board roles at ASML and Cencora, and governance experience at Rice University, which gives Xero shareholders a fresh lens on technology, capital allocation, and global scale.
Against that boardroom backdrop, Xero’s share price has been under clear pressure, with the stock at A$61.49 after a 1 day share price return of 2.81% and a 7 day share price return of 8.81%. However, the year to date share price return is down 45.22% and the 1 year total shareholder return is down 60.02%, which points to recent momentum improving after a tough run as investors reassess both growth potential and execution risk around changes such as Durcan’s appointment.
Spot opportunities beyond Xero by scanning a curated 15 high quality undiscovered gems with strong fundamentals that could be next in line for board level catalysts or renewed market attention.Bulls point to double digit revenue and net income growth alongside a steep share price fall. Bears focus on execution risk and a weak value score. Which side do the current valuation markers support next?
Most Popular Narrative: 54% Undervalued
At A$61.49, the most followed narrative on Xero pegs fair value at A$133.38, which frames the current share price as heavily discounted against that view and sets up a very different story to the recent drawdown.
Concerns over the quality and moats of SaaS businesses in the face of new AI threats will pressure Xero to demonstrate greater near term profitability, even if that sacrifices some long term growth ambition. This change will likely benefit Xero more than its current competitors. As the Warren Buffett quote says, "Only when the tide goes out do you discover who's been swimming naked". The pressure of AI means every SaaS company has to prove the very high P/E ratios attached to them are worthwhile. Xero has healthy revenue growth, healthy margins and healthy cashflows. Having the opportunity to demonstrate this over its shakier SaaS rivals should boost Xero in the long run.
See why 24 investors see Xero as 54% undervalued.
According to KiwiInvest, that A$133.38 narrative fair value builds on expectations of increasing subscriber numbers, higher average revenue per user, and scalable software economics that could support stronger net profit margins over time. The narrative also leans on Xero's current gross margin profile and views AI more as an efficiency tool for product rollout than an existential threat, which helps explain why it points to a large gap between the modelled fair value and the live market price.
Result: Fair Value of A$133.38 (UNDERVALUED)
Still, the KiwiInvest narrative could be knocked off course if AI tools erode Xero's pricing power, or if trust issues emerge around accuracy and uptime.
Find out about the key risks to this Xero narrative.
Another View On Xero’s Valuation
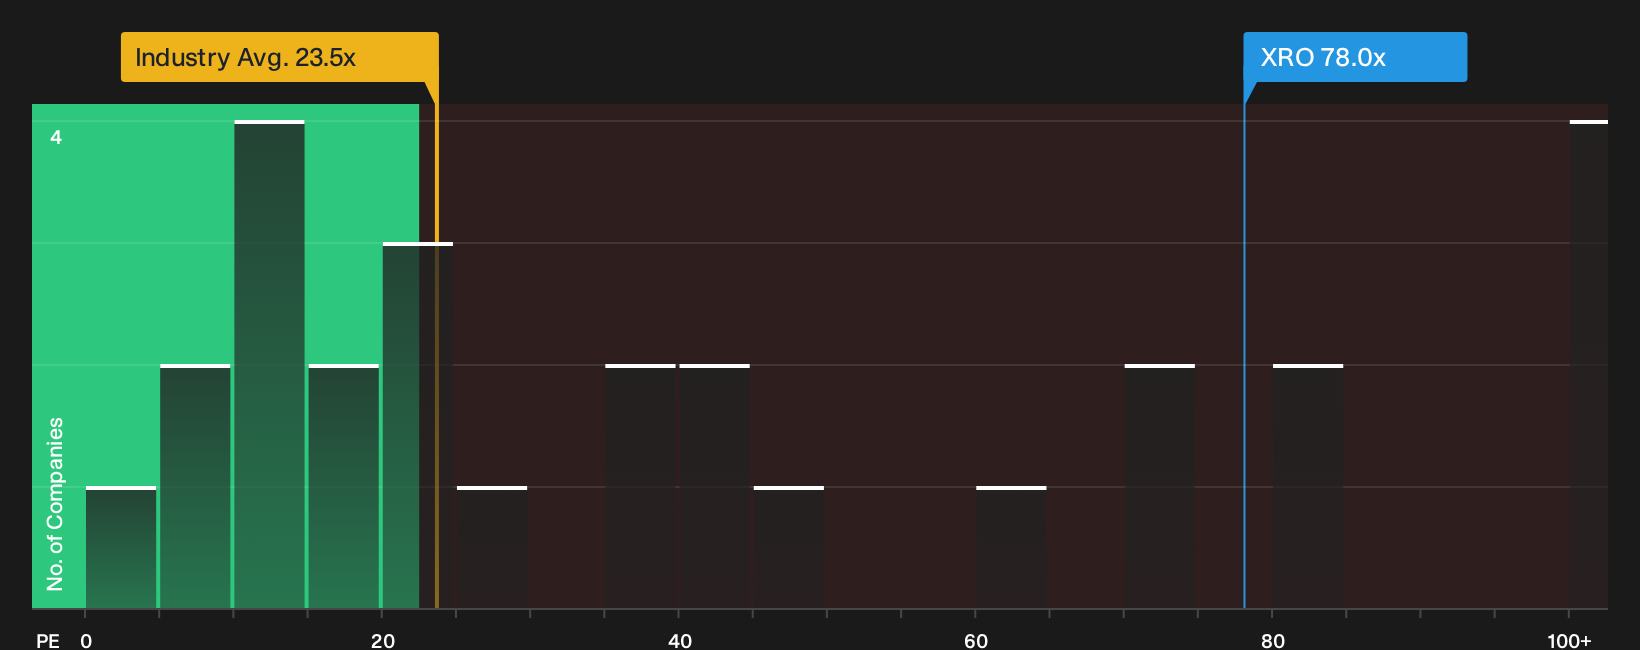
That A$133.38 narrative fair value leans on strong growth assumptions, yet the market is still paying a rich P/E of 78x for Xero compared with 38.2x for peers and a fair ratio of 44.4x. That kind of premium raises a simple question for you: Is the upside story already in the price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and worry on Xero feels familiar, treat it as a cue to move quickly, study the data in detail, and weigh up the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Xero?
You have seen how quickly sentiment around Xero can shift, so do not stop here. Use focused stock lists to spot your next move before the crowd.
- Target resilient compounding potential by scanning a curated pool of quality candidates in the 4 high quality undervalued stocks.
- Prioritise capital protection and focus on sturdier balance sheets by filtering for candidates in the 7 resilient stocks with low risk scores.
- Stay early on tomorrow's potential standouts by combing through a focused set of under-the-radar opportunities in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com