
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 Australian Value Stocks To Watch In October 2026
Global markets are reacting to central bank moves and trade negotiations, and many Australian shares tied closely to earnings expectations or rate sensitivities are seeing big swings. That kind of noise can leave cash rich businesses with solid future cash flow potential trading at a discount. This article highlights three Australian stocks that our cash flow focused valuation tool flags as underpriced and explains why patient, value oriented investors are watching.
The three stocks below are just a starting sample, and the full screen surfaced 5 more Australian businesses with similarly cash rich profiles and valuation gaps that are not covered here. To identify and analyze your own highest conviction ideas from this universe, head straight into the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper miner whose Havieron project in Western Australia underpins its future cash flow potential.
Operations: The business currently reports A$2.26b of revenue from its Telfer Havieron segment, with sales mainly into China and wider Asia.
Market Cap: A$6.80b
Greatland Resources matters for a cash flow focused screen because Havieron is shifting the story from pure exploration potential to real operating income.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
The real swing factor is how one less visible pressure ultimately shapes the long term cash conversion that underpins those projections.
That hidden pressure is exactly what the full narrative for Greatland Resources tackles, mapping how it could accelerate or stall Greatland Resources’ cash engine beyond the gold price story.
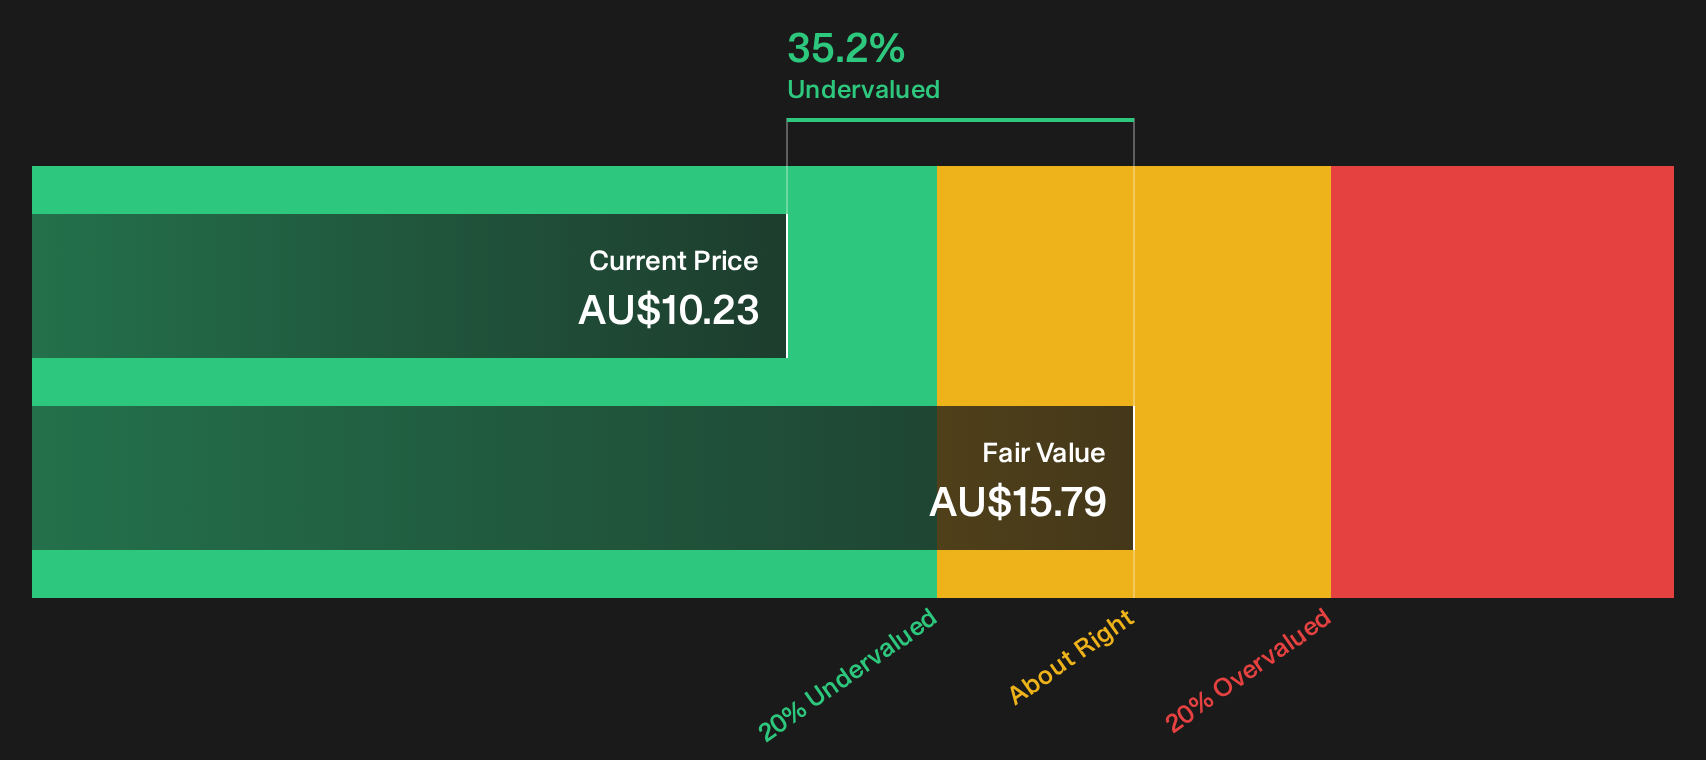
Ansell (ASX:ANN)
Overview: Ansell is a global supplier of hand and body protection, with healthcare examination and surgical gloves providing recurring, cash generative demand.
Operations: Ansell earns US$1.19b from Healthcare and US$947.3 million from Industrial, with meaningful exposure to North America and Europe.
Market Cap: A$6.26b
Ansell matters for this cash flow focused list because its healthcare glove lines resemble a utility style consumable, where consistent usage gives investors clearer visibility on future cash generation that can be plugged into discounted cash flow models.
"Ansell has established a defensible niche as a premium B2B specialist in hand and body protection, commanding roughly 20% global market share in both surgical and mechanical gloves and ranking #1 or #2 across its key verticals."
The real tension for Ansell now sits in how one quiet shift in cost discipline and pricing power ultimately shapes margin resilience.
That quiet shift is exactly what the full narrative for Ansell unpacks, showing how pricing power, cost discipline and demand cycles could be decoupling to reshape Ansell’s cash story.

Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a Perth based producer of LNG and other hydrocarbons, generating cash flows from large offshore and onshore projects.
Operations: Woodside earns about $7.29b from Australia, $4.62b from International operations and $1.93b from its Marketing segment.
Market Cap: A$61.44b
Woodside Energy Group taps directly into the screener theme because its LNG and upstream hydrocarbon projects convert long term contracts into tangible cash flows that discounted cash flow models can assess with more clarity than many shorter cycle businesses.
"Investor optimism appears driven by robust expectations for long-term demand growth in Asian and emerging markets, with Woodside's global LNG expansion (Louisiana, Scarborough) positioned to capture this growth; however, these assumptions may underestimate the potential for rapid decarbonization policies or renewable adoption, risking future revenue and volume growth if LNG demand softens in key markets."
What ultimately matters for investors is how one shift in future policy and customer demand shapes the pricing power behind those LNG cash flows.
That policy and demand crosscurrent is exactly what the full narrative for Woodside Energy Group unpacks, showing where Woodside Energy Group’s LNG engine could be accelerating or quietly stalling next.

Seeking Alternatives Before The Crowd?
Fresh opportunities do not wait. Breakout momentum, quietly dropping valuations and under the radar for now information all decay fast. Scan these ideas while it matters and consider them while they are still relevant.
- Spot potential turnaround stories with solid finances by running the list of solid balance sheet and fundamentals (12 results) and see which companies still trade as if the last cycle never ended.
- Track early dividend momentum and assess which established payers in the 5 dividend fortresses might be pricing in less stability than their balance sheets suggest.
- Target potential structural beneficiaries of AI infrastructure demand using the curated 92 AI infrastructure stocks and filter for businesses where cash flows can support continued expansion.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com