
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Taiwan Semiconductor Manufacturing (TSM) Nears Record Profit, Is The Stock Above Fair Value?
Taiwan Semiconductor Manufacturing (NYSE:TSM) heads into its third quarter 2026 earnings release with expectations for a sixth straight record profit, driven by already reported record quarterly revenue that exceeded earlier guidance.
Over the past year, Taiwan Semiconductor Manufacturing has seen strong momentum, with the latest share price at US$453.31 and a year to date share price return of 41.83%. The 1 year total shareholder return of 50.88% and very large 3 year total shareholder return of more than 4x suggest investors have been pricing in both AI driven demand and higher perceived execution risk as the business expands capacity and ramps new technologies.
Compare Taiwan Semiconductor Manufacturing's AI driven momentum with a curated group of infrastructure plays by scanning the 92 AI infrastructure stocks that are powering data center demand.
Bulls see Taiwan Semiconductor Manufacturing as the indispensable AI foundry, while bears see a cyclical heavyweight priced for perfection. Which case lines up more closely with today’s earnings setup and valuation?
Most Popular Narrative: 20% Overvalued
Taiwan Semiconductor Manufacturing closed at $453.31, while the most followed narrative fair value sits at $378.29. This frames today’s earnings excitement against a richer price tag than that narrative supports.
Here is the exercise that settles most arguments. Instead of asking what TSMC is worth, invert. Ask what has to happen for $417.52 to be the right price.
Run the machine backwards and the answer is a 13.2% compound annual revenue growth rate for ten consecutive years, on a path where margins fade from today's records as management says they will. Strip out inflation and that is roughly 10.7% real growth, every year, for a decade, from a company already doing $171 billion of revenue.
See why 125 investors see Taiwan Semiconductor Manufacturing as 20% overvalued.
Result: Fair Value of $378.29 (OVERVALUED)
Still, Taiwan Semiconductor Manufacturing’s story can break if geopolitical risk in the Taiwan Strait flares or if key customers materially shift high end orders elsewhere.
Find out about the key risks to this Taiwan Semiconductor Manufacturing narrative.
Another Look At Taiwan Semiconductor Manufacturing Using Earnings Multiples
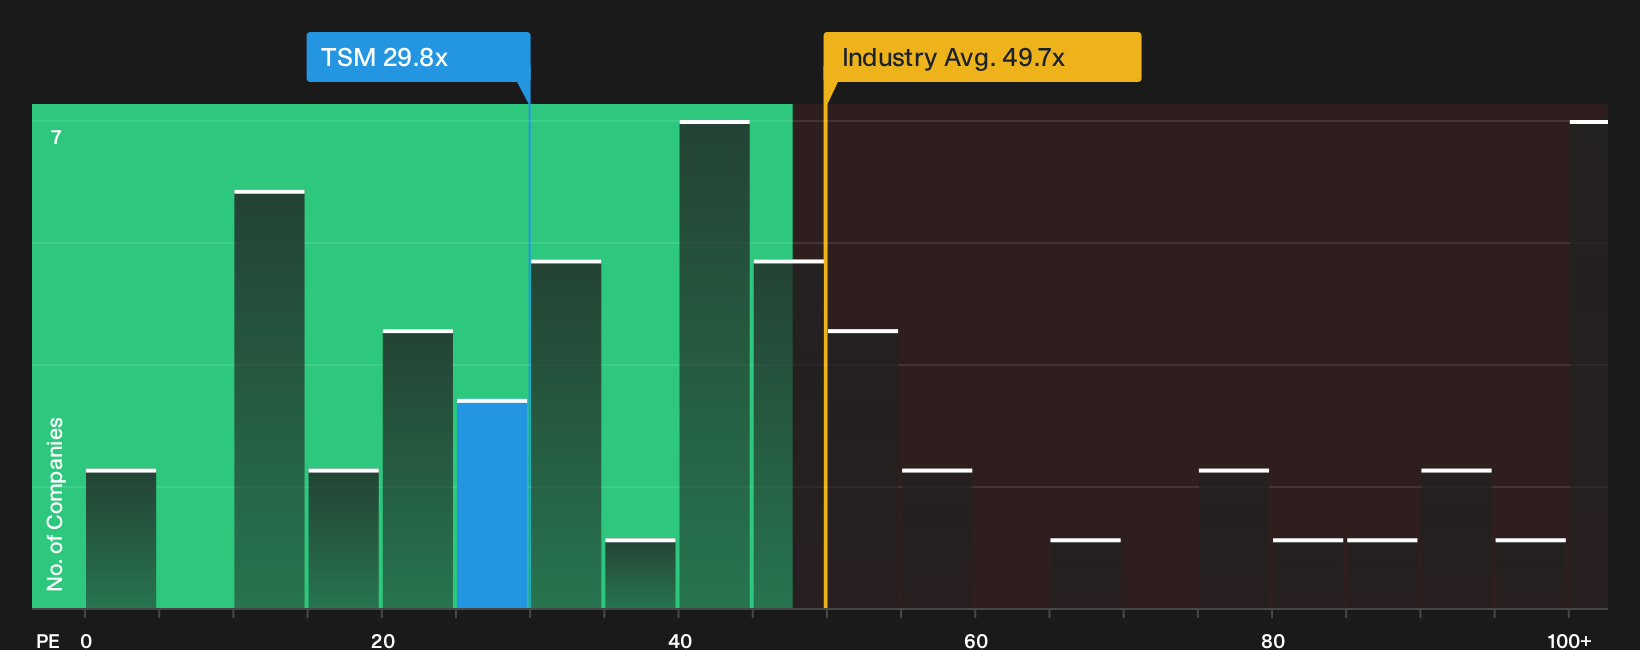
On raw numbers, Taiwan Semiconductor Manufacturing trades on a P/E of 29.8x. That is far below the US Semiconductor group at 49.7x and also under the peer average of 60.2x. The fair ratio sits at 42.6x, which suggests investors currently pay a lower earnings multiple than the market could move toward over time. Does that gap represent a valuation cushion, or a signal that the market is already adjusting for quality, cyclicality, and risk?
To see how this earnings-based view lines up against the AI hype and geopolitical overhang, take a look at our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and concern feels familiar, move quickly from headlines to hard numbers and form your own view using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Taiwan Semiconductor Manufacturing?
If Taiwan Semiconductor Manufacturing has you thinking more broadly about your portfolio, now is the moment to scan fresh ideas before the market moves without you.
- Target stability first and stress test your portfolio against shocks by running the 31 resilient stocks with low risk scores, which focuses on resilient businesses.
- Hunt for mispriced quality and compare your watchlist against the 29 high quality undervalued stocks, which filters for robust cash flows and solid fundamentals.
- Spot tomorrow’s quiet leaders early by checking the 20 high quality undiscovered gems, which highlights lesser known companies with strong financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com