
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Groupe Dynamite Heads 3 Canadian Value Stocks To Watch
Central banks are signaling that interest rates may need more frequent tweaks to keep inflation in check, which puts cash generation under the spotlight for Canadian companies. Reliable cash flows can help a business handle pricier debt and stickier costs, yet some are still priced as if that strength does not matter. This article walks through three Canadian stocks where current prices lag their underlying cash potential.
The three stocks ahead are just a sample set, and the full screen surfaces 9 more businesses with equally compelling cash flow stories that are not covered here.
To sort through that broader group on your own terms, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, compare, and analyze the highest conviction ideas for your watchlist.
Groupe Dynamite (TSX:GRGD)
Groupe Dynamite is a women’s fashion retailer built around its Dynamite and Garage brands. Recurring store and e-commerce sales are central to the cash flow story that places it squarely in this undervalued cash flow screener.
Groupe Dynamite generates about CA$1.49b from retail apparel across its banners, and with a market value near CA$6.56b, it is a sizable player in North American and UK women’s fashion tied closely to recurring store and online demand.
"Rapid expansion in the United States and early traction in the United Kingdom, including Oxford Street and other prime centers, positions Groupe Dynamite to reach more higher income shoppers and tourists, which can support sustained revenue growth and higher sales per square foot."
For investors focused on cash flows, one unresolved pressure on future margins may matter more than any of the current growth headlines.
Those margin questions are exactly what the full narrative for Groupe Dynamite unpacks. It lays out how Groupe Dynamite’s cash engine, growth ambitions, and risks could be decoupling from today’s pricing.

Pan American Silver (TSX:PAAS)
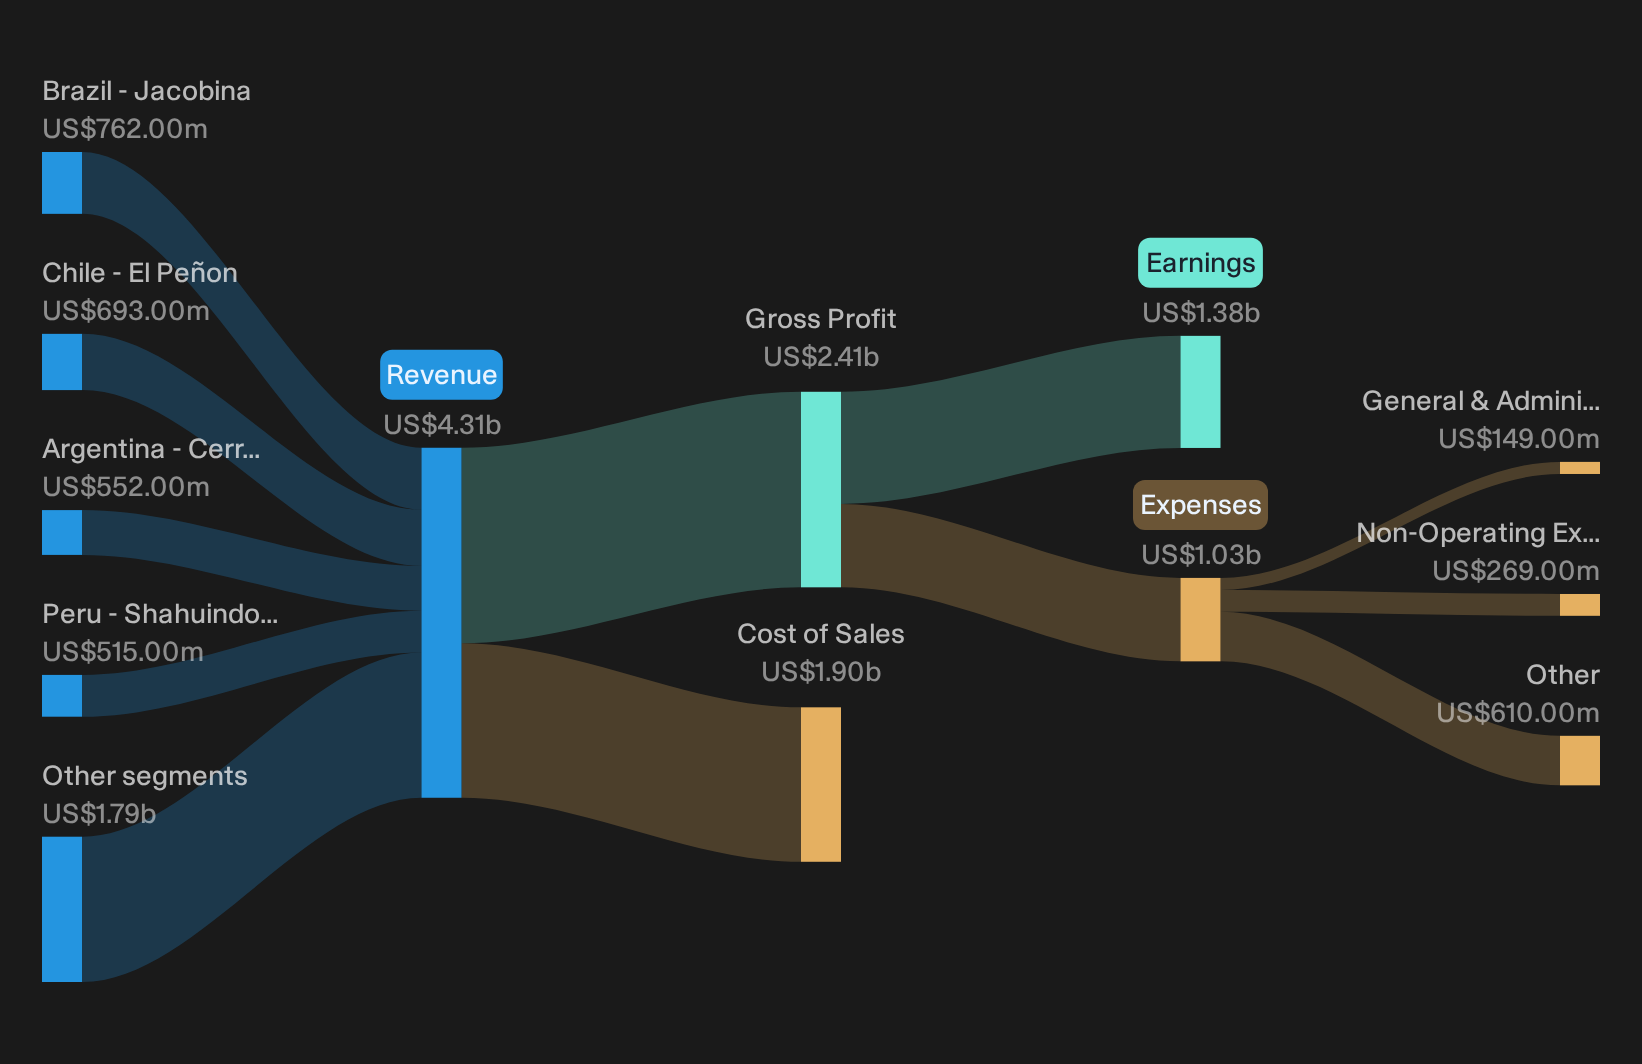
Pan American Silver runs a portfolio of silver and gold mines across the Americas, where cash generation from assets like La Colorada, Juanicipio and Cerro Moro anchors its role in this cash flow focused screener. Operations span Peru, Canada, Mexico, Brazil, Chile, Argentina and Bolivia. Brazil’s Jacobina mine produced about US$762 million in revenue, Chile’s El Peñon US$693 million, Peru’s Shahuindo US$515 million and Argentina’s Cerro Moro US$552 million, contributing to a business valued at roughly CA$27.5b.
Pan American Silver ties the screener theme directly to on the ground production, where a handful of high quality silver assets have outsized influence on future cash generation.
"Integration of Juanicipio, a very low cost high grade silver mine, is rapidly scaling attributable production while structurally lowering silver segment all in sustaining costs, supporting higher operating margins and free cash flow."
One question for investors is what happens if a less visible constraint on those margins does not move in the company’s favor over the next few years.
If that pressure on margins is what you keep circling back to, the full narrative for Pan American Silver shows how Pan American Silver’s cost profile and growth options might intersect.
SSR Mining (TSX:SSRM)
SSR Mining links directly into this cash flow focused screen through its producing gold and silver operations, where working mines and recent acquisitions feed the discounted cash flow story rather than distant exploration hopes.
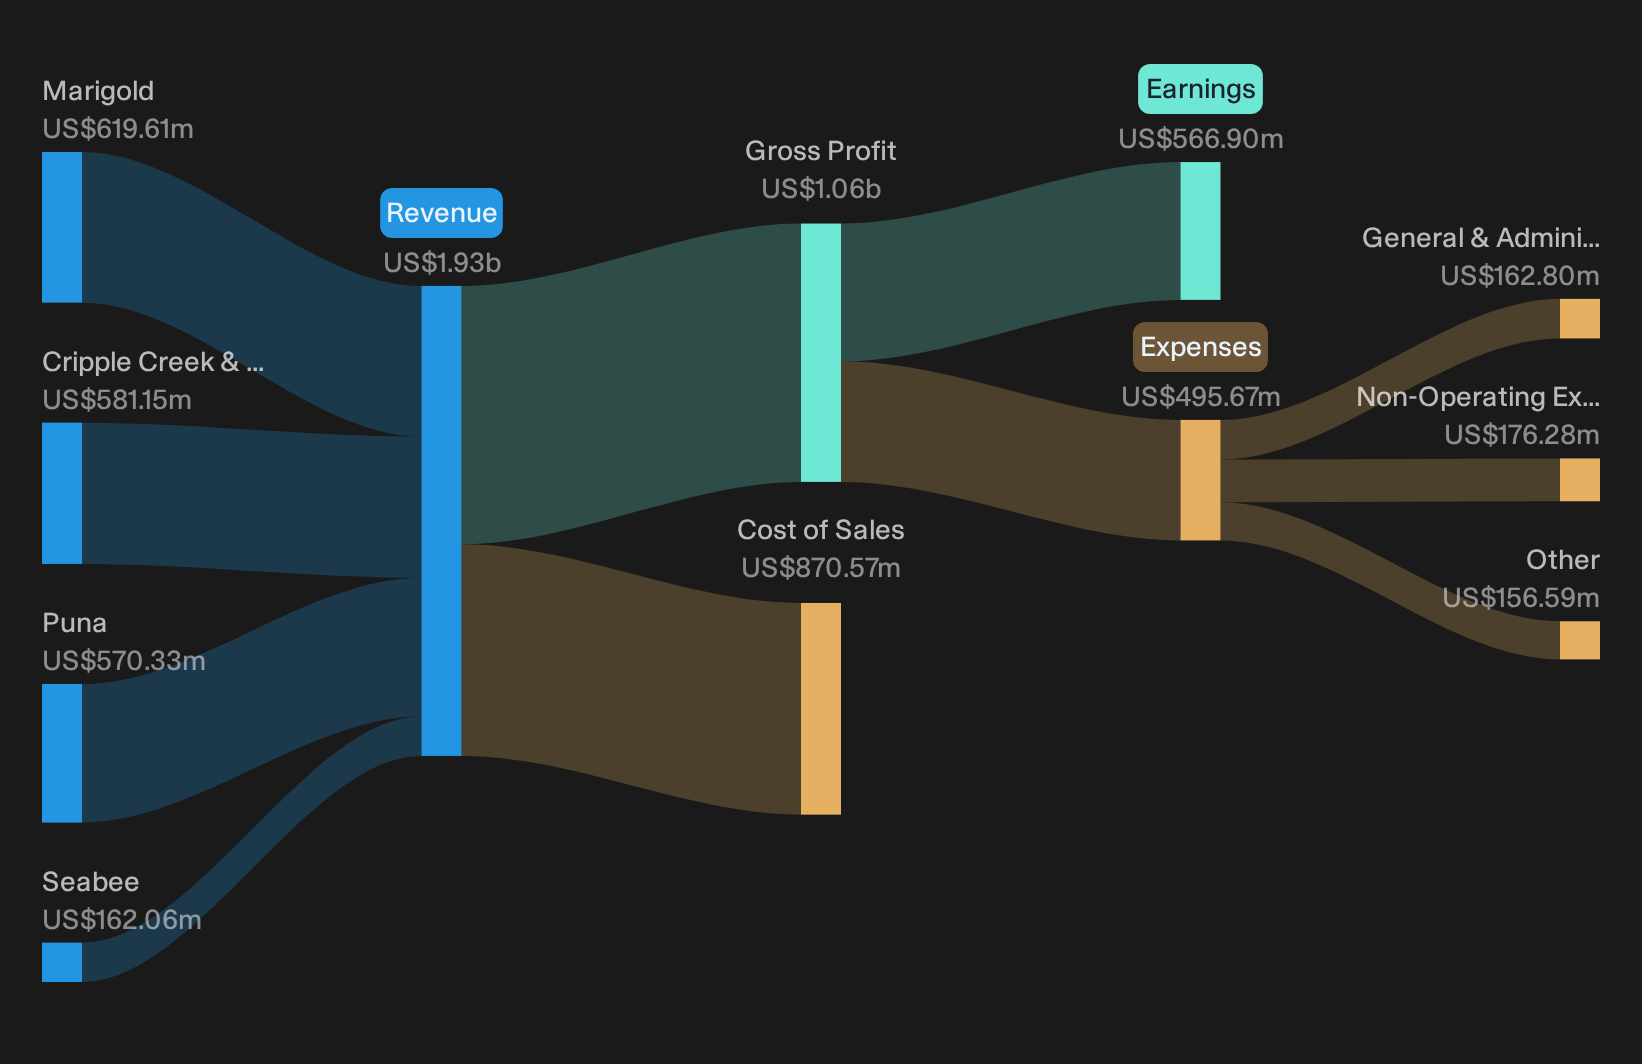
SSR Mining operates producing gold and silver mines that underpin the screener’s cash flow theme, with revenue anchored by Marigold at about US$620 million, Cripple Creek & Victor around US$581 million, Puna near US$570 million and Seabee roughly US$162 million, and a market value close to CA$10.3b.
"With a fortress balance sheet and strong ongoing free cash flow, SSR Mining has the scale and optionality to pursue capital allocation strategies, including opportunistic buybacks and further targeted acquisitions, at a time when industry consolidation and project scarcity favor well-capitalized mid-tier players, supporting future per-share earnings expansion and value creation not yet reflected in the stock price."
The real test for that cash flow story comes if a single cost and margin assumption inside those producing mines shifts more than investors currently expect.
If that single assumption is what you keep replaying, the full narrative for SSR Mining explains where SSR Mining’s cash engine could accelerate or stall next.
Seeking Fresh Alternatives Before They Fly
Markets move fast and fresh ideas do not stay under the radar for long. Catch potential breakouts, renewed momentum, and dropping entry points while it still matters and consider taking action in a timely way.
- Spot income workhorses early and scan the 3 dividend fortresses that can help support a portfolio when yields matter more than story stocks.
- Track where capital intensity meets long term demand and review the 43 power grid technology and infrastructure stocks before infrastructure momentum gets fully priced in.
- Explore secular shifts in automation and sift through the 91 robotics and automation stocks while the strongest balance sheets and cash generators may still be mispriced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com