
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To L'Oréal (ENXTPA:OR) Football Club Partnership
- L'Oréal Groupe has partnered with Paris Saint-Germain as official beauty partner through 2028, initially activating the deal via Vichy Laboratoires as the club's official skincare and haircare partner.
- The PSG tie-up gives L'Oréal a new route into sports fans and wellness focused consumers, aligning dermatological brands like Vichy with performance, recovery, and everyday care.
- Next, the focus shifts to how L'Oréal's PSG partnership could influence the broader investment narrative around marketing reach and brand positioning.
L'Oréal Investment Narrative Recap
An investor in L'Oréal needs to believe that global beauty demand, online adoption, and premium skincare can keep supporting mid single digit revenue expansion and steady earnings growth. The PSG agreement sits within existing marketing spend, so the short term catalyst still looks tied to execution in emerging regions and e commerce rather than this sponsorship alone.
The biggest near term risk remains competition from digital native and local brands in skincare and makeup, especially in North Asia and China, which could pressure volumes and pricing. Higher advertising needs and any FX or tariff shocks could also lean on margins, particularly if new launches or campaigns fail to pull their weight.
With no fresh company announcements disclosed alongside the PSG news, the most relevant reference point for this sponsorship is L'Oréal's stated focus on dermatological beauty and wellness aligned brands. Vichy fits that profile and already sits in a segment that benefits from consumer interest in health linked skincare.
For catalysts, the key question is how well management converts this kind of partnership into incremental demand across online channels and emerging markets, where double digit sales growth has been a focus. Execution risk sits in balancing heavier brand investments with cost discipline so operating margins do not come under unnecessary pressure.
L'Oréal's consensus narrative points to €54.5b in revenue and €8.9b in earnings by 2029. That profile lines up with analysts factoring in 6.3% yearly revenue growth and an earnings increase of about €2.6b from the current €6.3b level.
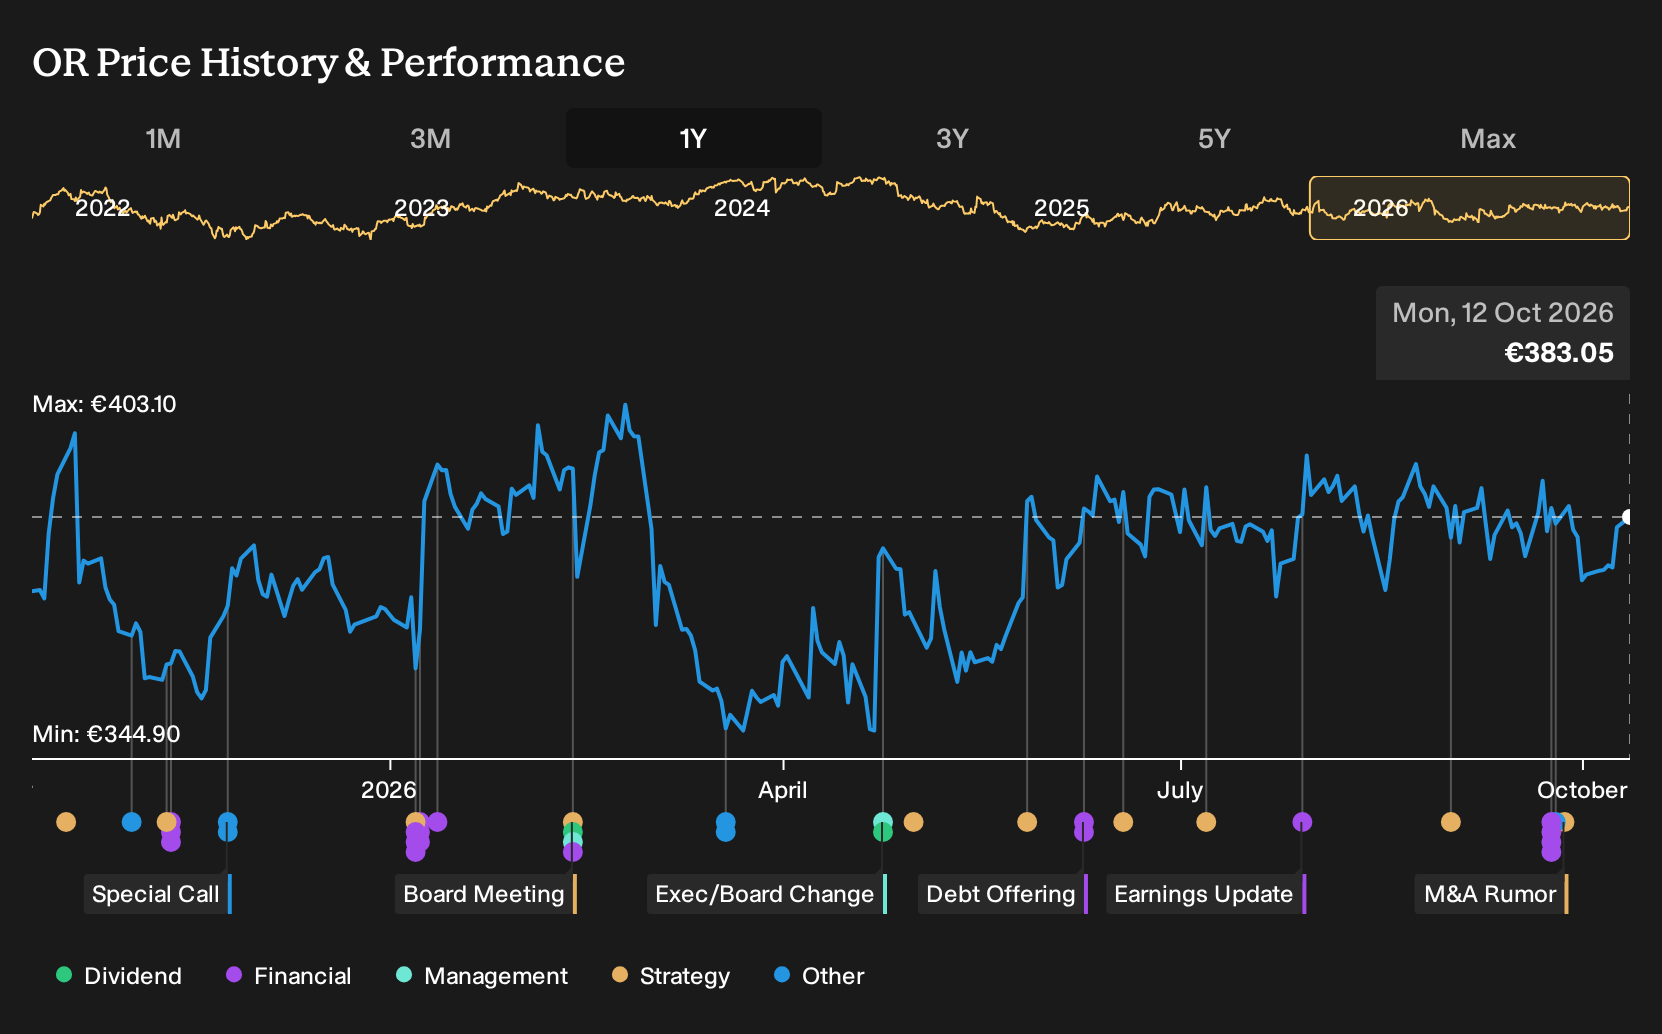
Uncover why L'Oréal's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value estimates for L'Oréal, clustered in a tight €417 to €438 band, so you are seeing a narrow but still divergent view of upside. Set those against risks around competition, FX, and higher advertising, and the spread in opinion becomes a useful prompt to examine multiple angles before acting.
Explore another L'Oréal fair value estimate, including one that suggests potential upside of as much as 14% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your L'Oréal research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for L'Oréal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate L'Oréal's overall financial health at a glance.
Looking For More Investment Ideas Beyond L'Oréal?
If the L'Oréal story has sharpened your thinking about brand strength and financial quality, it can be useful to widen the lens and scan other businesses that share some of those traits. The Simply Wall St Screener can help you quickly filter for different types of opportunities that match your style and risk tolerance.
- If you care most about value and fundamentals, use the 179 high quality undervalued stocks that aims to surface companies combining quality metrics with potentially attractive pricing.
- For a focus on resilience and balance sheet strength, scan the list of solid balance sheet and fundamentals (202 results) to find businesses with sturdier finances and more room to handle shocks.
- To keep risk in check while still hunting for returns, filter the market with the 226 resilient stocks with low risk scores and narrow in on stocks with lower overall risk scores aligned with your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com