
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Following DISA App Launch, Is Everforth (EFOR) Now Fully Valued?
Everforth (EFOR) is back in focus after DISA Global Solutions released a Workday based pre employment screening app built with Everforth’s TopBloc unit, tying HR compliance checks directly into Workday Recruiting workflows.
That launch lands at a time when Everforth’s 1 month share price return of 19.16% and 90 day share price return of 119.17% point to strong short term momentum, even though the year to date share price return is down 19.63% and the 5 year total shareholder return has fallen 68.37%.
Scan for other HR and IT services stocks showing similar momentum and product catalysts to Everforth through our curated list of 20 high quality undiscovered gems.
Everforth has a real business story in IT services and federal work, plus a fresh Workday tied product spark, yet the shares have already sprinted higher. Is that underlying quality still on sale or now fully paid for?
Most Popular Narrative: 36% Overvalued
Everforth closed at $37.50, while the most followed narrative anchors fair value at $27.50 using a 12.42% discount rate and detailed long term cash flow work. That gap frames the current rally as pricing in a lot of execution on AI, consulting and federal contracts before it actually shows up in the numbers.
The current valuation implies Everforth’s share price already reflects successful delivery on its AI and consulting led transformation and margin targets. As a result, this narrative views the stock as leaving limited room for disappointment, overvalued and bearish.
See why 3 investors see Everforth as 36% overvalued.
Result: Fair Value of $27.50 (OVERVALUED)
Still, Everforth could challenge this bearish view if its multiyear federal backlog converts to steadier revenue and structural cost programs support stronger cash generation.
Find out about the key risks to this Everforth narrative.
Another View: What Everforth’s P/E Is Really Telling You
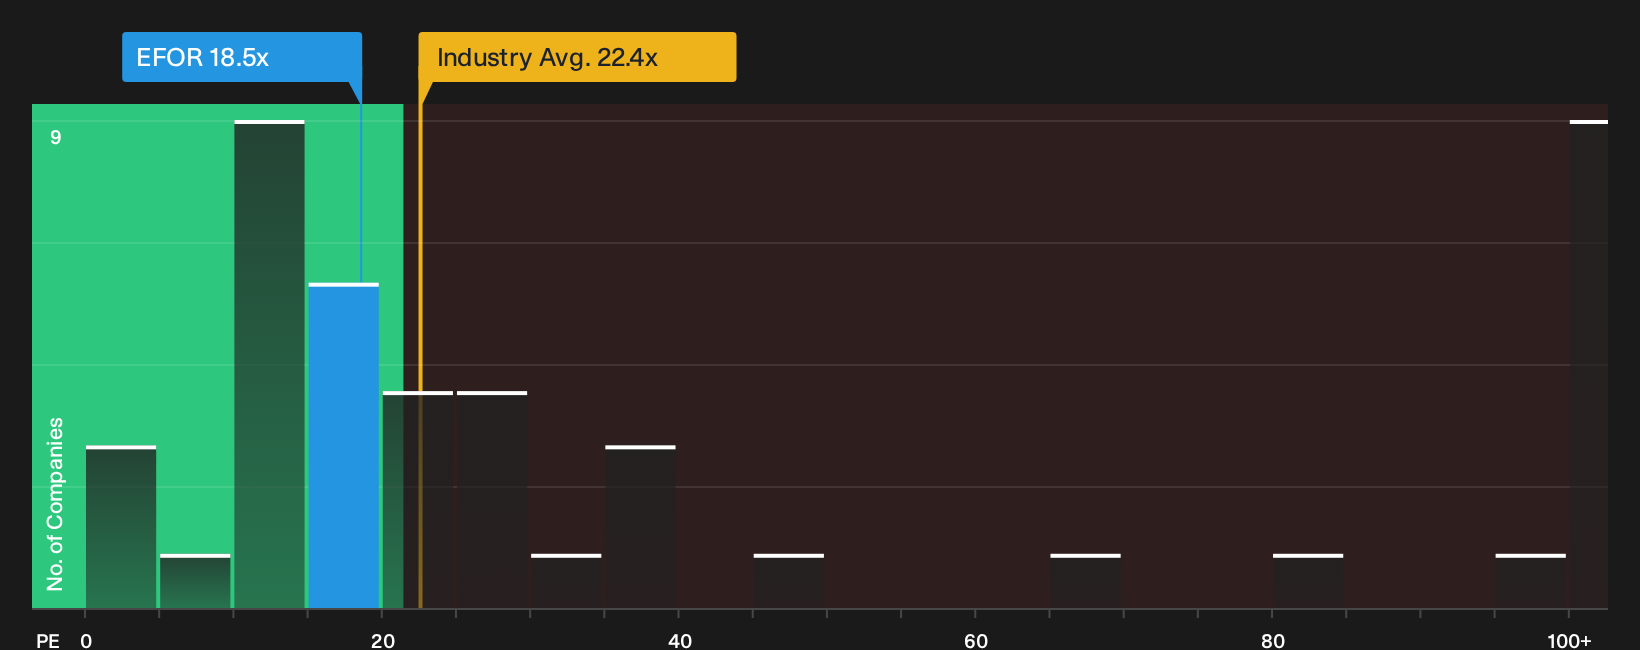
Analysts calling Everforth 36% overvalued are working off their own fair value math. The market is looking at a different scoreboard. On a P/E of 18.5x, the stock trades slightly above direct peers at 18.2x, sits below the wider US IT group on 22.4x, yet screens far below a fair ratio of 35.9x. That mix points to real valuation risk if earnings disappoint, but it also hints at room for re rating if Everforth delivers on the forecast profit ramp.
For a closer look at how this pricing gap could close in either direction, check the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals across Everforth’s narratives can feel confusing, so move fast, review the underlying data, then pressure test your own takeaway against the 2 key rewards and 3 important warning signs.
Looking for more Everforth sized investment ideas?
If Everforth has your attention right now, do not stop at a single ticker. Broaden your watchlist with fresh ideas sourced directly from focused screeners on Simply Wall St.
- Target resilient balance sheets and steady fundamentals by running a list of solid balance sheet and fundamentals (25 results) before market sentiment shifts again.
- Hunt for mispriced opportunities where quality and valuation still line up using the 29 high quality undervalued stocks while others stay glued to crowded trades.
- Stack potential income ideas on top of your growth watchlist by scanning the 8 dividend fortresses before the next round of payouts is priced in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com