
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
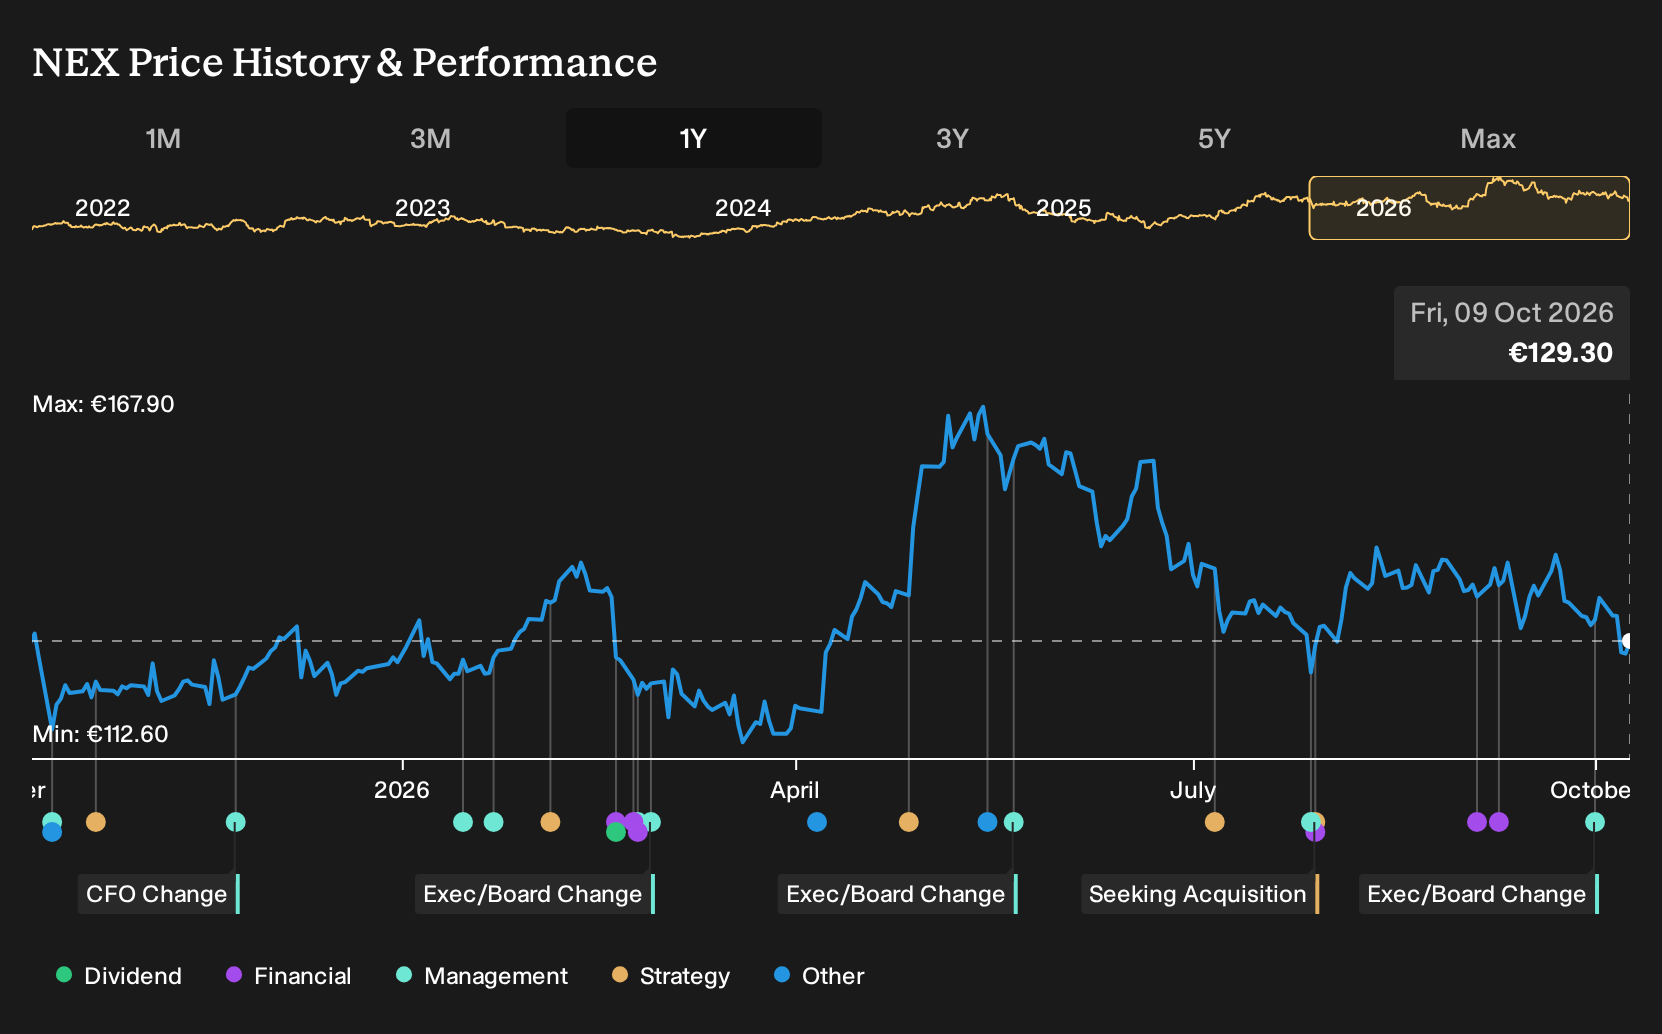
How Investors Are Reacting To Nexans (ENXTPA:NEX) Leadership Change
- Nexans has reshaped its Northwest Africa leadership by appointing energy-sector veteran Amine Houssaim as General Director of Nexans Northwest Africa and Nexans Maroc, and naming long-serving executive Noureddine Aouda as Deputy General Director, with former regional head Selma Alami remaining on the Nexans Maroc board.
- This reshuffle concentrates operational leadership in executives with deep experience in industrial operations, energy transition and digital projects, which is directly relevant to Nexans’ focus on electrification and grid-linked growth in Morocco and West Africa.
- We will now see how Nexans’ investment narrative could be influenced by this leadership refresh in its Northwest Africa operations.
Nexans Investment Narrative Recap
To own Nexans, you need to believe its push toward electrification, power grid and transmission work can translate into higher quality earnings, even with revenue forecast to edge down slightly each year. In the short term, the key swing factor is execution on higher margin projects while keeping recent profit gains, after earnings grew 47.3% over the past year.
The biggest risk is pressure on profitability if competition intensifies or large projects slip, at a time when management is still relatively new and one off items have distorted recent results. The Northwest Africa leadership change looks incremental rather than a clear near term catalyst for group earnings.
One useful reference point for this leadership reshuffle is the broader transformation of Nexans toward a near pure play electrification business, with heavier use of AI in pricing and operations. That shift is aimed at supporting earnings that analysts expect to grow about 23.6% per year, even while revenue is projected to drift slightly lower.
New management in Northwest Africa will be judged on how well they support these priorities on the ground, particularly in grid and energy transition projects in Morocco and West Africa. Execution there ties into group level catalysts such as margin quality, backlog visibility and the ability to offset cyclical weakness in more exposed construction and automotive demand.
What The Forecasts Assume For Nexans
Nexans' analyst narrative points to revenue of €7.5 billion and earnings of €467.0 million by 2029, based on a yearly 1.4% decline in revenue and an earnings increase of €253.0 million from €214.0 million today.
Uncover why Nexans' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view treats Nexans' AI and digital rollout as the main potential upside. The most optimistic analysts were already pencilling in flat revenue around €7.7b and earnings near €648.8m by 2029. You can now ask whether this Northwest Africa leadership change reinforces that upbeat story or forces a rethink.
Explore 6 other Nexans fair value estimates, including one that suggests as much as 58% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nexans research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nexans. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nexans' overall financial health at a glance.
Looking for more Nexans-sized investment ideas?
If tracking Nexans has sharpened your sense of what you want in a business, the next step is lining up similar opportunities that match your risk tolerance, income needs and time horizon. The Simply Wall St Screener can help you filter the market quickly so you spend your energy on the deeper work of understanding each company, not just trawling for tickers.
- If capital preservation sits high on your list, start with a set of companies that combine resilient balance sheets with measured risk scores through the 226 resilient stocks with low risk scores.
- For investors focused on quality and price discipline, you can narrow the field to financially sound businesses trading below their assessed value using the 179 high quality undervalued stocks.
- If you prefer to get in early on quieter stories with solid fundamentals, use the screener to surface a curated pool of 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com