
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What You Need To Know Ahead of Kimberly-Clark's Earnings Release
Dallas, Texas-based Kimberly-Clark Corporation (KMB) manufactures and markets personal care products in the United States. The company has a market cap of $32.5 billion and operates in two segments, North America and International Personal Care, offering disposable diapers, training and youth pants, swim pants, baby wipes, feminine and incontinence care products, and more. KMB is expected to release its Q3 2026 earnings soon.
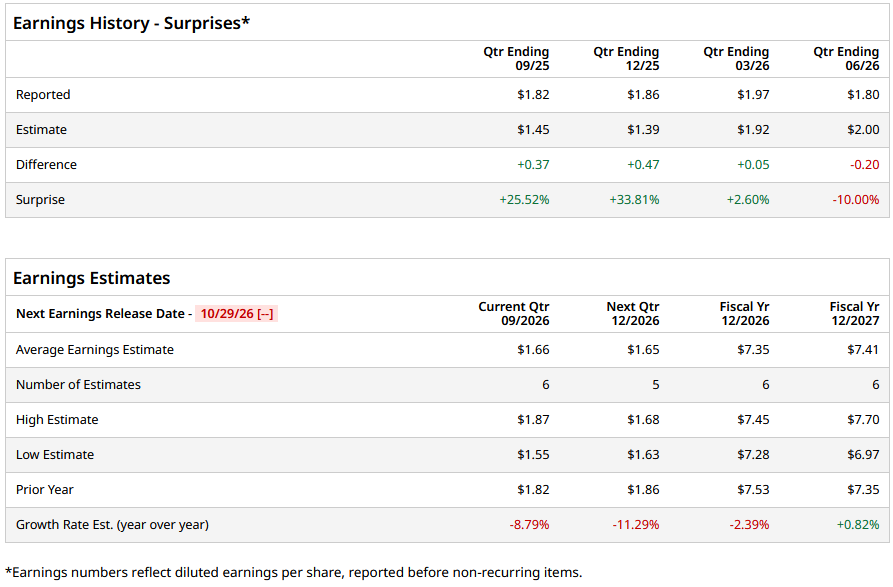
Ahead of this event, analysts anticipate the company will generate earnings of $1.66 per share, representing a fall of 8.8% from $1.82 per share reported in the same quarter last year. The company has surpassed the Street’s bottom-line estimates in three of the past four quarters, while missing on one occasion.
For fiscal 2026, analysts expect the company to report an EPS of $7.35, indicating a 2.4% fall from $7.53 reported in fiscal 2025. However, its EPS is expected to rise marginally year over year (YoY) to $7.41 in fiscal 2027.
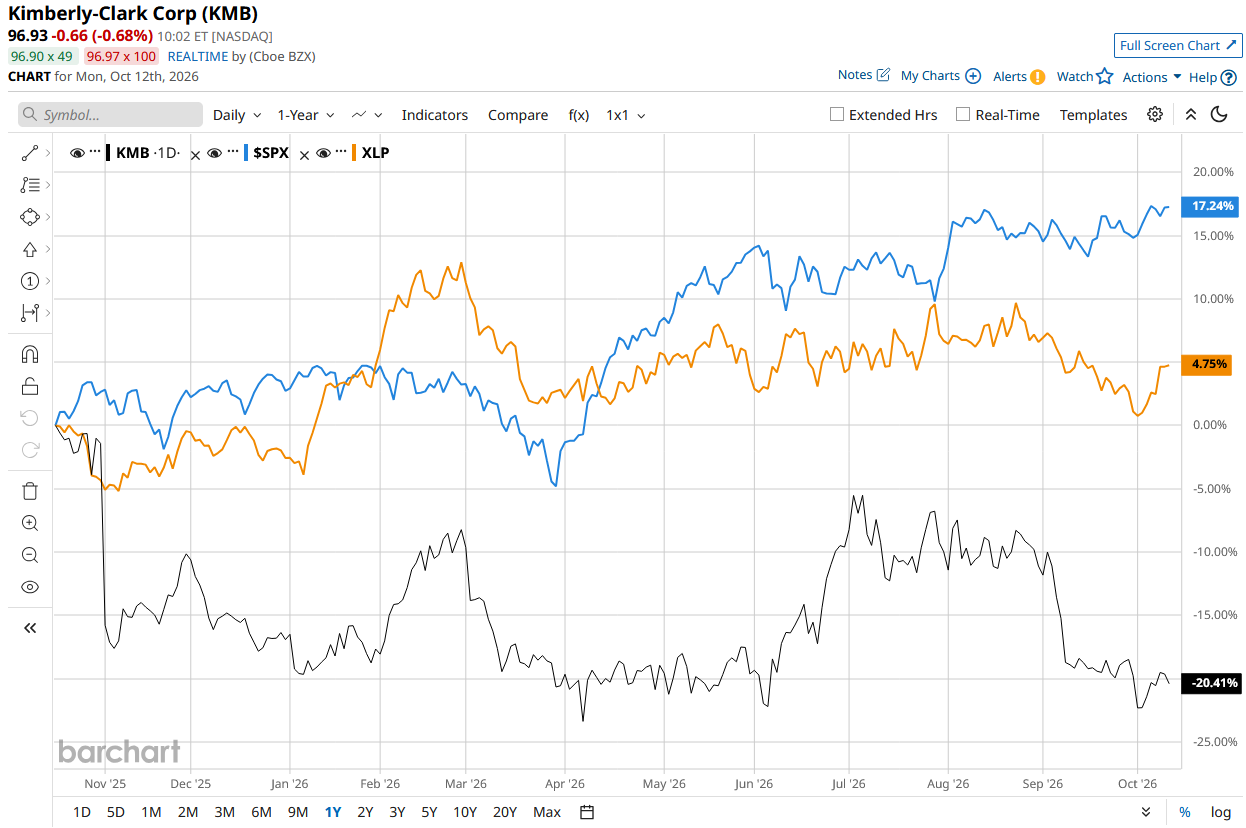
KMB stock has fallen 19.3% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 16% rise but outpacing the State Street Consumer Staples Select Sector SPDR ETF’s (XLP) 6.9% rise during the same time frame.
On Aug. 4, KMB stock declined 2.8% following the release of its mixed Q2 2026 earnings. The company’s revenue for the quarter remained flat year-over-year and came in at $4.2 billion, missing the Street’s estimates. Moreover, its adjusted EPS amounted to $2.12, beating the consensus estimates. The company’s operating margin and free cash flow margin also remained the same compared to the year-ago quarter. KMB’s organic revenue missed Wall Street’s estimates as well, while remaining flat YoY.
The consensus opinion on the stock is moderately bullish, with a “Moderate Buy” rating overall. Of the 16 analysts covering the stock, five recommend a “Strong Buy,” one suggests a “Moderate Buy,” nine suggest a “Hold,” and one recommends a “Strong Sell.” KMB’s average analyst price target is $114.35 and offers a 17.7% upside.
On the date of publication, Aritra Gangopadhyay did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.