
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 European Auto Stocks Facing The Chinese Hybrid Import Cap
Chinese hybrid imports into Europe now face a strict cap, and that suddenly reshapes who wins and loses in the region’s auto supply chain. Market share that once looked up for grabs is being rationed, which can redirect pricing power, factory volumes, and bargaining leverage. This article walks through three European auto stocks directly exposed to this policy shock and explains how each could respond, for better or worse.
The stocks covered below are just a sample of the idea, and the full screen surfaced 19 more European auto manufacturers and suppliers with equally compelling narratives that are not discussed here. To identify and analyze the highest conviction opportunities in this theme, head straight to the European Auto Manufacturers and Suppliers screener.
Forvia (ENXTPA:FRVIA)
Forvia is a textbook fit for this European auto suppliers theme, plugging directly into what goes into each vehicle that EU carmakers ship and increasingly what powers them. This makes its mix of seating, interiors and electronics especially important as trade rules tighten.
Forvia is a global automotive technology group supplying seats, interiors, exhaust and clean mobility systems, electronics, lighting and lifecycle solutions. Revenue is concentrated in Seating at about €7.7b, Electronics at roughly €4.9b, Clean Mobility at around €3.9b and Lighting near €3.5b, and the stock is valued at about €1.7b today.
"The acceleration of electric vehicle adoption, along with OEMs demanding new architectures, threatens to reduce demand for Forvia's traditional interior platforms and core product lines. This may cap overall revenue growth and limit content per vehicle as value migrates toward software-centric and simpler interiors over time."
What really influences the story for Forvia is how one less visible shift in where value sits inside the car ultimately affects margins.
To see how that margin story could evolve from risk to opportunity, read the full narrative for Forvia and spot where Forvia’s interior shift might be quietly accelerating returns.

Stellantis (BIT:STLAM)
Stellantis is one of the heavyweight European automakers in this screen, with a broad stable of brands and a dense manufacturing base that directly ties into how Europe responds to capped Chinese hybrid imports.
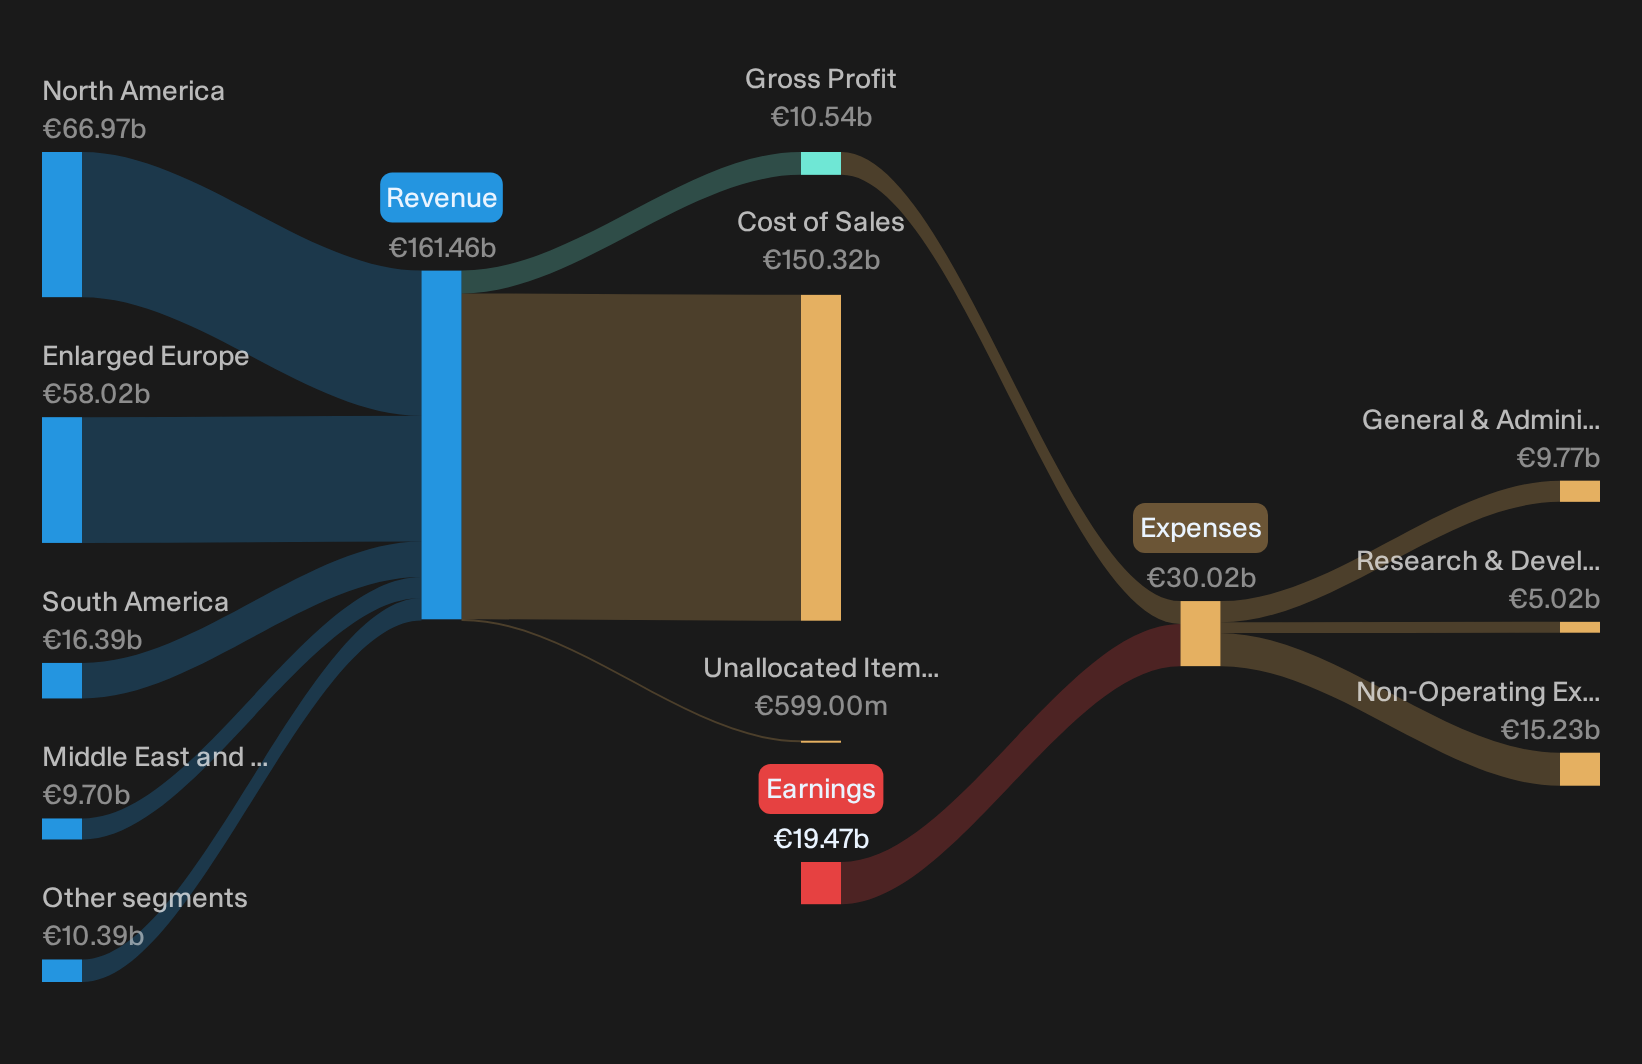
Stellantis designs and sells passenger cars, light commercial vehicles and related services worldwide under brands like Fiat, Peugeot, Jeep and Maserati, making it a key player in European vehicle and powertrain production. Revenue is heavily skewed to North America at about €66.9b and Enlarged Europe at roughly €58.0b, with South America at around €16.4b, the Middle East and Africa near €9.7b, Asia Pacific at about €1.8b and other activities contributing close to €7.9b. The stock is valued at roughly €11.6b.
"The deterioration in the financial position is harder to ignore. Industrial free cash flow was negative €4.5 billion in 2025."
What this means for Stellantis investors now largely comes down to how one unresolved pressure in its European hybrid push affects future margins.
That pressure point is exactly where the story gets interesting, and the full narrative for Stellantis shows how Stellantis could turn today’s cash strain into tomorrow’s leverage.
Gestamp Automoción (BME:GEST)
Gestamp Automoción is firmly plugged into the European Auto Manufacturers and Suppliers theme as a Tier-1 metal components specialist, supplying body, chassis and structural parts to vehicle makers. The company generates about €11.4b in auto parts revenue on a roughly €1.7b market value.
For investors tracking how European-listed suppliers respond as local production adjusts to capped Chinese hybrid imports, Gestamp Automoción offers a clear test of whether volume resilience and cost control can keep earnings on track.
"Although Gestamp Automoción is keeping EBITDA margins resilient through cost measures, the hit of €157 million to H1 2026 revenue from foreign exchange shows that currency pressure can quickly offset operational progress and may weigh on reported earnings if adverse moves persist."
What really matters now is how one underappreciated swing factor between European production volumes and cash generation plays out on Gestamp Automoción’s margin profile.
If that cash swing interests you, read the full narrative for Gestamp Automoción to see how Gestamp Automoción's volume mix, FX exposure and capex plans could be quietly decoupling.

Seeking Fresh Alternatives Before They Fly
Markets move quickly, and the next breakout group of stocks rarely stays under the radar for long. Scan these fresh ideas before the crowd and consider them while they are still in focus.
- Track cash-rich businesses that keep risk in check by running through the list of solid balance sheet and fundamentals (202 results) while prices and expectations still feel reasonable.
- Spot momentum setting up in future infrastructure by checking the 43 power grid technology and infrastructure stocks before these grid plays are fully driven by headline-focused investors.
- Target real earnings momentum in automation by reviewing the curated 91 robotics and automation stocks while valuation gaps and growth stories still appear mispriced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com