
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Airbnb (ABNB) Priced For More Than Its AI Push?
Airbnb has delivered a strong run over the past year, and the stock now reflects optimistic expectations about how much cash the business can generate. With fresh AI tools and new services rolling out, the key question is whether the current share price lines up with the cash flows that these initiatives may support.
- The stock is up 39.6% over the past year, which puts more pressure on the underlying cash flows to justify that kind of move.
- Airbnb's 2026 fall update, featuring AI-powered search and on-demand guest services, can shape expectations for future margins and the timing of cash generation from both guests and hosts.
- If you'd rather focus on earnings, this one's for you. See why Airbnb's 36.3x P/E tells a different valuation story.
The stock's next move may depend on whether Airbnb's current cash flows and their implied trajectory are sufficient to support the price investors are paying today.
If you want more than one stock story tied to AI and cash flow expectations, a focused starting point is a list built from 38 AI small caps.
Is Airbnb Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here is built on Airbnb’s ability to keep converting bookings into growing free cash. Over the last twelve months the platform generated about $4.86b in free cash flow, and the model assumes that this pool of cash expands over time rather than shrinks, with projections pointing to higher annual free cash flows by 2030.
Based on that set of assumptions, the DCF output suggests Airbnb’s estimated intrinsic worth is substantially above the current share price of $165.87. The recent 2026 fall update, which includes AI search and new host tools, helps explain why the market is already pricing in richer cash generation. Even so, the DCF still indicates a gap between the price and what the projected cash flows support. Find out what Airbnb could be worth using our Discounted Cash Flow (DCF) estimate.
The Airbnb Narrative: What Would Justify Today's Price?
Narratives aim to close the gap between Airbnb's current price and the earlier valuation puzzle by explaining which future paths for growth, margins and earnings would need to hold for the stock to be worth much more or less than it is today on Simply Wall St's Community page. Each story ties a fair value to a particular mix of possible catalysts and risks, so you can monitor over time which version of Airbnb's future appears to be unfolding.
Community views on Airbnb are split between one group that sees more upside left and another that thinks the quality is largely priced in.
Bull case: 9% undervalued
"They’ve launched long-term rentals, made over 500 product improvements, and are going all in on AI to make the platform smoother…"
Discover why this Narrative puts Airbnb at 9% undervalued.
Bear case: roughly fairly valued
"ABNB often trades at a premium relative to traditional travel companies, reflecting its strong brand, cash generation, and global scale…"
Explore why this Narrative puts Airbnb at roughly fairly valued.
Airbnb's price is just one signal, but ownership moves may tell you something different
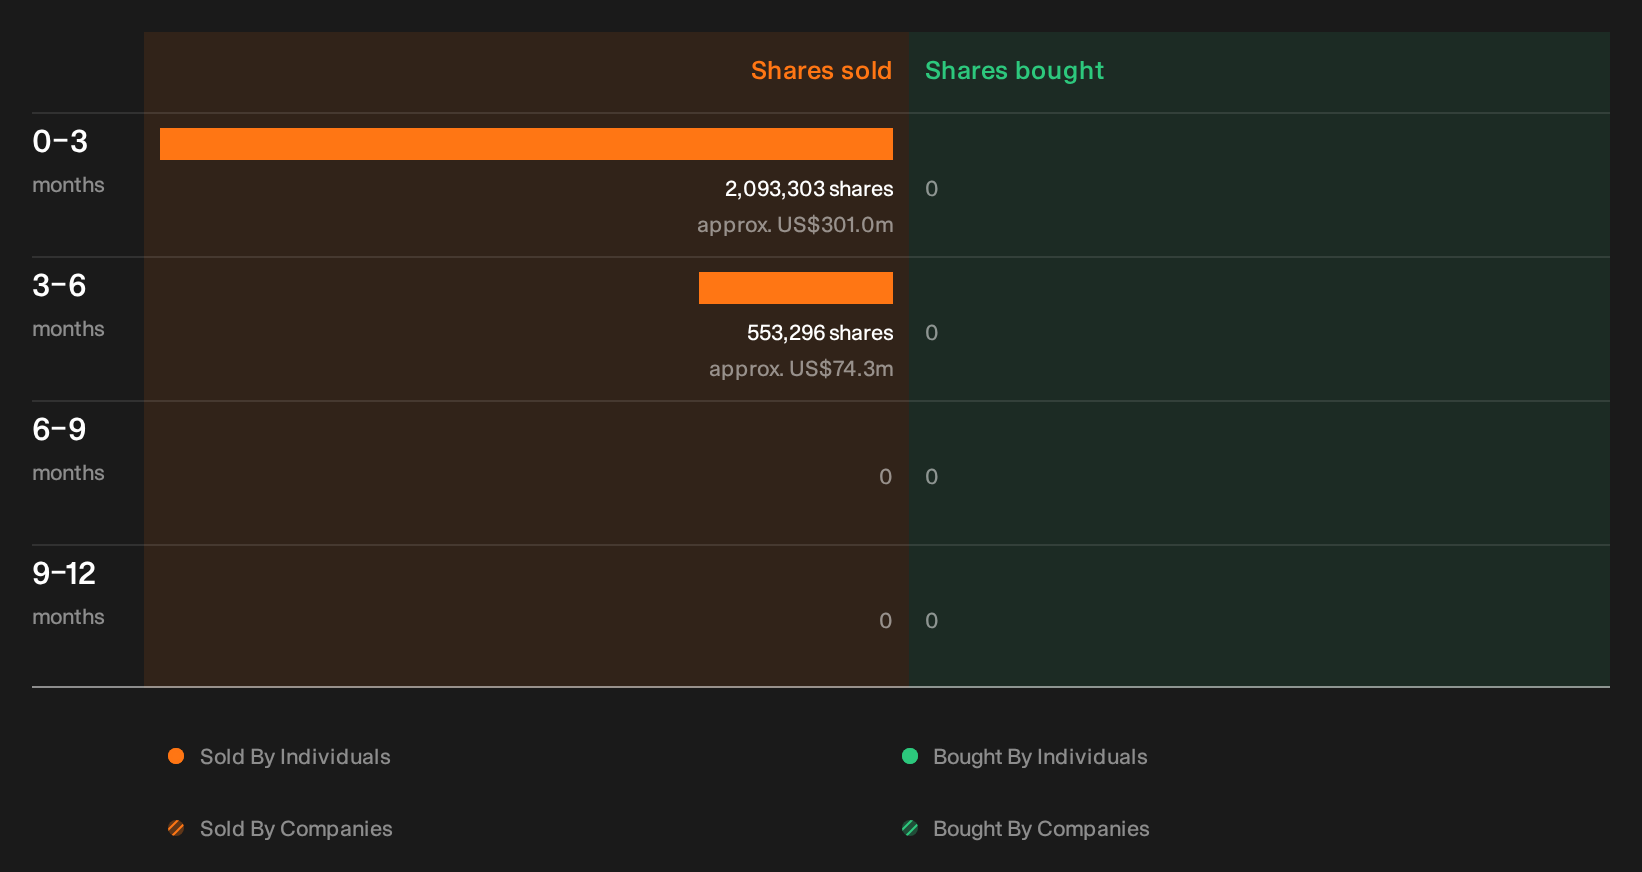
Valuation work only goes so far if you ignore what the people closest to Airbnb are doing with their own holdings, and recent selling activity our checks picked up is the next piece worth examining. See the recent insider selling flagged for Airbnb.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com