
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ConocoPhillips Stock Has Been in a Trading Range - Ideal for Short Put COP Plays
ConocoPhillips (COP) stock has been trading flat for the last two or three months. That's ideal for investors who short sell out-of-the-money COP puts and put credit spreads.
COP closed at $134.10 on Friday, Oct. 9, but over the last 2 months it's been as high as $141.22 on Sept. 15 and as low as $124.52 on Aug. 13. So, right now, it's in the middle of a trading range.
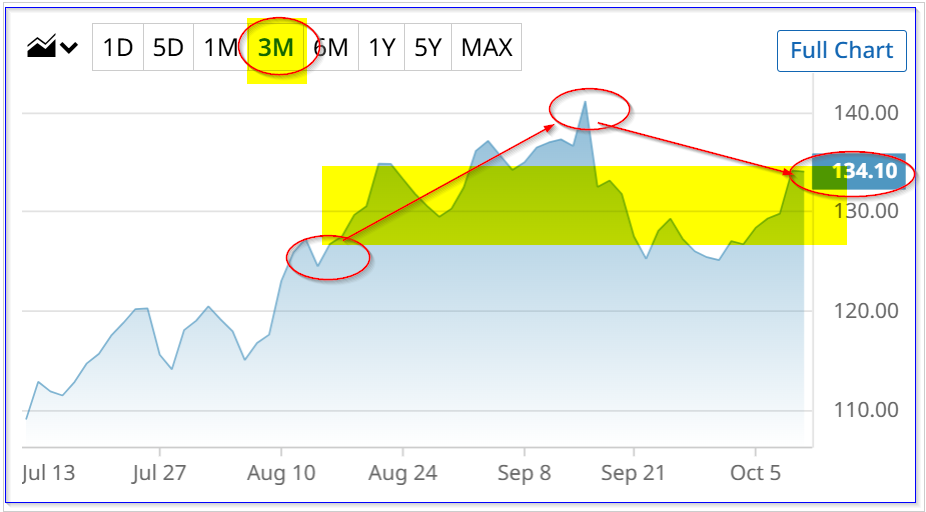
But analysts still see significant upside in their price targets (PTs). For example, Yahoo! Finance's survey shows an average PT of $146.88.
That's up from $145.44, as seen in my last Barchart article a month ago (Sept. 13), “Is ConocoPhillips Stock Worth Buying Here? - Shorting COP Puts and Credit Spreads are Better Plays.”
Moreover, analysts are preparing to update their price targets after the upcoming Nov. 5 Q3 earnings results. That means the stock may be stuck in this trading range up until then.
I previously discussed shorting out-of-the-money (OTM) COP put options. This has worked well, as I will show below. It's time to redo this play.
OTM COP Short-Put and Put Credit Spread Plays Worked Well
In my Sept. 13 Barchart article on COP, I discussed selling short the $130 put strike price expiring Oct. 16. At the time, COP was at $137.35, so this play was -5.6% OTM (i.e., $130/$137.35-1) and the delta ratio was -0.263, implying a 73.7% chance of success.
As it turned out, that play worked out well as the put premium fell from $2.21 to just $0.62 as of Friday, Oct. 9. That means the investor has made $159 (i.e., ($2.21-$0.62) x 100), on $13,000 in collateral, or 1.22% over the last month.
I also discussed doing a put credit spread for investors who didn't have $13K in collateral. The spread was also $159 (i.e., $221-$62) (quite a coincidence!) for a $120 put buy as well as the short $130 put.
But the required collateral capital for this play was only $1,000 (i.e., ($130-120) x 100). So, the expected return (ER) was $159/$1,000, or 15.9%.
As it has turned out, the spread has narrowed to just $57 (i.e., ($0.62 - 0.05) x 100). So, the implied profit, if this play is closed out now, is $102 (i.e., $159-$57). That represents a 10.2% gain (i.e., $102/$1,000) over the last 3 weeks.
The investor can wait until closer to Oct. 16 to close the play at an even lower spread if COP stays flat.
New COP Short-Put and Put Credit Spread Plays
A new play worth investigating is to short the $127 put expiring Nov. 13 for $2.39 at the midpoint. That represents a potential yield of 1.88% over the next month (i.e., $2.39/$127).
This could be a good play since the delta ratio is just -0.27, implying a 73% chance of success. In addition, the strike price is still 5.3% lower, providing some downside protection.
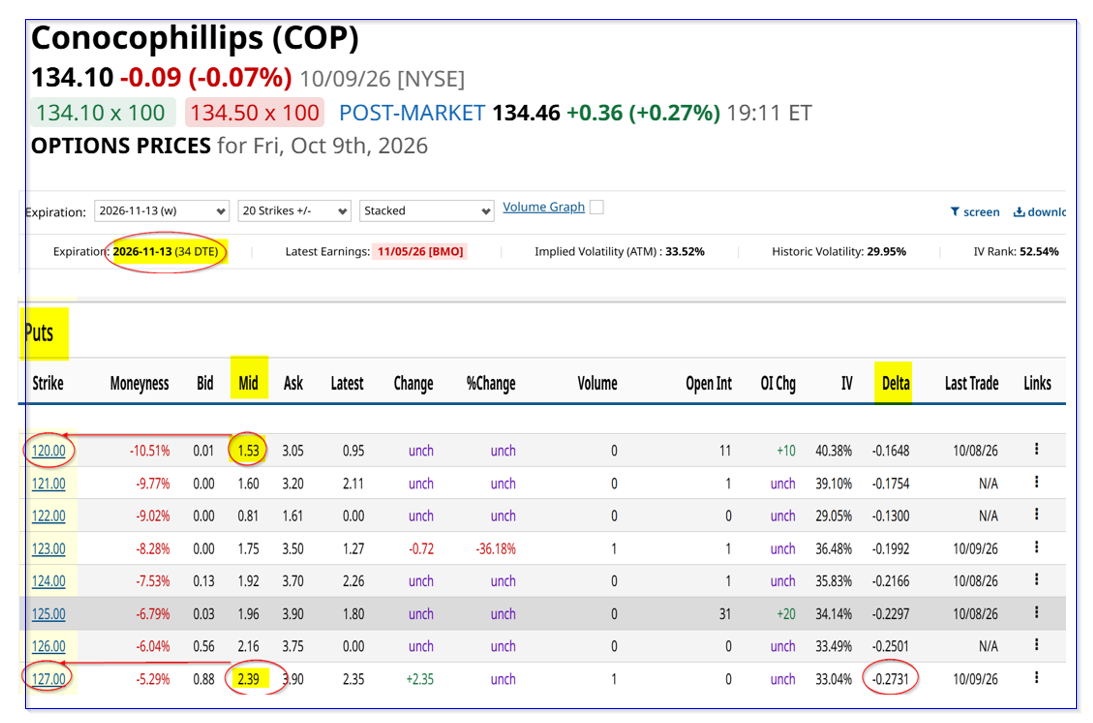
Moreover, the breakeven point is $127-$2.39, or $124.61, or 7.1% lower. That means even after assignment, the investor is buying in at an attractive price.
However, this play requires $12,700 in collateral. For investors willing to take on more risk, a put credit spread is potentially more attractive.
For example, the table above shows that the $120 put premium is $1.53. So, shorting the $127 put for $239 and buying the $120 put for $153 (to provide downside protection), provides a net spread of $86.00.
But the required collateral capital is just $700 (i.e., ($127 - $120) x 100). So, the put credit spread expected return (ER) is high:
$86/$700 = 12.29%
Since the $86 is collected upfront, the net collateral at risk is just $614. So, the net ER is higher:
$86/$614 = 14.0%
The risk is that COP drops below $126.14 (i.e., $127 - $0.86 net credit spread), or -5.94%. If it drops to $120, the whole $700 (net $614) collateral is lost.
Moreover, unlike a short-put play, the investor does not end up owning COP shares upon assignment, unless they sell the long put leg.
Nevertheless, this could be a more speculative play for investors to make higher returns on COP, ahead of its earnings release.
On the date of publication, Mark R. Hake, CFA did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.