
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Worthington Steel (WS) Earnings Reset Puts Fair Value Back In Focus
Why the latest Worthington Steel earnings matter for investors
Worthington Steel (WS) is back in focus after first quarter results showed sales of US$2,726.6 million and a swing to a net loss of US$10 million, alongside a maintained quarterly dividend.
Recent trading reflects that mixed picture. Worthington Steel’s share price is up 4.13% over the last day and has gained 6.34% over 30 days, yet it is down 7.85% on a 7 day share price return, while the 1 year total shareholder return of 21.94% points to momentum that has been building over a longer stretch.
Scan how Worthington Steel’s earnings reset compares to other metals processors by reviewing our hand picked list of solid balance sheet and fundamentals (25 results), which are built to handle tougher quarters.
After Worthington Steel’s sharp swings in both earnings and recent returns, the next thing to pin down is simple: Is most of the upside already captured or is the valuation still leaving room ahead?
Most Popular Narrative: 5.1% Undervalued
Worthington Steel’s most followed narrative pegs fair value at $38 per share, a touch above the recent $36.05 close. This frames the current move as modest rather than extreme and puts the focus on what could shift earnings power from here.
Worthington Steel is poised to benefit from increased demand in the electrical steel market due to AI initiatives, more data centers, and an anticipated annual power demand growth of more than 6% over the next 15 years, which should lead to higher revenues.
Strategic investments and acquisitions, such as the expansion of electrical steel capabilities in Canada and Mexico and the expected closing on a 52% stake in the European company Sitem, are set to enhance market share and drive revenue growth.
See why 5 investors see Worthington Steel as 5% undervalued.
Result: Fair Value of $38 (UNDERVALUED)
Still, weak demand in automotive and construction, along with the recent drop in earnings and adjusted EBITDA, could quickly challenge the current Worthington Steel fair value story.
Find out about the key risks to this Worthington Steel narrative.
Another View: Worthington Steel Looks Expensive On Cash Flows
The fair value story for Worthington Steel shifts when the SWS DCF model is used. On this approach, the estimated future cash flow value sits at just $2.97 per share, while the market price is $36.05. That points to a stock that screens as materially overvalued on cash flows. Where does that leave investors weighing the 5.1% undervalued narrative?
For a closer look at how this cash flow view is built, and what would need to change in the assumptions to narrow that gap, Look into how the SWS DCF model arrives at its fair value..
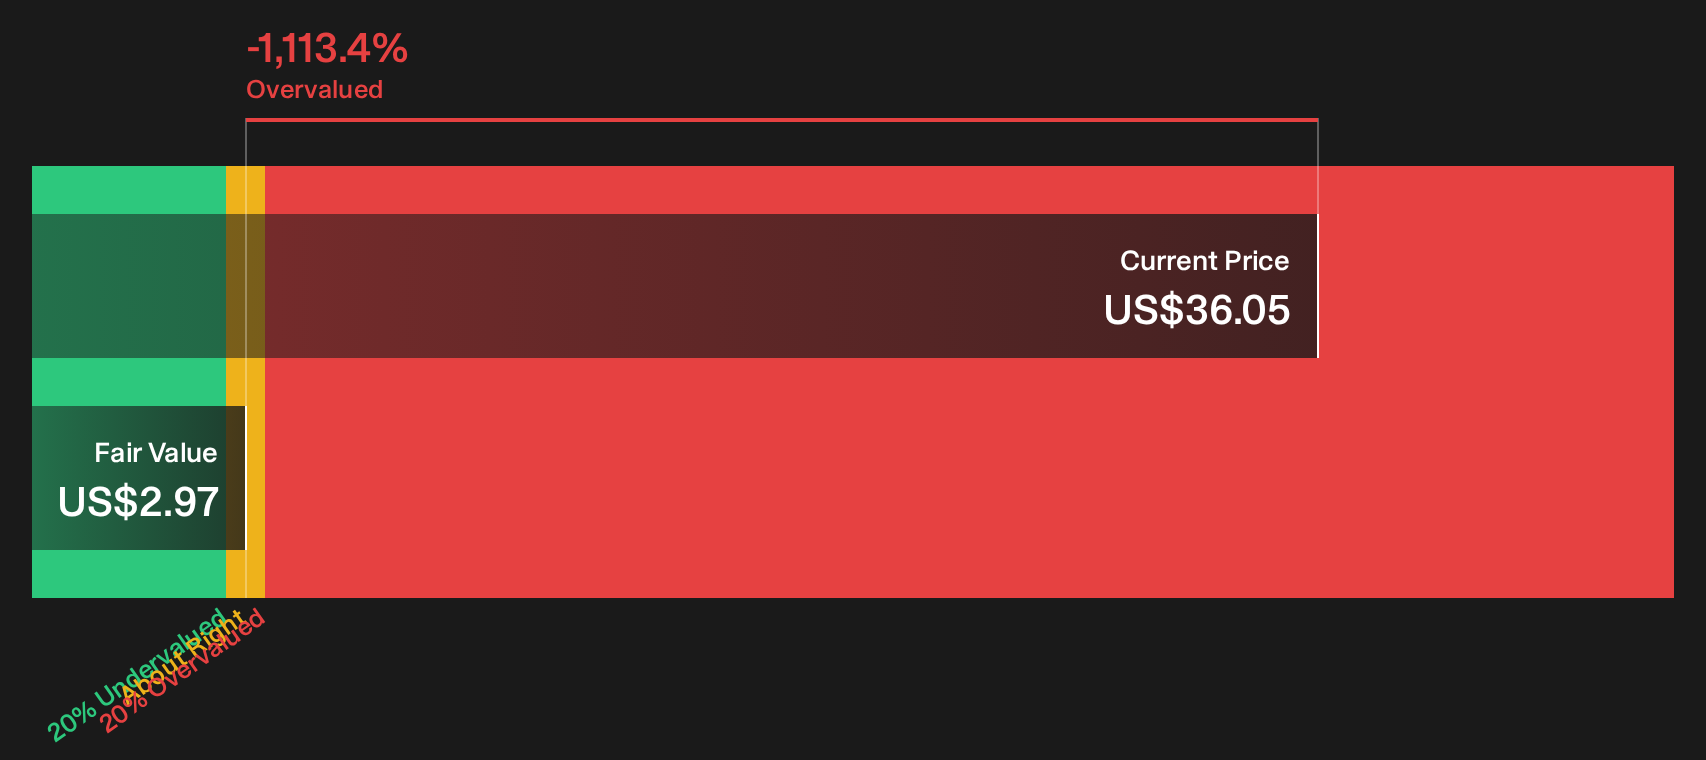
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Worthington Steel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split between fair value and DCF views on Worthington Steel feels unresolved, trust that instinct and put the numbers under your own microscope. Move quickly, review the full set of potential red flags, and weigh the 3 important warning signs.
Looking for more Worthington Steel investment ideas?
Do not stop your work with Worthington Steel alone. Broaden your watchlist with fresh opportunities that match different goals and risk levels using the Simply Wall Street Screener.
- Target quality at a discount by scanning a curated 29 high quality undervalued stocks that combine solid fundamentals with prices that may leave room for upside.
- Lock in potential income streams by reviewing a focused set of 8 dividend fortresses that specialise in higher yields with supporting financials.
- Dial down downside risk by tracking 31 resilient stocks with low risk scores designed to prioritise resilience when conditions turn against more fragile businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com