
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Tech Dividend Stocks Riding The AI Infrastructure Earnings Rebound
Global banks are turning more upbeat on equities as earnings forecasts for the S&P 500 push toward roughly 25% profit growth for Q3, and that shift in mood is feeding fresh attention into large, resilient dividend payers. If you worry about missing the next leg of this move, you are not alone. This article walks through 3 stocks from the Global Tech and Quality Dividend Barbell Winners screener that appear as potential beneficiaries of the latest market backdrop.
The three stocks highlighted below are just a sample from this barbell idea, and the full screen surfaced 13 more companies with equally detailed stories that are not covered here. To identify and analyze the highest conviction mix of growth and dividend strength for your own portfolio, head straight into the Global Tech and Quality Dividend Barbell Winners screener.
Vanguard International Semiconductor (TPEX:5347)
Overview: Vanguard International Semiconductor runs a Taiwan based foundry business that manufactures, packages, and tests integrated circuits for global clients.
Operations: The group generates about NT$51.7b from wafer manufacturing, with sales concentrated in Asia at NT$39.4b and America at NT$10.3b.
Market Cap: NT$350.3b
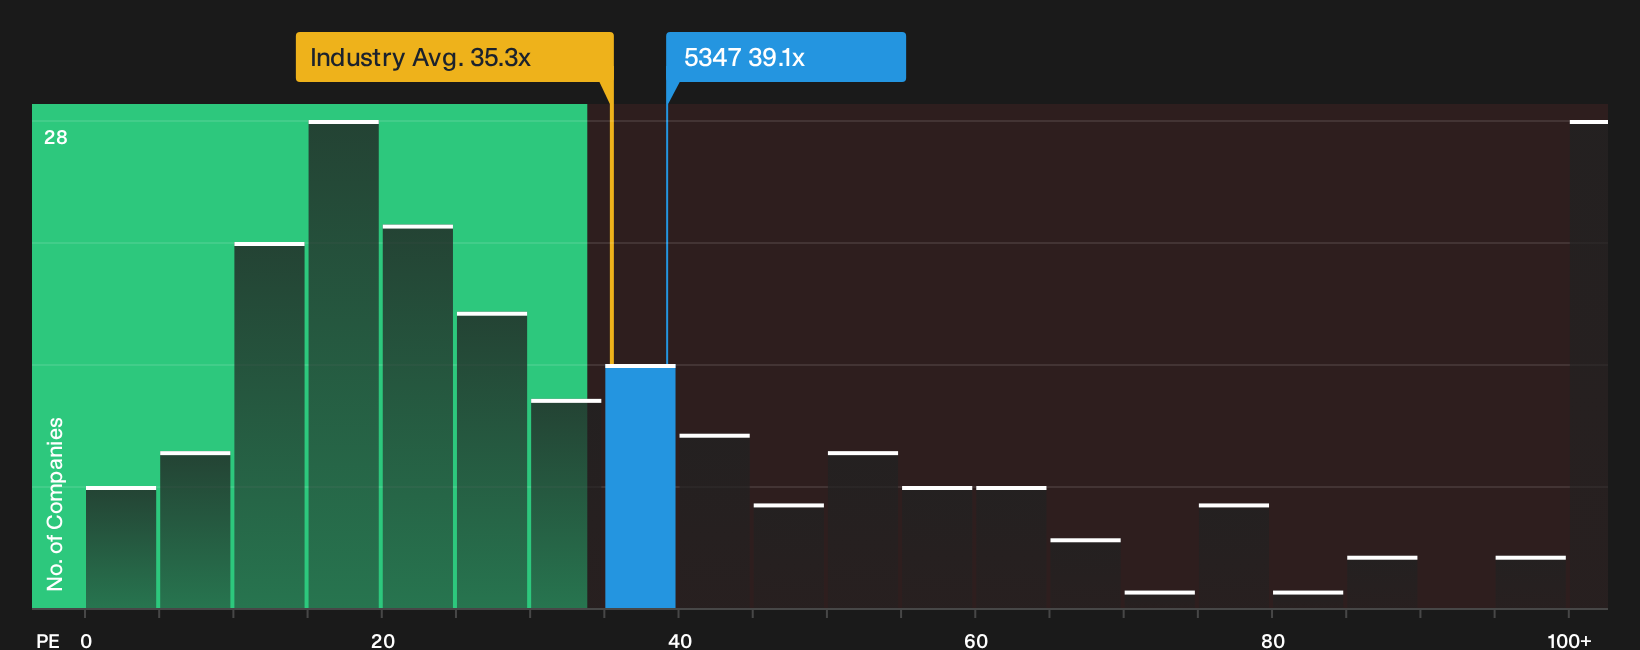
Vanguard International Semiconductor is included on this barbell screen as a foundry business with rising sales and net income across recent quarters, high forecast earnings and revenue expansion, and an established dividend, although coverage looks tight. The investment case depends on how that profit profile interacts with a premium P/E and one unresolved pressure on dividend funding and future margins.
With that trade off in mind, go straight to the 1 key reward and 3 important warning signs (2 are major!) to see whether Vanguard International Semiconductor’s premium P/E is masking risk or overlooked strength.
Mitsui High-tec (TSE:6966)
Overview: Mitsui High-tec manufactures electrical and electronic components, precision tooling and grinders, and EV and appliance motors that feed global tech hardware demand.
Operations: The business generates ¥167.1b from Electrical Parts, ¥69.6b from Electronic Parts, and ¥11.4b from Tooling and Machine Tools.
Market Cap: ¥165.9b
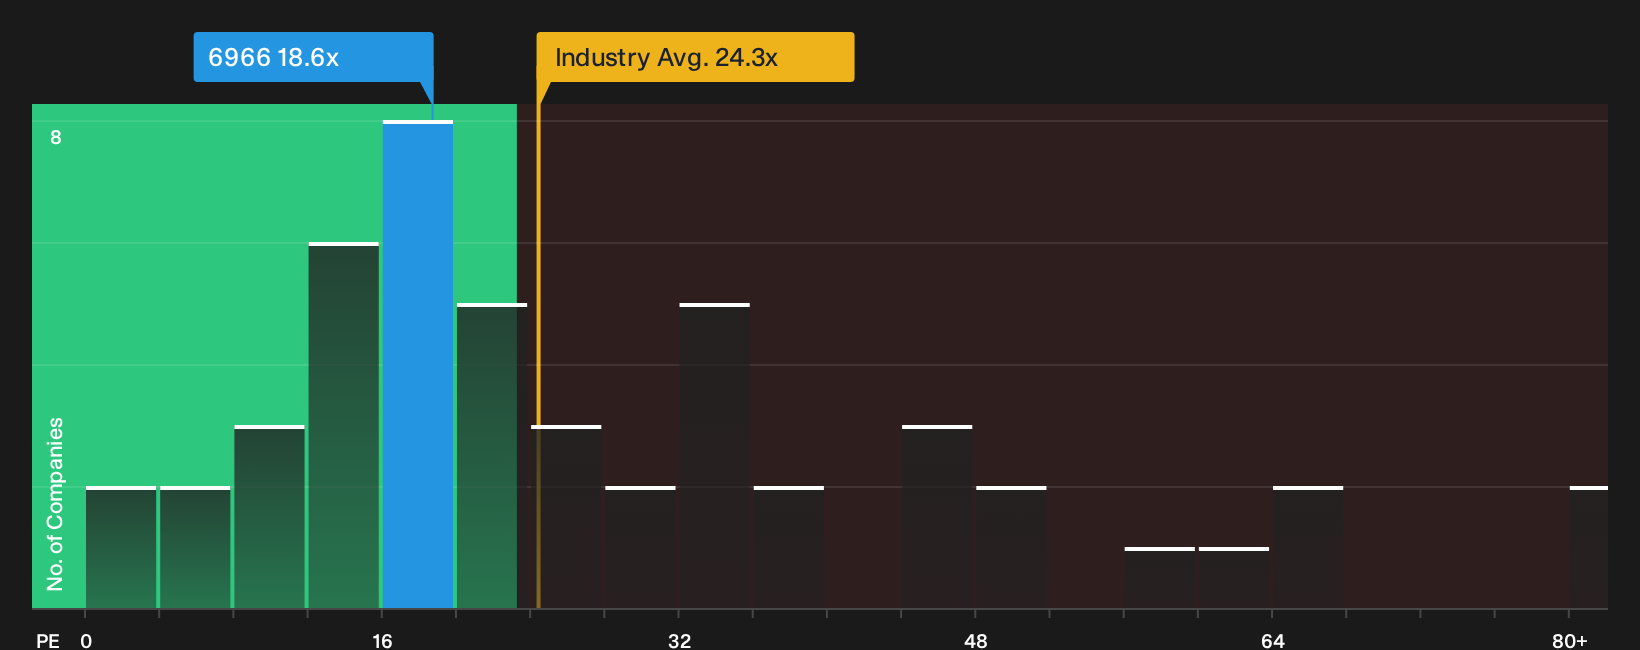
Mitsui High-tec provides global tech hardware exposure and a 2.09% dividend yield within this barbell structure. Earnings are now guided higher for FY2027 following stronger H1 trading, and the P/E of 18.6x sits below the wider semiconductor group but above closer peers. Interest in this stock largely depends on how one sizeable past loss and a fully debt-funded balance sheet affect future margins and cash returns.
To see how that trade off actually plays through the financials, jump into the 2 key rewards and 3 important warning signs and evaluate whether the balance sheet is masking a bigger opportunity.
Realtek Semiconductor (TWSE:2379)
Overview: Realtek Semiconductor designs integrated circuits and software that power connectivity, audio, video, and interface functions across global electronics and networking devices.
Operations: Realtek Semiconductor generates about NT$129.7b from microcircuit and related application software products serving a wide range of electronic device markets.
Market Cap: NT$386.1b
Realtek Semiconductor fits the growth leg of this barbell theme as a large, profitable IC designer. Its dividend profile and balance sheet are increasingly under scrutiny as global investors show renewed interest in the technology sector.
"AI data center growth is pulling advanced packaging and OSAT capacity away from Realtek's core products. If this prioritization persists, it could cap shipment volumes in PCs, consumer devices and networking, which would limit revenue growth even if end demand remains healthy."
What matters now is how a single shift in supply-chain bargaining power ultimately flows through to Realtek Semiconductor’s pricing, margins and payout capacity.
That supply chain shift is only half the story, and the full narrative for Realtek Semiconductor maps where Realtek Semiconductor’s pricing power and dividend policy could be quietly decoupling from old assumptions.

Curious About What You Might Be Missing?
Fresh opportunities can move from quiet to crowded fast. Screen for potential breakouts and momentum shifts while the data is still under the radar for now, and consider acting before the crowd.
- Spot potential early leaders in AI infrastructure and data center build outs by running the 92 AI infrastructure stocks before everyone else is chasing the move.
- Track money rotating into resilient compounders by scanning the 225 resilient stocks with low risk scores and keep a closer eye on stocks where downside risk scores already look contained.
- Hunt for potential outperformers in robotics and factory automation using the curated 91 robotics and automation stocks and stay plugged into trends that could reshape industrial supply chains.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com