
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DHT Holdings (DHT) Could Be 13% Above Fair Value Following Strong Tanker Update
DHT Holdings (DHT) grabbed investor attention after issuing a business update that put concrete numbers on its tanker earnings and capacity bookings, giving the market fresh data on its operating momentum.
For context, DHT Holdings’ share price has eased 1.16% over the last day to US$24.64. However, the 30-day share price return of 12% and year to date share price gain of 109.88%, alongside a 1-year total shareholder return of 148.7%, point to strong momentum building as investors reassess both earnings power and risk around its tanker exposure.
Scan how DHT Holdings fits alongside other oil and commodity transport plays by reviewing the hand picked 43 power grid technology and infrastructure stocks anchored to energy infrastructure and capacity demand.
DHT Holdings has surged well past its average analyst target and screens at a premium to some fair value estimates. Is that gap a warning sign or a fair price for its booked tanker earnings?
Most Popular Narrative: 13% Overvalued
DHT Holdings last closed at $24.64 while the most followed valuation framework puts fair value at $21.85. The current price embeds a meaningful premium that hinges on tanker earnings and cash returns holding up against softer analyst forecasts.
The current valuation and strong share price rally imply that a lot of optimism about DHT Holdings’ earnings power and cash distributions is already reflected in the stock.
The policy of paying out 100% of ordinary net income as quarterly dividends, alongside very large recent distributions compared with free cash flow, is expected to continue anchoring investor focus on income.
See why 101 investors see DHT Holdings as 13% overvalued.
Result: Fair Value of $21.85 (OVERVALUED)
Still, the story can change quickly if DHT Holdings’ generous dividend policy collides with weaker cash generation, or if recent insider selling proves an early warning signal.
Find out about the key risks to this DHT Holdings narrative.
Another View On DHT Holdings’ Valuation
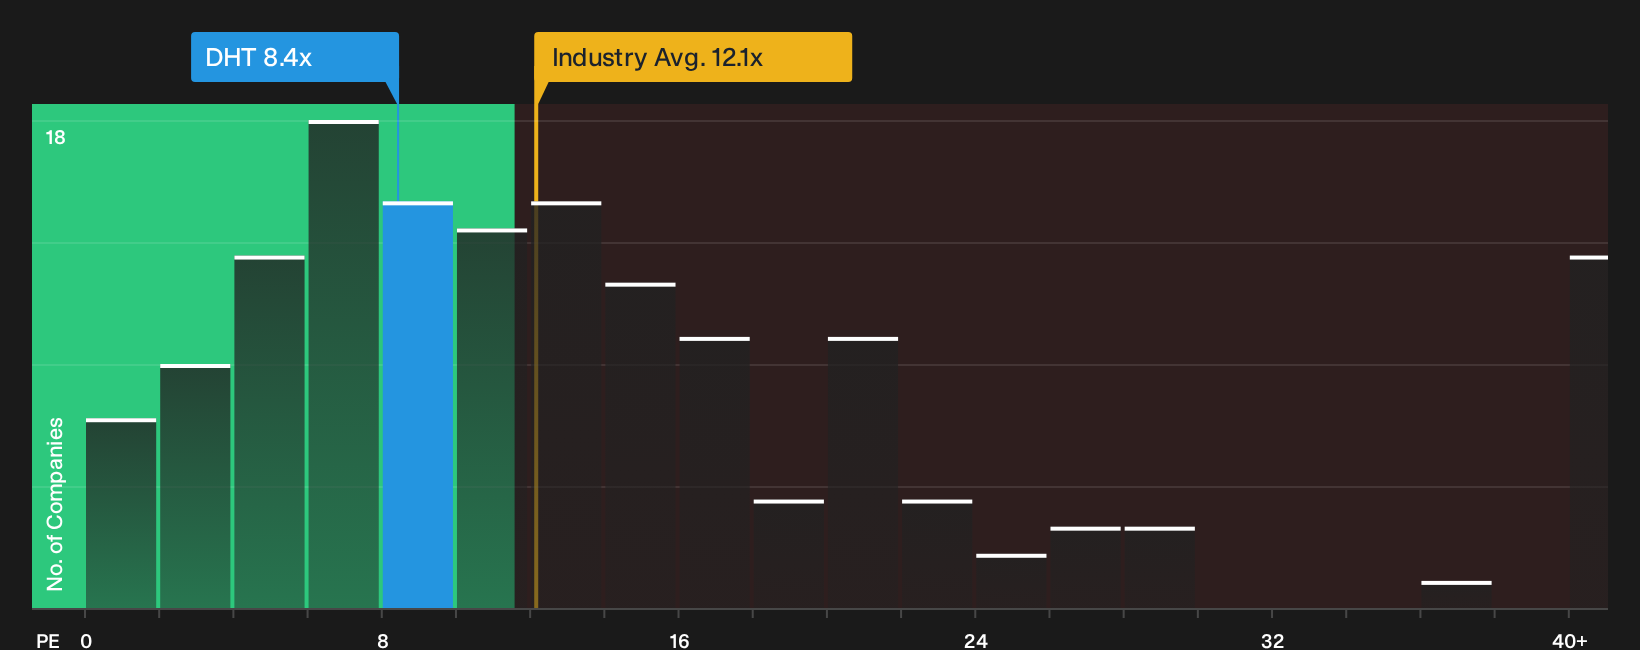
The earlier fair value anchor for DHT Holdings pointed to the shares trading about 13% above an estimated worth of $21.85. A different lens tells a softer story. On a P/E of 8.4x, DHT trades well below the US Oil and Gas sector at 12.1x and peers at 19.7x, yet slightly above its fair ratio of 7.7x, which hints at some valuation tension. Is the market paying a modest premium for quality, or edging into overpayment risk if earnings ease off?
To see how those earnings multiples stack up against the underlying business metrics in more detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Seen enough signals of both optimism and concern around DHT Holdings to start forming your own view, or still on the fence about the balance of risk and reward? Move quickly to weigh the upside against the potential pitfalls by reviewing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond DHT Holdings?
If DHT Holdings has sharpened your focus on risk and reward, do not stop there. Use a few targeted screens to surface fresh opportunities before others spot them.
- Target potential mispricing by scanning companies that currently look attractively valued on key fundamentals through the 29 high quality undervalued stocks.
- Strengthen your income shortlist by reviewing a curated set of high yield payers in the 8 dividend fortresses.
- Reduce portfolio stress by filtering for businesses with cleaner finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com