
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Here's What to Expect From L3Harris Technologies’ Next Earnings Report
Melbourne, Florida-based L3Harris Technologies, Inc. (LHX) is a global defense technology company that develops mission-critical systems spanning communications, sensors, electronic warfare, space, and surveillance. Its technologies serve government and defense customers, supporting national security, civil services, transportation safety, and other complex missions worldwide. The company has a market capitalization of approximately $44.1 billion.
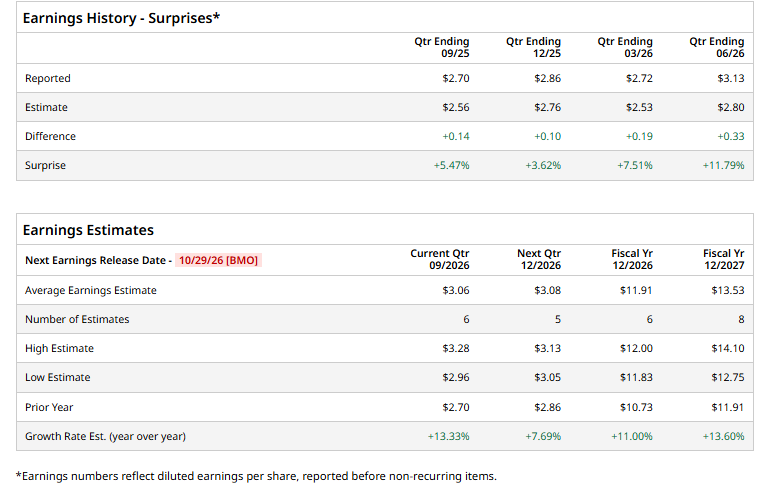
LHX is set to report its Q3 2026 earnings before the market opens on Thursday, October 29, 2026. Ahead of the release, analysts expect diluted EPS of $3.06, up 13.3% from $2.70 in the year-ago quarter. Notably, LHX has exceeded Wall Street’s EPS estimates in each of the past four quarters, which is impressive.
For fiscal 2026, analysts expect the company to report EPS of $11.91, an 11% increase from $10.73 in fiscal 2025. Moreover, EPS is projected to rise another 13.6% year over year to $13.53 in fiscal 2027.
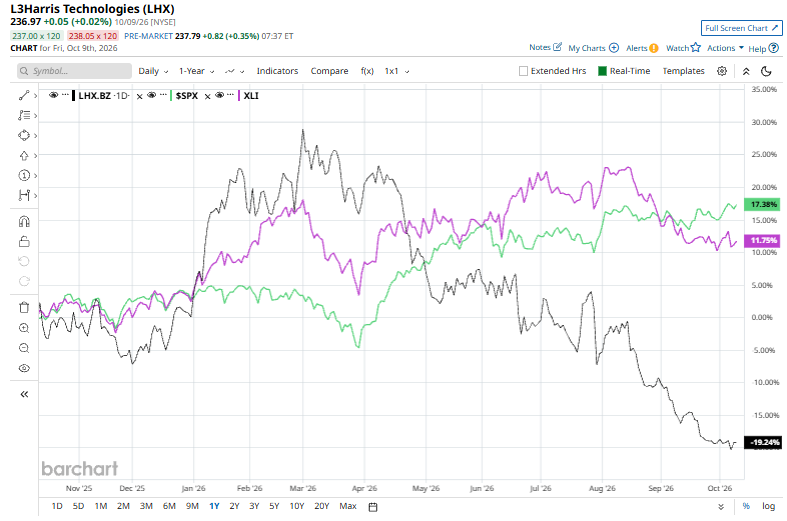
LHX stock has plunged 20.5% over the past 52 weeks, significantly underperforming the S&P 500 Index ($SPX), which gained 16%, and the State Street Industrial Select Sector SPDR ETF (XLI), which advanced 10.4% over the same period.
Recently, on October 1, L3Harris secured a $6 billion-plus, seven-year contract from Lockheed Martin Corporation (LMT) to expand propulsion production for the THAAD missile defense system. The award supports a previously announced plan to quadruple THAAD propulsion output, with L3Harris building a new manufacturing facility and expanding capacity for key propulsion components. The contract, alongside a recently awarded PAC-3 MSE propulsion contract, aligns with the company’s expectations for both programs and reinforces its role in strengthening U.S. missile defense capabilities.
Analysts remain cautiously optimistic on LHX, with the stock carrying a consensus “Moderate Buy” rating. Of the 22 analysts covering the stock, 14 recommend a “Strong Buy,” while the remaining eight recommend a “Hold.” Meanwhile, the average analyst price target of $340.95 implies potential upside of 43.9% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.