
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can ASML Holding (ENXTAM:ASML) Stay Below Fair Value On Earnings?
ASML Holding has been a major beneficiary of investor interest in semiconductor equipment, and the recent share price run raises a straightforward question for you as a shareholder or potential buyer. Is the current market value of ASML really supported by the earnings power that its chipmaking machines can generate over time?
- Over the past 3 years the stock has delivered a 188.3% total return, which puts a lot of expectations about future profit growth into the valuation debate.
- Fresh headlines around demand for ASML's extreme ultraviolet systems for AI chip production, along with strong recent results, can shape how much investors are willing to pay for each euro of earnings the business produces.
- Your read on ASML Holding is one view; the desks covering it have another. See what analysts think ASML Holding's shares could be worth.
The issue now is whether ASML's current share price is justified by its earnings when judged against the Fair Ratio benchmark.
If you want extra context around ASML Holding and AI chip demand before making any moves, run the same lens across a curated list using 92 AI infrastructure stocks.
Is ASML Holding a Bargain on Earnings?
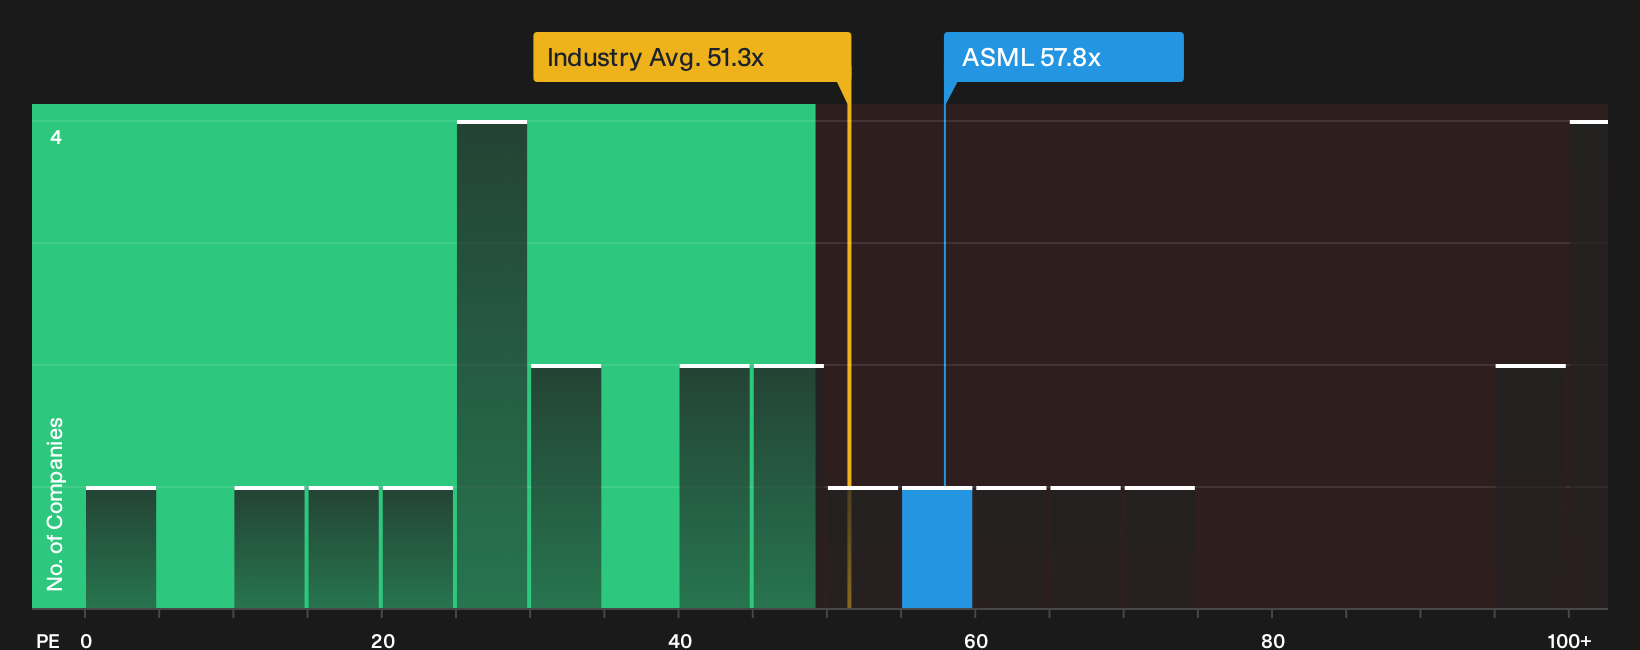
The P/E ratio is a useful lens for ASML Holding because earnings capture how much value its chipmaking tools are producing for shareholders. ASML trades on about 57.8x earnings, which is higher than the wider semiconductor sector on 40.4x and above the 52.0x average for closer peers in the space. That indicates the market is willing to pay a premium for each euro of current profit compared with many other chip equipment stocks.
On Simply Wall St's Fair Ratio framework, which blends factors like growth expectations, profitability, size and risk, ASML's current P/E sits below the level you would expect for those fundamentals, so the shares screen as undervalued on this metric. Because the recent stream of strong AI driven EUV headlines has already lifted sentiment, a P/E that still prices ASML below that tailored benchmark suggests the market may not be fully crediting its earnings power yet. Explore the numbers behind ASML Holding's P/E valuation.
The ASML Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives connect ASML Holding's valuation puzzle to a set of clear what-if stories about its future growth, margins and earnings, so you can see which assumptions would need to hold for the shares to be worth materially more or less than today. Each scenario on the Community page ties a fair value estimate to a defined mix of potential catalysts and risks, which lets you track over time which version of events is actually unfolding.
Community writers looking at ASML Holding are split between those who see limited upside from here and those who think the market is still not fully recognising its earnings power.
Bull case: 10% undervalued
"The market may nevertheless be overestimating the immediate financial threat from Chinese DUV equipment, China generated roughly 29% of ASML’s 2025 sales…"
Discover why this Narrative puts ASML Holding at 10% undervalued.
Bear case: 22% overvalued
"Traditional competitors like Canon or Nikon no longer pose a serious threat in advanced lithography, the real risk comes from geopolitics…"
Explore why this Narrative puts ASML Holding at 22% overvalued.
Before acting on ASML Holding's valuation, there is a final piece to weigh
Valuation tells only part of the ASML Holding story. Recent checks have flagged specific business risks that could change how you view the trade off between price and quality. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com