
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Phillips 66 (PSX) Faces A 10% Premium As Strike Risk And Leadership Change Emerge
Phillips 66 (PSX) is in focus after a union representing 385 workers at its Bayway refinery voted to authorize a strike, while the company also outlined upcoming changes in its refining leadership.
The labor dispute and refining leadership transition come at a time when Phillips 66’s share price has climbed sharply, with a 90-day share price return of 38.09% and a year-to-date share price return of 113.05%, while the 1-year total shareholder return sits at 120.68%. This suggests that recent strength may now be meeting fresh perceptions of operational and governance risk around Bayway and the upcoming management change in the refining segment.
Scan beyond Phillips 66 and stress test your energy exposure against our hand picked 31 resilient stocks with low risk scores, which combine resilience with lower measured risk profiles.
Phillips 66 looks like a powerful, diversified energy business, and the share price has rapidly caught up to that story. After such a strong run, is the stock still offering fair value today, or has enthusiasm gone too far?
Most Popular Narrative: 10% Overvalued
On the most followed view, Phillips 66 screens as overvalued, with a fair value of $251.95 against a last close of $278.18. The current price already bakes in a lot of execution on midstream cash flows, cost cuts and capital returns.
Midstream and marketing activities built around over 1 million barrels per day of NGL fractionation capacity at full or above full utilization and record LPG exports are expected to keep generating largely fee based cash flow. This can underpin earnings stability and the ability to fund dividends and sustaining capex.
See why 48 investors see Phillips 66 as 10% overvalued.
Result: Fair Value of $251.95 (OVERVALUED)
Still, two pressure points could upset the Phillips 66 story: prolonged derivative losses that absorb cash, and refinery or labor disruptions that hit throughput and costs.
Find out about the key risks to this Phillips 66 narrative.
Another View: Phillips 66 Through The Cash Flow Lens
While the popular narrative tags Phillips 66 as about 10% overvalued at a fair value of $251.95, the Simply Wall St DCF model paints a very different picture. On that approach, PSX at $278.18 sits well below an estimated future cash flow value of $483.25, which implies a wide valuation gap that long term investors will need to reconcile for themselves.
Look into how the SWS DCF model arrives at its fair value.
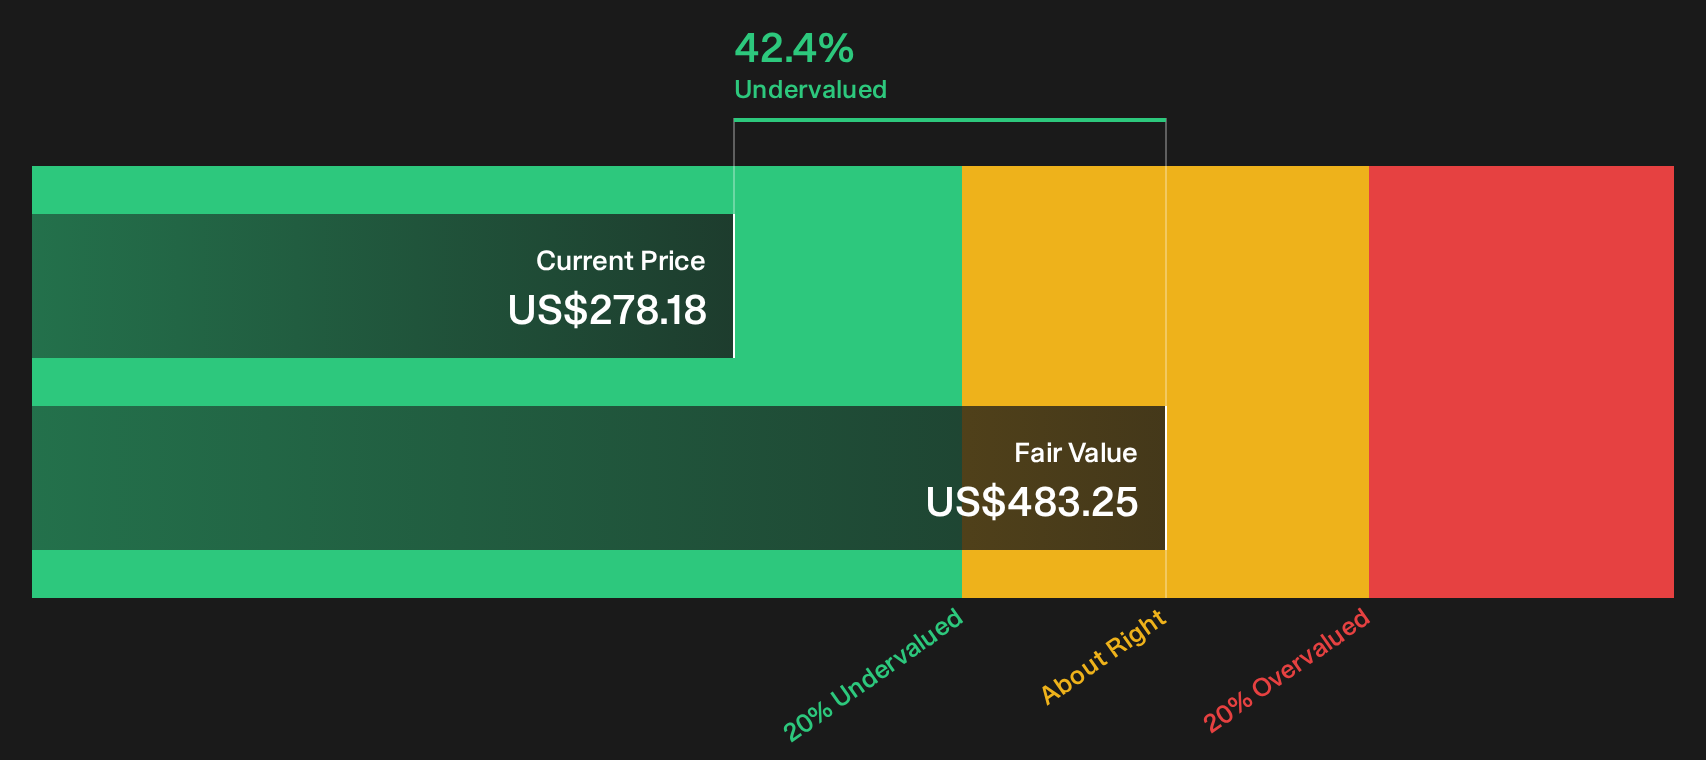
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Phillips 66 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of investors are split on Phillips 66 right now, with some focused on risks and others on the upside potential. Consider moving quickly, reviewing the data in detail, and weighing both the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Phillips 66?
Do not stop at Phillips 66. Broaden your watchlist with a few focused stock ideas that match different goals, risk levels, and income needs.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive entry points through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that feature resilient cash flows and higher yields inside the 8 dividend fortresses.
- Protect your downside by filtering for companies with robust balance sheets, steady cash generation, and cleaner risk profiles using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com