
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Everpure (P) Could Be 14% Below Fair Value Following Its Data Primacy Update
Everpure (P) just rolled out a fresh wave of Data Primacy features that tie its storage hardware more tightly to AI workloads, giving enterprise customers new tools to manage and contextualize their information.
That backdrop of Data Primacy updates lands while Everpure’s share price has been on a sharp run, with a 30 day share price return of 57.35% feeding into a 123.87% year to date move and a 5 year total shareholder return of 495.57%. This indicates strong momentum but also a higher bar for how future execution and valuation expectations line up.
Capitalize on Everpure’s AI data momentum by lining up your next ideas from a curated group of 92 AI infrastructure stocks.After a move like Everpure’s, some investors lean into the momentum while others wait for the chart to cool off. The real tension sits in the numbers. Does the current valuation already price in this AI data story?
Most Popular Narrative: 14% Undervalued
Everpure last closed at $154.49 while the most followed narrative on the stock pins fair value closer to $180. That gap frames the AI storage re-rating debate more sharply than any short term share price move.
The market is pricing Everpure as an enterprise storage company. That is the wrong category. Once two or three analysts figure out what is actually happening inside this business, the multiple closes toward AI infrastructure peers, and the stock moves $70 to $80 from here without a single change in fundamentals. Let me walk through why.
See why 47 investors see Everpure as 14% undervalued.
According to Degen_GCR, the margin story underpins that higher fair value. In the narrative, Everpure is framed as an all flash infrastructure play with DirectFlash hardware, Purity OS, and Evergreen subscriptions working together to support data hungry AI workloads, which helps explain why a discount rate of 8.42% is applied and still results in a fair value above the current $51.5b market cap.
The same thesis leans heavily on cash generation and growth forecasts already visible in public filings. Revenue of $4.26b and net income of $253.3m are paired with annual revenue growth of 23.3% and earnings growth expectations of 38.6% a year, which is above both the wider US market and the US tech sector. On that view, a fair value of $180 implies the market is not fully reflecting long duration cash flows tied to AI infrastructure style demand.
Result: Fair Value of $180 (UNDERVALUED)
Still, the Everpure thesis can wobble if hyperscale demand underwhelms or if rivals like VAST Data and Weka win a bigger share of AI storage budgets.
Find out about the key risks to this Everpure narrative.
Another View On Everpure’s Valuation
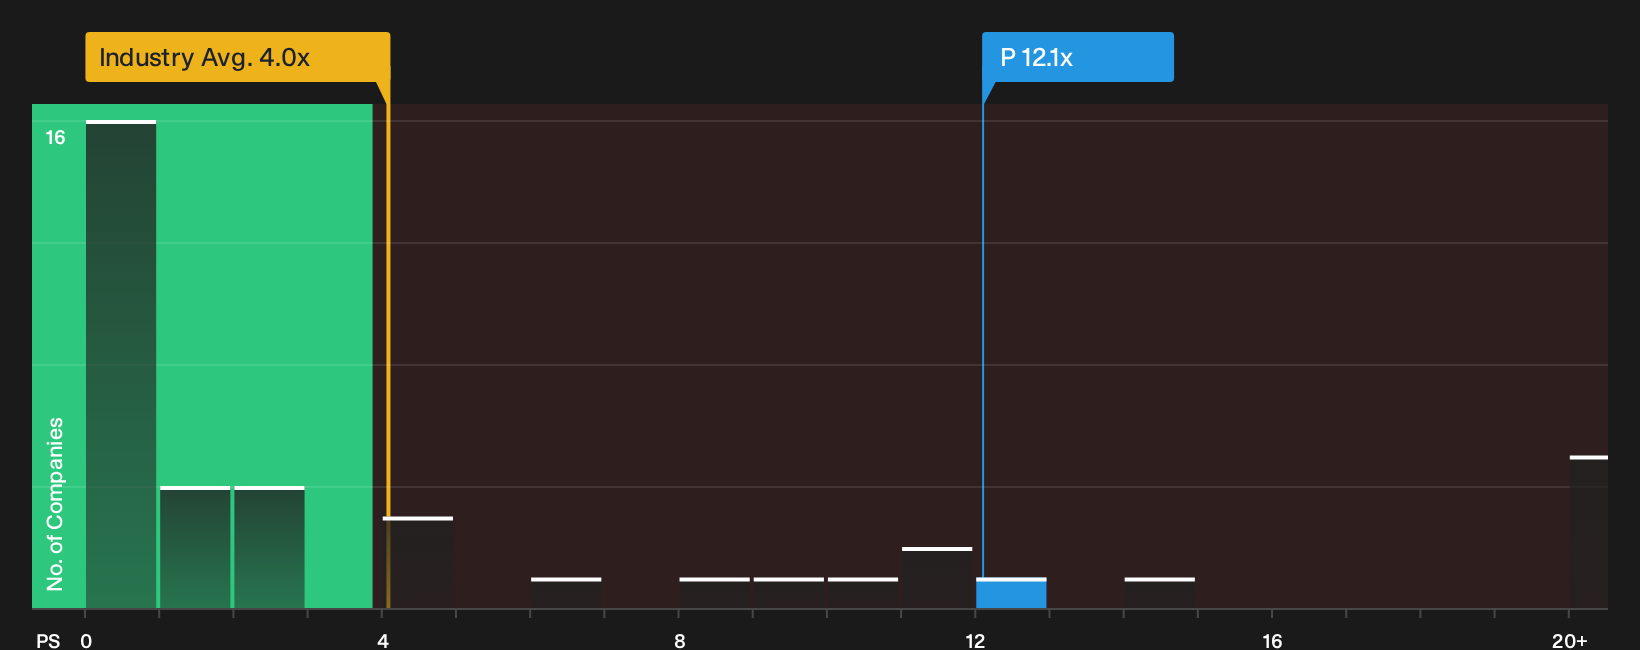
On simple P/S math, Everpure looks expensive. The stock trades around 12.1x sales compared with 4x for the broader US tech sector and 5.2x for peers. This points to clear downside risk if sentiment cools. Yet the fair ratio sits at 20.3x, which implies the market could still shift higher. Which version of this story do you trust more?
To see how this pricing gap fits into the wider picture on quality, growth, and risk, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Everpure’s story so far, with real upside potential but also flagged concerns. Move quickly, review the data yourself, and pressure test both sides against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Everpure?
Do not stop your research with Everpure. Broader context across sectors and styles can sharpen your conviction and help you avoid concentration risk.
Use the Simply Wall Street Screener to pressure test your thinking against other opportunities before you commit fresh capital.
- Target stability first by scanning a 31 resilient stocks with low risk scores that can help you spot businesses where risk scores stay on the lower side.
- Hunt for quality at a discount with the 20 high quality undiscovered gems that highlights companies with strong fundamentals that are not widely followed yet.
- Anchor your portfolio with staying power by reviewing a 8 dividend fortresses that focuses on higher yielding payers with an income profile above 5%.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com