
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Acciona (BME:ANA) Fairly Valued Following Its Record €54b Backlog?
Acciona (BME:ANA) has drawn fresh attention after reporting a record-high infrastructure backlog, tying long-term revenue visibility to large projects and concessions while margins and cash generation still face pressure.
Acciona’s share price has softened over the past quarter, with a 90 day share price return down 15.9%. However, the year to date share price return is 10.9% and the 1 year total shareholder return is 17.0%. This signals longer term momentum that contrasts with recent weakness around €211.4 as investors reassess growth potential and contract risk around that record backlog.
Scan how Acciona compares with other infrastructure heavy, cash flow focused businesses by reviewing our hand picked list of solid balance sheet and fundamentals (202 results) in the same space.
Acciona now offers a record project pipeline and a softer share price, a mix that can either reward patient buyers or signal a value trap at about €211.4. How does the valuation compare with that risk profile?
Most Popular Narrative: 3% Undervalued
On the prevailing narrative, Acciona’s fair value of €218.31 sits modestly above the last close at €211.4, so the price gap is narrow and depends heavily on how much faith you place in future margin improvement and that huge project pipeline.
ACCIONA's infrastructure backlog reached an all-time high of €54 billion, providing a strong foundation for future revenue growth through large-scale projects and concession awards. This is expected to drive an increase in revenue and operating margins as projects come to fruition.
See why 7 investors see Acciona as 3% undervalued.
That widely followed storyline is built on a 7.9% discount rate, relatively modest annual revenue growth assumptions of about 1.4%, and profit margins rising from 1.6% to roughly 3.0%. At a fair value of €218.31, it implies Acciona trades on a future P/E of 19.9x by 2029, compared with a current P/E of 31.3x and an industry level cited at 20.4x.
Analysts behind this view also factor in earnings climbing from €360.0m to €681.8m by around October 2029, with a wide spread between the most optimistic and most cautious forecasts, and a gradual reduction in the share count as buybacks shrink the equity base. The relatively small 3.1% gap between the current share price around €211.4 and the €218.31 target suggests they see Acciona as broadly in line with their expectations rather than a clear bargain or an obvious excess.
Result: Fair Value of €218.31 (ABOUT RIGHT)
Still, any prolonged period of low power prices or weaker conditions in Spain that hit Acciona Energia’s EBITDA could quickly challenge this “about right” valuation story.
Find out about the key risks to this Acciona narrative.
Another View: Acciona Looks Expensive On Earnings
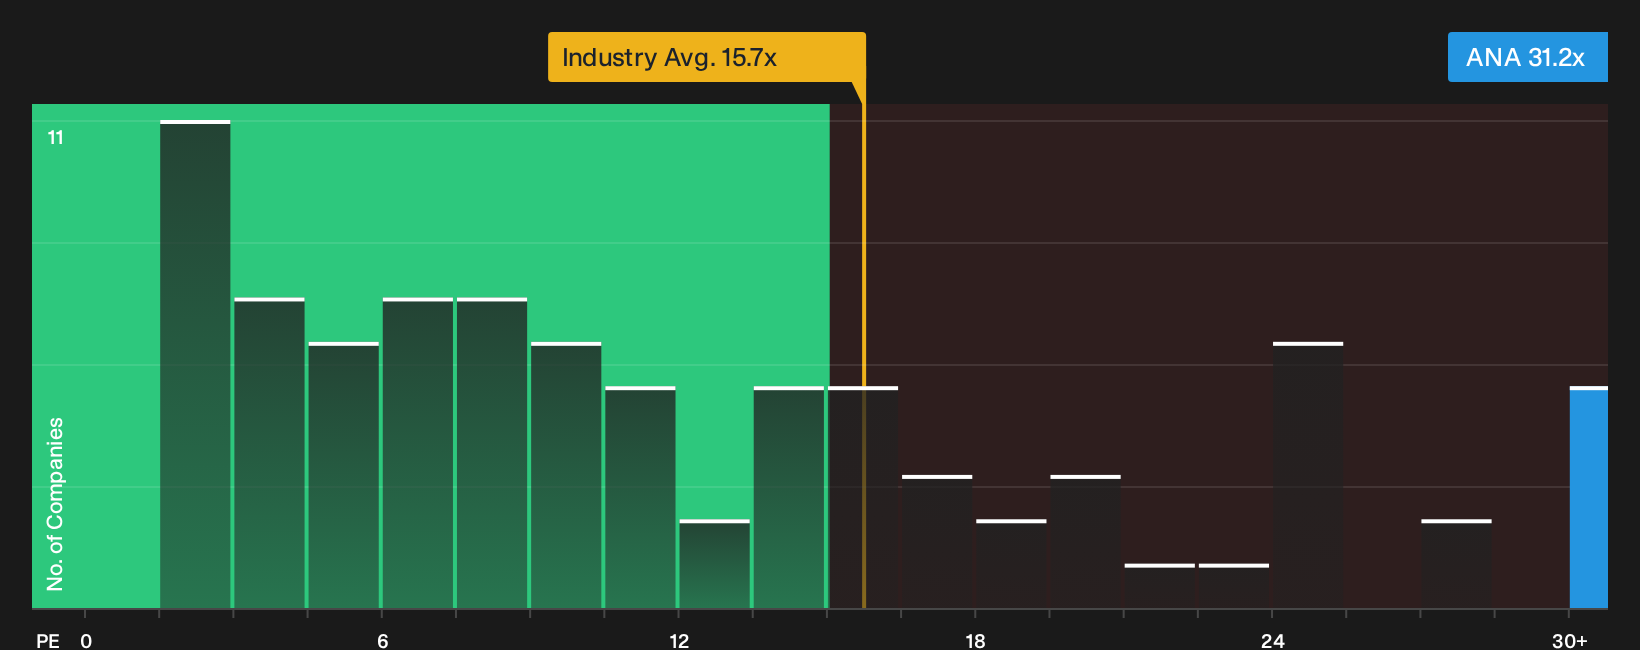
Acciona’s fair value story around €218.31 leans on margin gains and a long project pipeline. On plain earnings metrics, the picture is tougher. The stock trades on a P/E of 31.2x, while the estimated fair ratio is 22x and the European Electric Utilities group is around 15.7x.
That gap means you are paying a premium both to peers at 15.7x and to the 22x fair ratio that the market could move toward if sentiment cools. The question is simple. Are you comfortable paying up at 31.2x when growth forecasts are only mid single digit for revenue and low double digit for profit?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Acciona is mixed, with a huge backlog on one side and valuation questions on the other, so check the data yourself and decide where you land. To weigh both sides in one place, start with the 1 key reward and 5 important warning signs.
Looking for more Acciona-sized investment ideas?
If Acciona has you thinking harder about quality, do not stop here. Fresh ideas often come from comparing very different setups and return profiles across the market.
- Target resilience by filtering for companies that pair strong finances with tempered risk using the 224 resilient stocks with low risk scores.
- Spot potential mispricings by reviewing the 179 high quality undervalued stocks that combine sturdy balance sheets with attractive fundamentals.
- Hunt for future leaders early by scanning the 618 high quality undiscovered gems that many investors have not focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com