
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Procter & Gamble (PG) Fairly Valued As Evercore Sees E Commerce Momentum?
Evercore ISI’s upgrade of Procter & Gamble (PG), tied to improving U.S. e-commerce share on platforms like Amazon and a reassessment of cost pressures, has pushed this consumer staple back into the spotlight for investors.
Procter & Gamble’s recent upgrade lands on top of a steady run, with a 7-day share price return of 3.62% and a 30-day move of 4.10% to about $151, while the 1-year total shareholder return of 5.55% points to moderate, longer term progress rather than a surge in momentum.
Scan Procter & Gamble’s upgrade in context by comparing it with 31 resilient stocks with low risk scores that, like PG, balance steady fundamentals with an emphasis on resilience over headline-grabbing swings.
The recent climb in Procter & Gamble’s share price could be investors warming back up to the story, or it could be the business quietly justifying a higher tag. How far does that show up in the current valuation?
Most Popular Narrative: 41% Overvalued
That detailed valuation work pegs Procter & Gamble’s fair value at about $107.50, well below the recent $151.23 close. This frames Evercore’s upgrade against a much more conservative long term view.
Despite this, I feel the future for this company still holds some friction by the appearance of fierce competition, pressuring Procter & Gamble to reduce its prices and by consequence its operating margins. Also, unless something exceptional happens, given the maturity of the business, I see its revenues grow below or at the economy growth rate.
See why 34 investors see Procter & Gamble as 41% overvalued.
Result: Fair Value of $107.52 (OVERVALUED)
Still, a higher US$151 share price and rising competition in core categories could compress Procter & Gamble’s margins and weaken the overvaluation argument.
Find out about the key risks to this Procter & Gamble narrative.
Another View On Procter & Gamble’s Value
That narrative-driven fair value of about $107 for Procter & Gamble clashes with our DCF model, which points in the opposite direction. On this view, the stock at $151.23 trades around 23% below an estimated future cash flow value of $196.96, suggesting the overvaluation story is not so straightforward. Which lens do you trust more when cash flows and sentiment diverge like this?
To see how the assumptions line up against each other in detail, take a closer look at how the SWS DCF model is built for Procter & Gamble, from growth inputs through to discount rates, and decide which version of “fair” feels more realistic for you as an investor. Look into how the SWS DCF model arrives at its fair value.
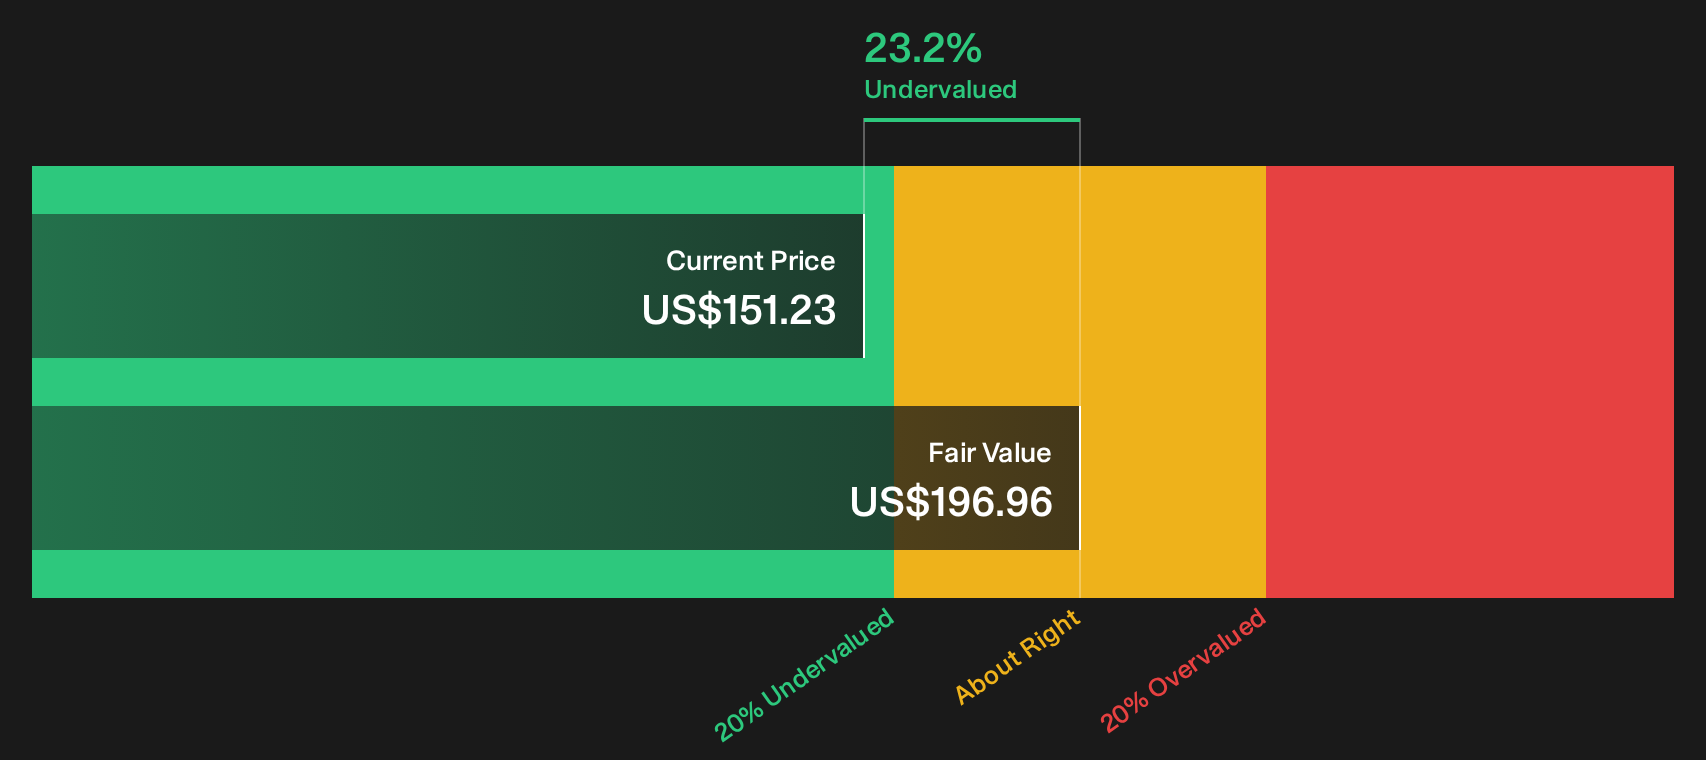
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Procter & Gamble for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation, risk and reward make Procter & Gamble a stock you need to judge on your own terms, so move quickly from headline takes to the underlying numbers and weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Procter & Gamble?
If Procter & Gamble has you thinking harder about price versus quality, broaden your watchlist now or risk missing opportunities sitting in plain sight.
- Target stronger value potential by scanning companies that screen as 29 high quality undervalued stocks and may offer more attractive entry points than headline consumer staples.
- Strengthen your portfolio’s defense by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you lean toward businesses with healthier financial foundations.
- Get ahead of the crowd by searching for 20 high quality undiscovered gems that combine solid fundamentals with lower visibility on the market radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com